

How to enjoy our new magazine:
Just scroll!
Click or tap the table of contents icon in the menu bar to find any article.
Read any article by clicking or tapping the read full article button below each article intro.
Jump back to your previous browsing spot from any article using the menu bar or back to issue button.
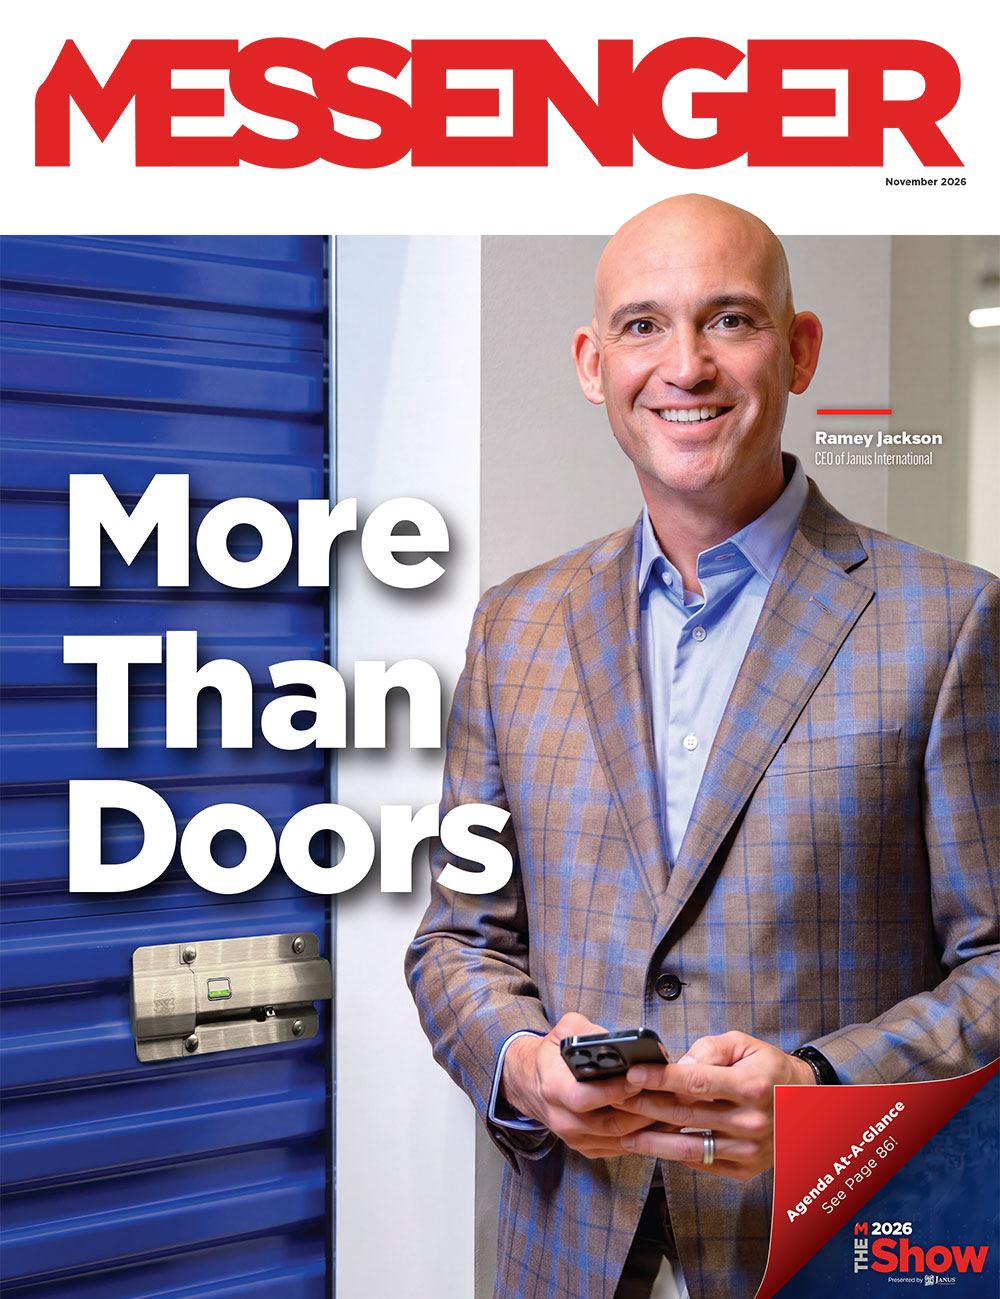



-
Breathe New Life Into Aging Facilities With Door ReplacementsPage 14
-
Google Business Profile Posts For Local SEOPage 18
-
Sorting Through The Noise Before You Buy Into AIPage 22
-
Your New Opportunity May Be RetentionPage 26
-
Choosing A Management Model By Workload, Not Door CountPage 32
-
The Next Chapter Of Cancer ResearchPage 36
Experience
Local Expertise
Not Just a Builder

-
Page 50
-
Weakened Fundamentals Mark The End Of SummerPage 52
-
Survey Data Shows Shift In Self-Storage DemandPage 62
-
It’s The Only Ad Number That MattersPage 70
-
U-Haul Migration Trends Show Generations Taking Different PathsPage 72

-
Building A Unit Mix Strategy That WorksPage 114
-
Asia’s Self-Storage Market Is Organized ChaosPage 116
-
Brazilian Self-Storage Is Growing On Its Own TermsPage 124
-
10 Federal Storage in Lake Worth, TexasPage 128
Why ManagementPlus? Extra Space Storage is the largest third-party management company for a reason. They don’t differentiate between their own facilities and yours. When you partner with Extra Space, you’ll get the same resources that make their properties so successful.
-
Turning Disposition Into DollarsPage 130
-
Flock And Other ALPR Cameras Secure Properties But Raise ConcernsPage 134
-
The Market That Breaks The Pricing PlaybookPage 138
-
Tracking And Utilizing Predictive Localized Demand SignalsPage 142
-
Using Cost Segregation As A Powerful Tax Savings And Financial ToolPage 144
- Chief Executive Opinion by Travis Morrow8
- Publisher’s Letter by Poppy Behrens11
- Meet The Team12
- Women In Self-Storage: Claire Shamsid-Deenk by Alejandra Zilak41
- Who’s Who In Self-Storage: Scott Levy by Brad Hadfield47
- Innovation Spotlight: Ai Lean by Brad Hadfield148
- Self Storage Association Update151
- The Last Word by Travis Morrow152
ARCO brings unmatched scale and expertise to every project. With 48 offices, 30+ years of experience, and 18+ million square feet of Class-A self-storage delivered nationwide, we combine national reach with local insight to help owners scale confidently while protecting schedule, budget, and long-term asset value.
For the latest industry news, visit our comprehensive website, ModernStorageMedia.com.





CEO of MSM and Storelocal Corporation,
President of National Self Storage
f you’re holding this magazine, there’s a good chance you’re standing inside the Georgia World Congress Center with a badge around your neck. Welcome to THE Show.
We built this week for the entire industry. Here’s how I’d spend it.
Start your mornings in the Georgia Ballroom. Our keynotes come from outside the bubble on purpose: Aoife Roche on AI Wednesday, Scott Jennings on the midterms Thursday, and Congressmen Jefferson Shreve and Troy Downing on Friday. Then, pick a pillar. Operations, Data, Development, and Investment run at the same time, so split up your team and compare notes over lunch. Chipper Jones closes out Wednesday afternoon.
Make time for the Deal Room on Wednesday and Thursday. It’s a different kind of room, a front-row look at how deals come together, and I don’t think you’ve seen anything like it.
Walk the trade show floor with a real problem in your pocket. The people in those booths solve problems for a living, so give them a hard one.
The Deep Blue Welcome Reception will be held at the nearby Georgia Aquarium (transportation included) in the Grand Oceans Ballroom, featuring two large aquatic observation windows. Picture yourself connecting with friends and colleagues over cocktails and a delicious collection of savory bites by Wolfgang Puck as whale sharks and playful belugas glide by!
None of this happens without Janus International, our title sponsor, and every sponsor on the floor. They bet on this week before any of us had seen it, so stop by their booths and say thank you.
And to my team: Thank you. You built this while still putting out a magazine every month, and you sweated details nobody here will ever notice. I’m proud of every one of you.
One more ask: We’re considered one of the friendliest industries around, so prove it. Meet someone you’d never call. The best relationships in this business start with a handshake in a hallway.
I’m closing things out Friday morning. Find me before then and tell me what you think, including what we got wrong. That’s how next year gets better.
I’m glad you’re here.
Welcome to Atlanta.
-
PUBLISHER
Poppy Behrens
-
Director Of Sales & Marketing
Lauri Longstrom-Henderson
(800) 824-6864 -
Creative Director
Carlos Padilla
(800) 352-4636 -
Editor
Erica Shatzer
-
Lead Writer / Web Manager
Brad Hadfield
-
Storelocal® Media Corporation
Travis M. Morrow, CEO
-
Websites
-
Visit Messenger Online!
Visit our Self-Storage Resource Center online at
www.ModernStorageMedia.com,
where you can browse our paid publications, research archived articles, sign up for a magazine subscription, submit a change of address, and more. 
- All correspondence and inquiries should be addressed to:
MSM
PO Box 608
Wittmann, AZ 85361-9997
Phone: (800) 352-4636
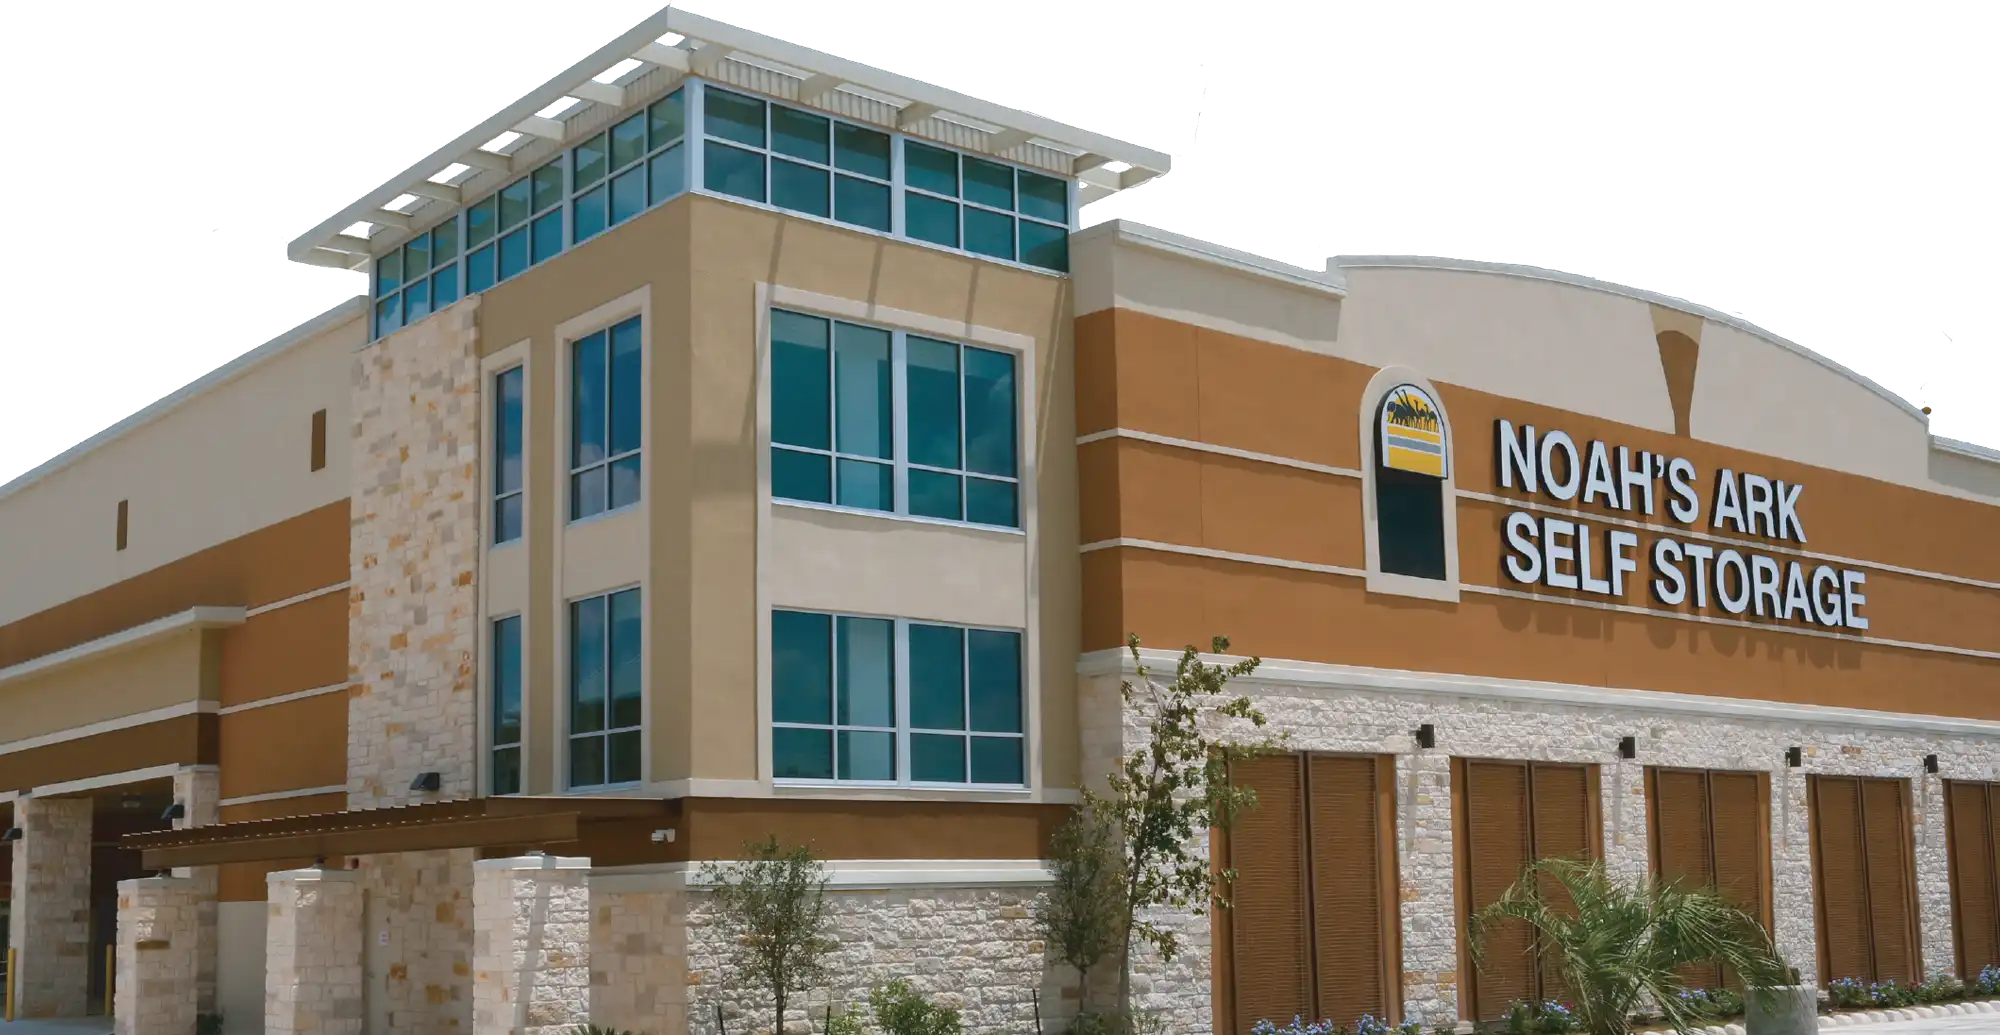
Invest with confidence in a family-owned and operated self-storage brand backed by 40 years of proven experience. Built on trust, stability, and hands-on management, our company has thrived across market cycles while delivering consistent value.
Join a legacy of smart growth and reliable returns in an essential, resilient industry.
210-405-6695
theparhamgroup.com

f you’re reading this from your hotel room in Atlanta over coffee before the first session, or somewhere inside the Georgia World Congress Center between events, then something we have been planning, talking about, and working toward for months has finally happened. THE Show is finally here.
After months of meetings, phone calls, emails, schedules, changes, more changes, and enough moving pieces to make my head spin, THE Show is no longer something marked on a calendar. It’s happening. And I must admit, there is something pretty incredible about finally being able to say that.
By now, people from across the industry are gathering in Atlanta. Old friends are finding each other in hotel lobbies. People who have spent months talking by email and Zoom are finally shaking hands. Exhibitors are welcoming attendees to their booths. Speakers are preparing to take the stage.
That may be what I’m looking forward to most. We spend so much of our lives communicating through screens. We hold meetings from different states, send messages at all hours, and conduct business with people we may rarely see in person. For a few days in Atlanta, we get to change that. We get to be together.
Yes, there will be plenty to learn. There will be business conducted, deals discussed, and ideas exchanged. There will undoubtedly be debates, disagreements, and more than a few conversations that continue long after a session ends.
But I hope there will also be laughter. I hope there are unexpected introductions. I hope someone sits down next to a stranger and leaves Atlanta with a new friend, customer, mentor, or business partner.
And I hope we all remember to have some fun. Enjoy the Georgia Aquarium. Dress up and join us for the awards gala. Walk the trade show floor. Stay for one more conversation. Ask the question you’ve been wanting to ask. Introduce yourself to someone whose name you’ve known for years but have never actually met.
Most of all, make these few days your own.
For months, we’ve talked about THE Show and counted down the days until Atlanta. Now the planning is behind us, the doors are open, and all of you are here. There’s nothing left for me to tell you about what THE Show is going to be. Now we get to experience it together. Welcome to Atlanta. Welcome to THE Show. Let’s make it unforgettable!
Publisher
Welcome to THE Show.
Let’s make it unforgettable!
f you’re reading this from your hotel room in Atlanta over coffee before the first session, or somewhere inside the Georgia World Congress Center between events, then something we have been planning, talking about, and working toward for months has finally happened. THE Show is finally here.
After months of meetings, phone calls, emails, schedules, changes, more changes, and enough moving pieces to make my head spin, THE Show is no longer something marked on a calendar. It’s happening. And I must admit, there is something pretty incredible about finally being able to say that.
By now, people from across the industry are gathering in Atlanta. Old friends are finding each other in hotel lobbies. People who have spent months talking by email and Zoom are finally shaking hands. Exhibitors are welcoming attendees to their booths. Speakers are preparing to take the stage.
That may be what I’m looking forward to most. We spend so much of our lives communicating through screens. We hold meetings from different states, send messages at all hours, and conduct business with people we may rarely see in person. For a few days in Atlanta, we get to change that. We get to be together.
Welcome to THE Show.
Let’s make it unforgettable!
But I hope there will also be laughter. I hope there are unexpected introductions. I hope someone sits down next to a stranger and leaves Atlanta with a new friend, customer, mentor, or business partner.
And I hope we all remember to have some fun. Enjoy the Georgia Aquarium. Dress up and join us for the awards gala. Walk the trade show floor. Stay for one more conversation. Ask the question you’ve been wanting to ask. Introduce yourself to someone whose name you’ve known for years but have never actually met.
Most of all, make these few days your own.
For months, we’ve talked about THE Show and counted down the days until Atlanta. Now the planning is behind us, the doors are open, and all of you are here. There’s nothing left for me to tell you about what THE Show is going to be. Now we get to experience it together. Welcome to Atlanta. Welcome to THE Show. Let’s make it unforgettable!
Publisher
Contact Lauri Longstrom-Henderson at Lauri@modernstoragemedia.com for more information.

s self-storage owners and operators look toward 2027, the challenge is familiar: maximizing asset value while controlling expenses. Construction costs remain elevated, labor shortages continue to impact project timelines, and customers still expect facilities to look clean, modern, and secure.
The good news is that improving an aging facility does not always require a major capital investment. In fact, one of the most cost-effective improvements available today is often hiding in plain sight: replacing old, worn, and failing roll-up doors.
For many operators, door replacement offers an opportunity to dramatically improve curb appeal, enhance customer satisfaction, reduce maintenance costs, and extend the life of existing facilities at a fraction of the cost of major renovations.
As facilities enter another year of heightened competition, smart maintenance decisions may deliver a better return on investment than expensive expansions.
While owners often focus on large-ticket investments such as office renovations, fencing upgrades, or technology enhancements, storage doors represent a significant portion of what customers actually see. A facility with hundreds of units may have hundreds of opportunities to make a positive first impression. Conversely, every damaged or worn door can become a visual reminder that maintenance has been deferred. Replacing aging doors can provide an immediate transformation that modernizes an entire property without altering the facility footprint.
As doors age, maintenance requirements often increase significantly. Operators may encounter:
- Misaligned tracks,
- Damaged springs,
- Bent panels,
- Failing latches,
- Rust and corrosion,
- Increased service calls, and
- Difficulty operating doors.
While individual repairs may seem relatively inexpensive, the cumulative cost over time can add up quickly. Maintenance teams can find themselves repeatedly addressing the same issues, diverting resources away from other critical facility improvements. In many cases, operators are spending money to maintain equipment that has already exceeded its most productive life cycle. Door replacement shifts the focus from ongoing repairs to long-term reliability.
Second, replacement doors may reduce ongoing maintenance expenses. Modern door designs frequently incorporate improved materials, finishes, and construction methods that are resistant to corrosion, fading, and wear.
Third, new doors can improve operational consistency. Fewer service interruptions mean less frustration for tenants and less demand on facility staff.
The result is a relatively straightforward improvement that can generate operational savings while supporting revenue growth. For operators preparing capital improvement budgets for 2027, that combination can make door replacement one of the most attractive maintenance investments available.
That reality has shifted attention toward asset preservation. Replacing aging doors allows owners to refresh facilities without the disruption or cost associated with major redevelopment efforts. Rather than spending millions on expansion or reconstruction, operators can often achieve meaningful improvements through targeted upgrades that address highly visible and heavily used components.
Doors fall squarely into that category. They represent one of the most frequently operated pieces of equipment on self-storage property. Every rental cycle creates wear. Over years and decades of service, that wear inevitably accumulates.
A disciplined replacement strategy helps facilities maintain a modern appearance while avoiding the operational risks associated with aging infrastructure.
Upgrading older doors provides an opportunity to improve both real and perceived security. Customers notice equipment that appears solid, well-maintained, and professionally installed. Facility owners benefit from the confidence that comes with modern construction standards and dependable performance. In an industry built on trust, these factors continue to influence customer retention and long-term facility reputation.
The most successful investments are often those that deliver value year after year through reliability, appearance, and reduced maintenance demands. Many operators have found that selecting doors engineered for durability and lower maintenance can significantly reduce lifecycle costs.
For example, Central States’ Sentry™ line of doors has gained attention among facility owners because of the innovative design that extends optimum door life while also eliminating some forms of annual maintenance. These product enhancements can help support long-term maintenance goals while preserving facility appearance.
Just as importantly, modern door systems can often be installed as part of phased improvement strategies, allowing owners to spread investments over time while steadily improving facility performance.
While large-scale redevelopment projects will continue to play a role in some markets, many owners will discover that smaller, targeted investments can generate impressive returns. Door replacement is one of those opportunities.
It improves curb appeal, enhances customer confidence, reduces maintenance demands, and extends the useful life of existing assets, all without the expense and disruption of major construction projects.
For operators building maintenance budgets for 2027, the question may not be whether aging doors should be replaced but whether continuing to maintain outdated doors is costing more than they realize.
In an industry where every dollar matters, replacing old doors can be one of the simplest ways to give a facility new life while protecting long-term profitability.

Google Business Profile (GBP) is the primary digital gateway for modern renters and the most critical asset for local customer acquisition.
Think of your GBP as a “digital storefront window” on a digital street. If the display in a physical window never changes, the town guide assumes the shop is dormant or closed. However, when you regularly publish fresh GBP posts, the town guide gains the confidence to enthusiastically point visitors toward your business. Regular posting (updates, offers, and events) signals to the algorithm that your facility is active, organized, and ready for recommendation.
- Traditional Search is focused on matching individual words and keyword density.
- Modern AI Search interprets natural language, analyzes photos via computer vision, and assesses entity trust and neighborhood sentiment.
Fact Density (The First 30 percent Rule)
- Weak – “We are the absolute best storage company in town. We love our customers and offer amazing rates for everyone!”
- Strong – “Our climate-controlled 10-by-10 units in downtown Dallas maintain a constant temperature between 60 degrees and 78 degrees Fahrenheit. No security deposit required for new renters.”
Computer Vision Verification
- Strategic Tip: Rename your image files before uploading to include localized keywords, such as self-storage-near-navy-pier-chicago.jpg.
- Be location-specific in your photo and post descriptions.
Attribute Mapping
- Security – Keypad entry, gated access, security cameras, etc.
- Accessibility – Wheelchair-accessible entrances, ground-level units, etc.
- Amenities – Climate control, on-site moving supplies, etc.
- Unit Features – Highlight specific square footage (e.g., 5-by-5 versus 10-by-20) and explain how climate control protects delicate items from humidity.
- Trust Signals – Post photos of new security upgrades, such as upgraded corridor lighting or 24/7 gate monitors.
- Localized Incentives – “First Month Free for residents near Local Landmark Name.”
- Bundle Packs – Promote “Moving Starter Kits” including boxes, bubble wrap, and tape to increase ancillary revenue.
EVENTS (TIME-BOUND ACTIVITIES)
- Community Involvement – Highlight local sponsorships or charity drives at the facility.
- Facility Tours – “Open House: Walk through our new temperature-controlled wing this Saturday.”
- Think FAQs – Forget keywords. Think Frequently Asked Questions.
- Antidote to High Ad Spend – Regular posting builds organic authority, reducing your reliance on expensive Google Ads. Needless to say, keep track of your competitors and match or beat what they’re doing. If they are doing Google Ads, you should too.
- Increased Conversion Rate – Avoid the “zero-click” search phenomenon. Let customers find your pricing and features directly in GBP posts without ever having to visit your website.
- Frictionless Lead Gen – Strategic call-to-action (CTA) buttons like “Book” or “Learn More” target mobile users, who represent over 50 percent of online leases, at the exact moment of high intent.
- Updates – Highlight specific features or moving tips, such as explaining how your climate-controlled units protect sensitive items like leather furniture during humid summer months. These can be blog posts or image posts. Set up a tool like Dlvr.it to automatically share your blog posts to your GBP.
- Offers – Share limited-time promotions with precise pricing, dates, and redemption steps, like offering the first month free on a 10-by-10 drive-up unit when reserved online. Make sure to include a clear call-to-action button, such as “Book” or “Get Offer,” that links directly to your reservation page so customers can rent a unit immediately.
- Events – Announce community activities, seasonal events, and auctions. Include all pertinent information.
Like I’ve covered in my past articles, instead of just matching keywords, AI looks for trustworthy “fact density” to answer specific customer questions about pricing, current promotions, or unique facility features. Furthermore, when you post regularly, it sends a strong signal to Google that your business is actively managed and reliable. Thus, this increases your chances of being recommended by the AI over competitors with stagnant profiles.
Nevertheless, GBP is not social media. It’s strictly business related. Google will remove posts that are not relevant to your business. For instance, if a regular customer’s kid makes the honor roll, skip GBP. Save posts like that for Facebook and Instagram. Also, don’t publish the same thing over and over again. GBP isn’t like a social media feed that includes other people’s content. It’s yours alone.
By the way, did you know you can now connect your GBP to your Google Analytics account? Go to Settings, then Product Links, and look for Google Business Profile and follow the instructions to link it.
As always, if you need help with any of your digital marketing, feel free to book a free discovery call, so we can brainstorm some ideas.


very vendor in self-storage right now has an AI pitch. Some of them are genuinely useful. A lot of them are not. And if you are an operator trying to figure out which is which, the noise level is high enough that it is easy to either dismiss all of it or believe too much of it.
Neither of those responses serves you particularly well. So here is an attempt at a more grounded take on where AI actually stands in self-storage operations today, what is working, what is oversold, and how to tell the difference.
What that means in practice is that the fear of being left behind and the fear of getting burned by a bad product are both reasonable concerns to have simultaneously. You should not ignore AI because some of the vendors are questionable. You also should not sign contracts because someone told you the world would pass you by if you didn’t.
The right posture is somewhere in the middle, which is not the most exciting advice, but it is the accurate one.
At STORE, the most meaningful near-term application has been on the reporting side. Instead of having people spend hours pulling delinquency data, leasing activity, and performance numbers from different systems, we built an internal platform that does the extraction and formats the output. Work that used to require several people now requires a fraction of that. The underlying data is the same. What changed is how long it takes to get from raw numbers to something an owner can use.
Marketing a self-storage facility is not like marketing a consumer product. You are trying to reach a specific person in a specific geography who has a specific need, often right now. Generic AI-generated content, targeted at a general audience, is not the right tool for that. If anything, the self-storage industry has a dual marketing challenge that most sectors do not: You are selling to owners and to consumers at the same time, and each requires a different voice and a different approach. That is a judgment problem, not a volume problem, and AI does not solve judgment problems.
There is also a whole cottage industry around something called AEO, which is pitched as the AI equivalent of search engine optimization. The idea is that you can make your facility more visible in AI-generated responses the same way SEO makes you visible in search results. This is largely not how it works. AI language models are built on the same underlying web content that search engines index. There is no separate lever to pull. Any vendor selling AEO as a distinct service is, with very few exceptions, selling you SEO with a new label on it.
An algorithm that is optimizing purely for revenue extraction will raise rates on good long-term tenants at intervals that feel arbitrary and sometimes are. California has already passed legislation limiting how aggressively operators can raise rates on existing customers, and other states are watching. The operators running black-box pricing systems that nobody inside the company can fully explain are going to have a harder time adapting to that regulatory environment than operators who have kept a human in the loop.
The better use of AI in rate management is as an auditor rather than an autopilot. It can flag when a rate increase might cost you a tenant who has been reliable for two years. It can surface patterns in the data that a human reviewer might miss. But the decision about what to do with that information should stay with a person who is accountable for the relationship with that customer.
What specific decision does this tool improve? How do you measure whether that improvement is happening? Where does it fit into our existing workflow, and what does it change for the people using it? If a vendor cannot answer those questions clearly, that is important information. Features and automation and AI buzzwords are not what you are paying for. Outcomes are what you are paying for, and any tool that cannot tell you what outcome it produces probably does not produce one.
A secondary question worth asking is how much effort it takes to get the tool working. If onboarding takes longer than the time the tool will save you in the first year, the math does not work. A lot of AI products in the market right now are technically impressive and practically burdensome. You want the opposite.
When that capability matures, an operator will be able to ask a question like what is driving the performance gap at this facility compared to last quarter and get an answer that is grounded in actual property data rather than a generic response. That is when the reporting and decision-making applications get genuinely powerful. We are not fully there yet, but it is close enough to be worth understanding now.
In the meantime, the operators who will get the most out of AI are the ones who treat it as infrastructure rather than magic. Use it to handle the mechanical work. Keep humans accountable for the judgment calls. Ask hard questions of vendors and ignore anyone who tells you the tool will run itself. It won’t. But it will make the people running your operation meaningfully better at their jobs when it’s used well, and that is worth quite a lot.
here are currently more U.S. self-storage facilities than Starbucks, McDonald’s, and Subway locations combined (more than 51,000 facilities according to the Self Storage Association). That means serious competition for operators.
Add to this a low housing inventory that has homeowners staying put, and you have strong potential for a move-in slump.
In today’s business and financial climate, tenant retention needs extra attention. Fortunately, your current tenants represent tremendous revenue opportunity.
But before you consider how to keep tenants on property, think about why they might vacate and address those issues. That may be half the battle won.
“Most of the move-outs I see aren’t about price, they’re about friction,” says Melissa Huff, COO and co-owner of Lighthouse Storage Solutions. “The customer got a surprise fee, nobody answered the phone when they had a problem, or the property looks like nobody’s touched it in weeks.”
Also remember: Some tenants will leave no matter how buttoned up your business is.
“The goal is not to prevent every move-out,” says Jared J. Mastroianni, COO of modSTORAGE. “People finish a move, sell a home, settle an estate, or simply stop needing storage. A good retention program separates natural departures from avoidable ones.”
So, focus on what you can control: See what other operators are doing, figure out what you can do better, and make changes.
“You all sell storage,” says Sarah Beth DeFazio, Universal Storage Group’s vice president of sales and development. “You are the differentiator. Be the professional in your market. Know your property inside and out. Know your competitors inside and out. You can’t answer a comparison you’ve never done.”
How do you get to know your competitors that well? Stop by with a pizza at lunchtime one day and chat. You’ll soon know just about everything of value about them.
To start, answer the phone. Be there for tenants and prospects. And whether they’re on the phone or in the office, really listen to what they’re saying.
“Delivering excellent customer service alongside high standards at the store level makes it significantly easier for customers to choose to stay for one more month,” says Guy Middlebrooks, executive vice president of operations for CubeSmart Self Storage. “Friendly, service-oriented, and responsive store and sales center teams truly set you apart.”
Huff notes that customer service is about people, not features or amenities. “Automation has changed this business for the better but hasn’t replaced the manager,” she says. “Tenants want a personal experience [especially] when things go sideways. That’s the moment a good manager earns another 12 months of rent.”
For new tenants, an exceptional service experience includes some hand-holding that makes them feel valued and validates their choice:
- Showing them to their unit,
- Staying with them as they inspect it,
- Explaining how the gate and smart locks work, and
- Pointing out security cameras.
For long-time tenants it means providing a consistent quality of service and offering someone who’s ready to leave some options. Could they manage in a smaller unit? Focus on addressing the specific needs you’re not meeting.
Superior customer service works best in combination with other retention-boosting practices.
“The rental conversation is the whole ballgame,” says Huff. “Three extra minutes at the counter prevents a year of arguments that make people leave.”
Eventual rate increases are a fact of life for every business, so how do you handle that sensitive topic down the line?
“Everybody understands that expenses go up,” Huff says. “What people don’t like is being blindsided.”
Notify every tenant of an increase in writing with the required notice. Maintain a consistent increase interval, when possible. If you delay increases and then hit tenants with a large hike, even with notice, you’re going to see many move-outs.
“Most operators read those reviews defensively instead of reading them as data,” says Huff. “Learn from the data and make improvements.”
Mastroianni adds, “Track why tenants leave, not just how many leave. The manager should also mark whether the cause was reasonably preventable.”
Review the information monthly by facility and tenant tenure. Assign an owner, set a correction date, and check whether the pattern continues. This needn’t be a complicated dashboard, but a simple checklist of problems you can actually fix.
DeFazio recommends not waiting until move-out day for surveys. “Do an entry survey and ask why they chose you,” she says. “Do an exit survey and ask what changed. Most operators guess about their differentiators. Your customers will tell you if you ask.”
“Meeting customer expectations regarding technology, such as Bluetooth-enabled access, a user-friendly online rental and payment system, is essential in today’s environment,” says Middlebrooks.
Cameras, door alarms, and smart locks are expected features that will help you seal the deal. They make tenants feel secure. The most sophisticated technology isn’t always what keeps them around longer, though. A feature as common as autopay is a top retention tool.
“A tenant on autopay doesn’t drift into delinquency, doesn’t get overlocked, doesn’t get embarrassed, doesn’t get to the lien stage and just walk away,” states Huff. “Push autopay adoption hard. It’s the cheapest retention tool in the business.”
A pleasant environment also encourages tenants to stay. Everyone likes a clean, bright, and well-maintained facility.
“That means the office, the hallways, the restrooms, the grounds, the units themselves,” Huff says. “Burned-out bulbs and an overflowing dumpster tell your tenant you’ve stopped caring, and once they believe that they start shopping.”
Occasionally walk around your property just to see what needs fixing or cleaning up. Then, have a friend—a fresh set of eyes that won’t easily overlook any issues—do the same thing, and compare notes.
“Financial incentives like account credits or free rent usually do not effectively encourage longer stays,” says Middlebrooks.
If there’s a service or condition problem, a discount isn’t the solution, according to Huff. “If people are leaving because the property is dirty or the manager is short with them, a rate concession buys you a month and solves nothing,” she says. “Fix the actual problem.”
There are exceptions, though.
“A discount can be useful when it’s targeted, time-limited, and tied to a defined situation, such as a short-term hardship or a unit-size mismatch,” notes Mastroianni.
- A free lock,
- Free moving supplies at move-in (or move-out),
- One free month at a milestone, and
- A handwritten thank-you note.
“We pay $100 cash to anyone who sends us someone who rents,” says DeFazio. “That’s a better use of $100 than shaving $12 off a rate for somebody who was going to stay anyway.”



portfolio can look manageable on a map and still be unmanageable on a Tuesday morning.
That is the blind spot in many discussions about self-storage management style. The decision is often framed around facility count: One manager can cover three sites, five sites, perhaps more if the technology stack is strong. But doors do not create the daily operating burden, exceptions do. A gate that will not close, an access complaint tied to the wrong tenant record, a promised callback without an owner, and a delinquency workflow that stopped midway all compete for the same limited resource: verified managerial attention.
The better question is not, “How many facilities can one person manage?” but rather, “How much unresolved work can the operating model safely absorb before important signals lose ownership?”
An oversight load test helps answer that question. It is a practical method for selecting among on-site, hybrid, and remote management based on the character of the work, not a universal staffing ratio. The method does not predict injuries, losses, or financial performance. It makes the conditions that consume attention visible before an operator expands a manager’s span of responsibility.
Both have five facilities. Only one may be suitable for centralized remote management.
Technology can reduce repetitive work, but it can also move work out of sight. An automated notice may send successfully while the account remains unresolved. A work order may show “complete” while the physical condition has not been independently read back. A dashboard may display 10 normal sites and one red exception, yet the red exception may require three phone calls, a local dispatch, a customer update, and a second inspection.
That is why the unit of management capacity should be the open operational obligation. An obligation remains open until the required action, evidence, and communication are complete, not merely until a task changes status.
This emphasis is consistent with established control principles. The U.S. Government Accountability Office’s 2025 Green Book treats internal control as a management process for effective operations, reliable reporting, and compliance. OSHA’s recommended safety practices call for defined responsibilities, proactive hazard control, and evaluation of whether controls remain effective. Ready.gov places communications, recovery, and continuity planning inside business preparedness. NIST’s Cybersecurity Framework 2.0 separates governance, detection, response, and recovery rather than treating an alert as the end of the work. None of those sources sets a staffing ratio for self-storage. Together, they support a useful operating premise: responsibility, observation, action, and verification should remain connected.
- Open exceptions by consequence – Count unresolved safety, security, access, customer, maintenance, payment, and data-quality exceptions. Separate routine issues from those that could cause harm, lock out a customer, or leave a facility unable to operate normally.
- Time sensitivity – Identify which facts or conditions become less reliable with age. A gate photo from yesterday, a unit-status readback from last week, and a current customer access problem should not share the same clock.
- Verification effort – Record what is required to prove the result: system receipt, camera review, local inspection, customer confirmation, vendor documentation, or a second-person check.
- Commitment load – List promises that the operation has made to customers, vendors, and employees, including the owner and due time. An unanswered promise is operational work, even when no alarm is flashing.
- Recovery dependency – Note whether closure depends on local labor, a vendor, another platform, a credential holder, or a physical part. A remote manager cannot directly complete work that requires hands on site.
- Interrupt density – Measure how often the manager must abandon planned work to handle new events. A manageable queue can become unsafe when interruptions prevent deliberate follow-through.
The card should be reviewed at a defined cadence and whenever the portfolio changes materially. A new acquisition, access-system conversion, staffing loss, severe-weather event, or vendor outage can alter the load without changing the facility count.
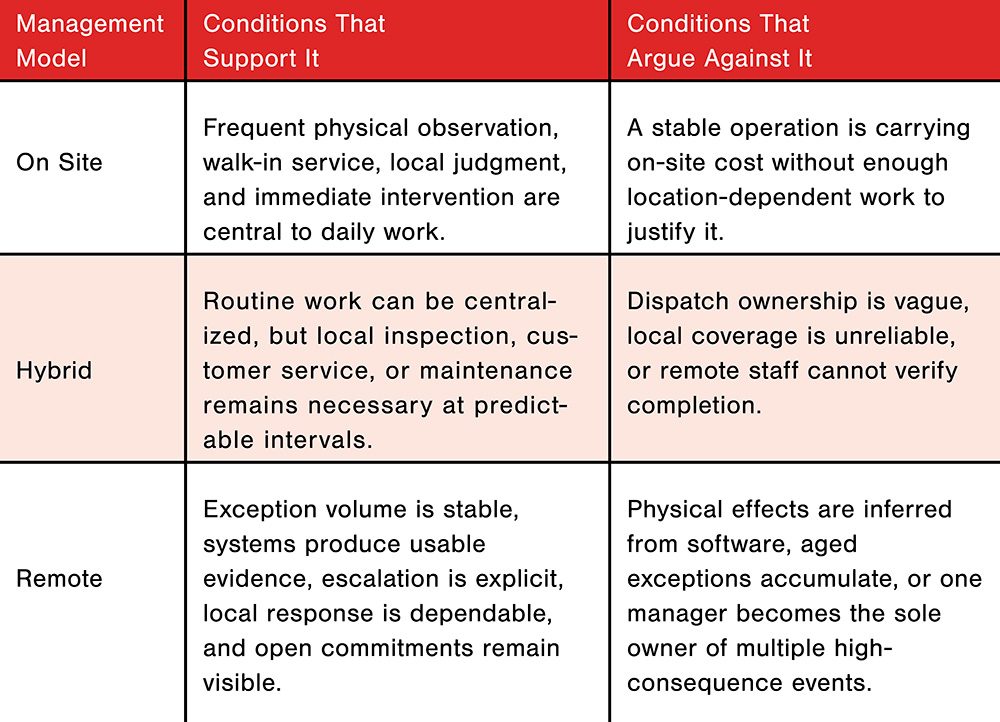
The test can also reveal that the current model is correct but the span is too broad. In that case, the answer may be to reduce the number of obligations carried by one manager, not to replace the model.
The raw count is 18. The oversight load card tells a different story.
The gate failure is high-consequence, time-sensitive, and dependent on local inspection. The access complaint requires a current account readback and customer confirmation. The refund is not technically complex, but it is a live commitment with a deadline. The maintenance tickets are controllable if vendor appointments and follow-up evidence are visible. The document corrections are routine unless they begin to age.
The immediate issue is not that eight sites are too many. It is that three different types of work require near-term attention and two require evidence the remote manager cannot create alone. If local inspection is dependable and the gate event has a named incident owner, the remote model may remain appropriate. If the manager must personally locate a vendor, reconstruct the transfer, and remember the refund while new interruptions arrive, the model has exceeded its safe oversight capacity for that period.
The responsible response is temporary and specific: assign local verification, place the customer commitments on a visible clock, defer noncritical planned work, and review whether the portfolio needs hybrid coverage until the load returns to normal. The operator should not turn this fictional example into an industry threshold. Its value is in showing why a small number of consequential obligations can matter more than a large number of routine tasks.
- No high-consequence exception may remain without a named owner and next action;
- A physical or access change is not closed until the required readback exists;
- Customer promises must have an owner, due time, and completion record;
- Local response dependencies must have a tested primary and backup route;
- One manager should not remain the sole coordinator for simultaneous high-consequence incidents; and
- Recurring aged work should trigger a capacity or process review, not repeated deadline extensions.
Those red lines are internal management choices. They should reflect the operator’s actual policies, legal obligations, insurance requirements, and risk tolerance. The important point is to establish them before a busy week tests the system.
The strongest model is therefore not the one with the fewest people or the most software. It is the one that keeps consequential work visible and owned while preserving enough capacity for the next interruption.
Counting facilities is easy. Governing obligations is harder—and far more useful. Before expanding a manager’s portfolio, run the oversight load test. If the organization cannot name the open obligations, their owners, their clocks, and the evidence required to close them, the next facility is not the only risk. The current management model is already asking attention to cover what the operating system cannot yet prove.


30+ years in self storage • Nationwide service • No outsourcing or junior analysts
 1-866-279-5673
 info@bmsgrp.com
wenty years ago, a successful self-storage entrepreneur facing his own battle with cancer had a vision. What if the industry he helped build could become a powerful force in the fight against a disease that touches nearly every family?
That entrepreneur was Barry Hoeven, founder of Westport Properties and US Storage Centers. Diagnosed with kidney cancer, he understood firsthand the urgency of advancing research, developing better treatments, and giving patients more options. Hoeven also understood the power of business relationships and the remarkable generosity of the self-storage industry.
In 2007, Hoeven founded Kure It Cancer Research with a clear mission: Fund innovative research for underfunded cancers and help promising scientific ideas move forward.
What began as one man’s determination to make a difference has grown into a national cancer research funding organization supported by business leaders, storage operators, industry associations, and corporate partners.
As Kure It prepares to celebrate its 20th anniversary in January 2027, we have an incredible story to share, and the self-storage industry helped write it.
Behind those numbers are researchers who could pursue ideas that might otherwise have sat on a shelf waiting for funding.
Kure It occupies a unique space in cancer research philanthropy. We focus on high-risk, high-reward projects, particularly early-stage research that has scientific promise but may not yet qualify for traditional government or institutional funding.
We call it seed funding.
Think about what it takes to launch a new business. Before there is a proven product, substantial investment, or measurable revenue, someone must believe in the idea and provide the resources to get started.
Cancer research works much the same way.
A scientist may have a compelling hypothesis, but without initial funding to gather evidence, test an approach, or demonstrate early results, that idea may never advance. Kure It helps bridge that critical gap.
Our goal is to move quickly, invest strategically, and give researchers the opportunity to generate the early evidence that will attract larger grants and additional investment.
It is a funding model that aligns remarkably well with the entrepreneurial mindset of the self-storage industry.
At City of Hope Orange County, Kure It committed $550,000 to research focused on improving early detection and screening for stomach and pancreatic cancers. These are diseases where earlier diagnosis can make an enormous difference, yet effective screening options remain limited.
Our national investments also include a $250,000 grant supporting Dr. Dizman’s research at Dana-Farber Cancer Institute, made in honor of NeSSA leader, Charlie Fritz, and a $200,000 grant supporting Dr. Eng’s work at Vanderbilt-Ingram Cancer Center.
Kure It has also invested $1 million in an endowed chair in genitourinary oncology at the University of California, Irvine, establishing a lasting commitment to research and scientific leadership.
Most recently, our 2026 fundraising efforts have highlighted pediatric leukemia research at City of Hope, including the work of Dr. Adam de Smith, whose research explores the earliest origins of childhood leukemia.
Each project is different, but they share a common need: resources to advance research that could ultimately lead to better prevention, earlier detection, and more effective treatments.
That vision helped inspire Round Up For Research, a program that allows participating storage customers to contribute through small, recurring donations.
Individually, these contributions may seem modest. Collectively, they have become extraordinary.
To date, Round Up For Research has raised $7 million for Kure It Cancer Research.
That is millions of dollars generated through everyday business operations, supported by facility managers, team members, storage customers, and companies that believe in making a difference.
US Storage Centers and Westport Properties have been instrumental in building this program and demonstrating what is possible when philanthropy becomes part of a company’s culture.
And the generosity extends well beyond one organization.
Partners like Charity Storage, Late 2 Lien, Storage Solution, Cubby, and Absolute Storage Management are among the companies helping expand Kure It’s reach. Industry associations, including the California Self Storage Association (CSSA), Northeast Self Storage Association (NESSA), Arizona Self-Storage Association (AZSA), and Tennessee Self Storage Association (TNSSA), have also helped strengthen relationships and introduce our mission to new audiences.
This is an industry built by entrepreneurs, innovators, and people who understand the value of relationships. Competitors come together, share ideas, support one another, and frequently rally around causes larger than their individual businesses.
Hoeven recognized that spirit nearly 20 years ago. Today, we continue to see it in action.
This year, we introduced “Building for the Future,” a strategic partnership initiative designed to expand Kure It’s funding capacity, strengthen relationships across industries, and build a larger, more sustainable network of supporters.
At the center of this campaign is our “Community Blueprint,” a visual representation of the businesses, foundations, research institutions, and community leaders helping shape the future of cancer research.
The concept is simple: Important things are built with vision, planning, resources, and people willing to invest in the outcome.
The Blueprint recognizes those partners while inviting others to take their place in what we are building together.
We know the impact that storage operators can make through Round Up For Research. Now imagine expanding participation among management companies, software and CRM providers, developers, construction companies, vendors, and industry associations.
And imagine pairing that growth with new corporate partnerships, family foundations, and philanthropic leaders from outside the storage industry.
This is not about replacing the partners who helped build Kure It. It is about honoring their commitment by inviting others to join them.
Today, Kure It directs approximately $1 million a year toward cancer research. As we look toward our next chapter, I keep coming back to one question: What if we could grow that to $3 million, or even $4 million?
That would mean more projects funded, more innovative ideas tested, and more scientists working on underfunded cancers getting the seed funding they need. It is an ambitious goal, but we are not starting from scratch. We have nearly 20 years of experience, a proven funding model, exceptional research partners, and an industry that has already shown it is willing to lead.
Nearly 20 years later, we have the answer: more than $11 million invested, 77 research projects, 142 scientific publications, and $6.8 million raised through Round Up For Research—one small donation at a time.
Hoeven was right about this industry.
To our longtime storage partners, we thank you. You built this.
To everyone else, consider this your invitation. Whether you operate one facility or hundreds, build them, finance them, or write the software that runs them, there is a place for you in what comes next.
Going from $1 million a year to $4 million will not happen by accident. It will happen because companies decide to be part of it.
Every breakthrough in cancer research starts as an idea someone was willing to fund. The next one could start with you.
Let’s build the next 20 years together.
nyone who’s been alive long enough knows that life is full of twists and turns. Some are better than others. If you’re lucky, a few are extraordinary. Claire Shamsid-Deen’s journey has had unexpected shifts that fit into the latter category. Today, she’s one of the owners and the CEO of third-party management company A-American Storage Management Co., Inc. (A-American Self Storage). How she made it to that position is so impressive it will make you firmly believe that what’s meant for you will most definitely find you.
Those first few years, she lived in a rough neighborhood, yet it was the setting that taught her the wonders of focusing on achieving success. “My dad started his own business out of our garage,” says Shamsid-Deen. “He didn’t go to college, but he was good at sales and became very successful as an entrepreneur with MK Battery.”
When her father’s business took off, the family moved to San Juan Capistrano, an affluent coastal town in Orange County. She attended the high-end preparatory high school Santa Margarita Catholic High, a place where excellence is habitual. “I lettered in track and field and soccer,” Shamsid-Deen says. “Being an athlete was my identity, and my youth club team was one of the best in the country.”
And that’s not hyperbole. They regularly went to national championships and many of them got college scholarships. “I got a full ride to Pepperdine,” she says proudly. “I had multiple offers to go to other schools, but I didn’t want to leave the beach.”
After graduating college, she wanted to work in the entertainment industry. “I worked in small movies, wearing so many hats—art departments, on-set production assistant, stuff like that. I also needed a job that I could take the bus to, because I didn’t have a car.”
She eventually got a job answering phones at a talent agency, where her knack for working her way up shined through: Only two months into her job, she was moved to the commercials department, where she started signing and booking kids on the side. “I became a talent agent overnight,” says Shamsid-Deen. “They didn’t have a youth department, so I started one. Once they started getting calls from casting directors asking for me, they realized it was a good idea.”
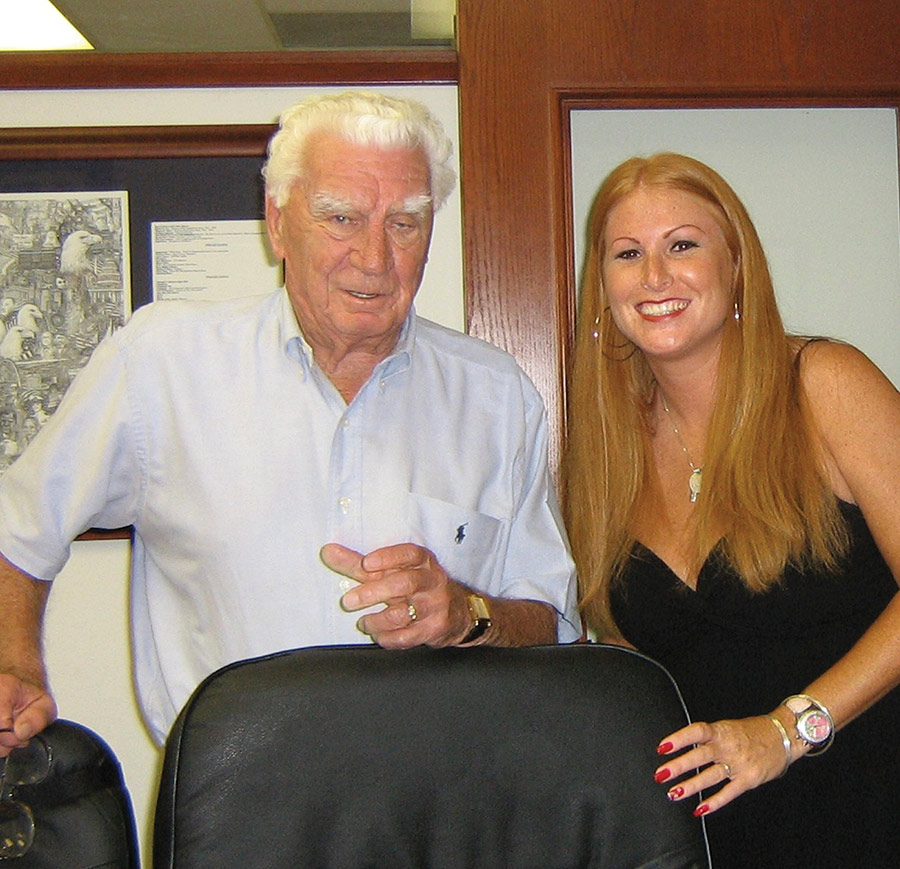
Around that same time, she was dating a guy whose mother worked at A-American Self Storage. “She told me to start working with her while I got on my feet.” The move would be one of the most serendipitous decisions of her life.
Craig Olson, the then-president of the company, eventually asked her to work with him. “I learned a lot about the industry from him,” she says, adding that he and his father, Ed Olson, became huge career mentors.
She taught herself to do the role as she went along, not letting the fact that it was her first job at an office intimidate her. “I was always very confident, even in those early days. People would ask me, ‘What do you mean you’ll just go into Ed’s office?’ And I just did. If I had a question to ask or anything to say, I’d just go in and ask him. I think that’s part of the respect he had for me,” says Shamsid-Deen. “The key is to prove that you’re just as important to be respected as anyone else. I’m sure that my confidence with Mr. Olson made our relationship work well. I learned a lot from both Olsons about myself, about self-storage, and about business in general.”
She remained with the company throughout the entire ordeal, helping manage what was left. Despite the country’s financial hardships, a lot of the self-storage owners A-American did third-party management for held out. “They didn’t want to sell,” says Shamsid-Deen. “We’ve held on to those assets as clients for many years, even after Craig Olson had left and all the VPs were gone.”
Ed Olson hired another company to manage the clients that were left. After about a year, she asked him to give her, Josh Paterson, and Madelline Quijano a chance to rebuild the company. “He let us do it,” she says.
Slowly but surely, they started bringing in more deals for investors. “We grew and bought more properties. The three of us were running things, even though we weren’t the owners back then. We’d talk to Ed in Hawaii and get his approval for big purchases.”
At some point, Shamsid-Deen visited him in Hawaii. Even though he was in his early 90s, he continued working; during that trip, she drove him to his meetings. “He said he wished he had known earlier he had such a strong team. He was really proud of us.”
It wasn’t just something he said during a heartwarming moment. He actually included Shamsid-Deen, Paterson, and Quijano into his estate planning. When he passed away, the trio who had rebuilt A-American Self Storage became the owners.
“It’s been two years. The first one was really tough. There’s a large amount of assets where Ed was majority owner of, so we’re dealing with trustees,” she says. “We answer to a lot of owners, just like a lot of third-party management companies, but so far, so good. We just signed a new third-party management deal that puts us at 29 properties—slowly growing again.”
From temp worker to owner, it’s an impressive trajectory no matter how you look at it—one that surpasses all the expectations for great achievements from her youth. “I’ve been with the company for about 21 years now,” she says. “I started in late 2004/early 2005. And while we’ve been through a lot, it’s because of those challenges that I know I can get through anything.”
Her years of experience let her look at her story with the benefit of hindsight. “It’s been a privilege and an interesting journey,” she adds. “I remember vividly, in the early years, sitting in a meeting with about 10 male district managers and one of them telling me in front of all the other guys that I would never make it in this business because I didn’t know enough about self-storage.”
They love spending time at the beach and watching sports together. “We’re Arsenal fans. We also love the Lakers, and we’re UCLA fans. Those are the non-negotiable sports teams to follow,” she notes with amusement. “If they try to be USC fans, I will kick them out of the family.”
More control over healthcare costs.
Access to virtual doctors, counseling, prescriptions, and everyday health support.
- $0 virtual doctor visits
- $0 licensed counselors
- 5,000+ prescriptions included
- No insurance, co-pays, or deductibles
- Support for everyday health needs
Powerful tools to protect you and keep you connected with the people who matter most.
- Emergency Alert Button
- Live GPS Location Sharing
- Trip Monitoring & Safety Alerts
- Automatic Place & Geofence Notifications
- Real-time updates, check-ins, and alerts
- Hangouts, Trips, Places, Zones, and more
Your employees invest in your business every day. Invest in them.
safer, more
connected
team

supplier with three unique business
solutions to serve a wide variety of needs
- Full product line, including
doors and hallway systems - Complete storage building packages
- Multi-story premium installation
eciding your path forward can take time. Scott Levy knows this all too well. At Penn State, he couldn’t figure out what he wanted to do, changing majors seven times. But as a self-proclaimed “numbers geek,” something involving finance seemed to make sense—more so than learning to speak Russian.
“I took a few Russian classes, yeah,” Levy says through laughter. “But that didn’t get me excited. When I got into economics, money, banking, and statistics, that’s what really lit my fire. I think my mind has always gone to a methodical problem-solving approach.”
Despite this, Levy says he’s had to force himself out of that process from time to time throughout his career. “You can’t have a completely linear focus. It’s hard to collaborate well if that’s your mindset.”
Levy prefers to be in a room with people who don’t necessarily think the same way as him. “That’s how you grow and innovate,” he says. “You put all these different viewpoints together into the ‘wonkinator’ and come up with a better answer.”
His recruiting pitch wasn’t exactly overflowing with assurances. “He basically said, ‘This is probably going to work, but it might not,’” Levy recalls. “‘As long as your eyes are wide open on this one, I’d love to have you come on board.’”
Levy took the chance and stayed for 15 years.
When the company emerged from the downturn with capital and an opportunity to grow, Levy made his move into investments. He spent roughly a decade working alongside Jonathan Perry, whom Levy considers both a friend and mentor. Together, they grew the company’s numbers. Levy estimates that he completed approximately $5.5 billion in self-storage transactions over his career, roughly 90 percent of it during his years at CubeSmart.
Still, after a decade and a half, Levy decided it was time to see what else he could learn. “Leaving Cube was bittersweet, but I was ready to see what else was out there.”
During his first nine months, Simply acquired approximately $475 million in properties, increasing the portfolio by about 25 percent. Levy then worked with the Simply team to refine processes and improve the operation itself with much success. But in 2023, Blackstone sold Simply Self Storage to Public Storage. Suddenly, Levy was once again figuring out what he wanted to do next.
Those conversations ultimately led Levy to join Highline as chief investment officer in 2023. In 2025, he added the title of president. Now Levy oversees investments, marketing, revenue management, and operations, with additional involvement in accounting and human resources through the company’s shared-services structure.
Highline currently operates 63 properties, up from 56 when Levy joined. But adding stores wasn’t his immediate priority. Same-store occupancy was approximately 76 percent when he arrived. For the better part of his first two years, Levy focused on improving the performance of what Highline already owned. He was joined by two former Simply colleagues, CMO Craig Olinger and COO Scott Sebring, and the trio set about strengthening operations across the portfolio.
According to Levy, self-storage remains an intensely local business, and population continues to grow in some areas, creating opportunities for new supply. The problem, he says, is piling new supply into markets that haven’t absorbed what was already built. “If three properties have been delivered in 10 miles and someone’s trying to add a fourth, that market just needs time to digest all of that and reset what normal is before trying to add more.”
Levy remains bullish on self-storage. While industry revenue and NOI may not be producing the extraordinary gains seen coming out of the pandemic, he says they’re also not collapsing. Highline, especially, has performed particularly well. Its strategy was to avoid cutting rates more than necessary while rebuilding occupancy, allowing the company to begin pushing rates again once the portfolio reached a comfortable occupancy level.
Looking ahead, he remains optimistic. “New supply is slowing while existing supply continues to be absorbed. Even if demand remains relatively flat while supply growth declines, pricing power should eventually improve. If demand begins growing at the same time, the effect becomes even stronger.”
Levy puts the brakes on just a bit, saying developers shouldn’t expect a sudden return to the post-COVID years. “I don’t think it’s a switch that someone’s going to flip and all of a sudden we’re back to normal. Normal is a setting on the washing machine. It’s harder to predict in the real world.”
What he does expect is a gradual return toward more historical industry fundamentals. The underlying need for storage, after all, hasn’t disappeared. “We are fortunately a nation that has a lot of stuff,” he says. “We like our things and need a place to store them.”
Levy’s optimism doesn’t mean he believes self-storage is easy money, especially as operations become more sophisticated and competitive. “For a long period of time, self-storage, because we performed so well, especially post-COVID, was viewed as a bit of a get-rich-quick scheme,” he says. “Self-storage investment is not a get-rich-quick scheme. It takes a lot of time, patience, and it’s a much more operationally intensive business than people realize.”
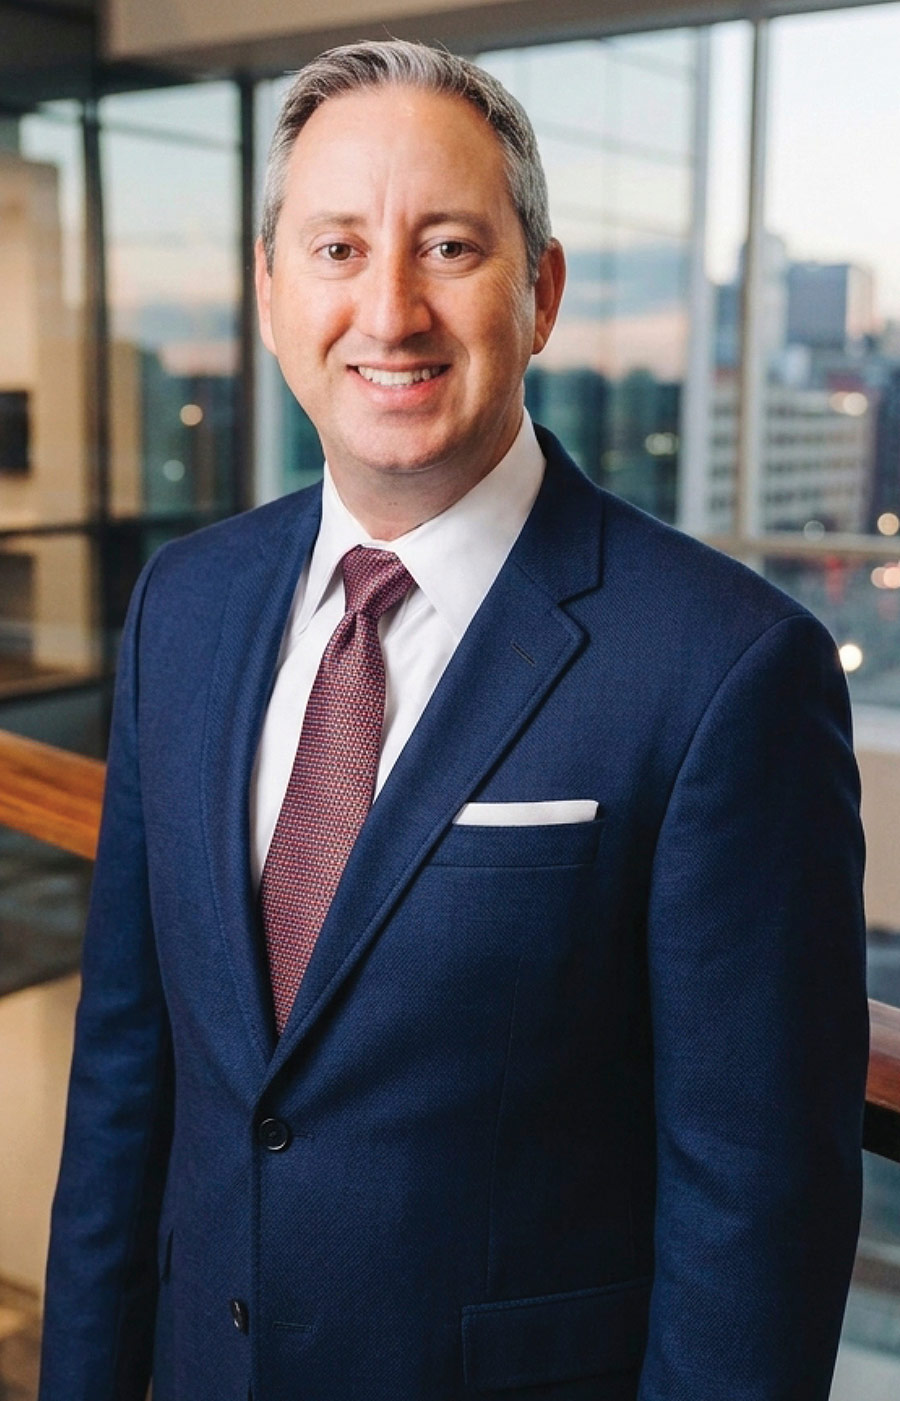
If self-storage hadn’t come calling, Scott Levy might be in a very different position. “I’d probably be a Secret Service agent,” he says with a straight face. The U.S. Secret Service offered him a job in its white-collar crime division, focused on money laundering, shortly after college. He turned it down because he had already accepted his first position in real estate. “I thought it would be disingenuous to back out of that,” he says.
Levy admits the Secret Service would have been a pretty cool career path, but he has no regrets about the decision. “Had I taken that position, I probably wouldn’t have my wife and my three kids that I have now. I wouldn’t have a lot of the friends that I have in the industry. As intriguing as that would’ve been, I wouldn’t change anything.”
Levy has been married to his wife, Christy, for 13 years, and they have three children: Mason, Carter, and Isabel. The family lives in the Philadelphia suburbs, where Levy spends his free time hunting, fishing, and attempting to improve his golf game. “I stink at it,” he says with a laugh. “I’m better at catching fish than making par.”
Data Storage Stats
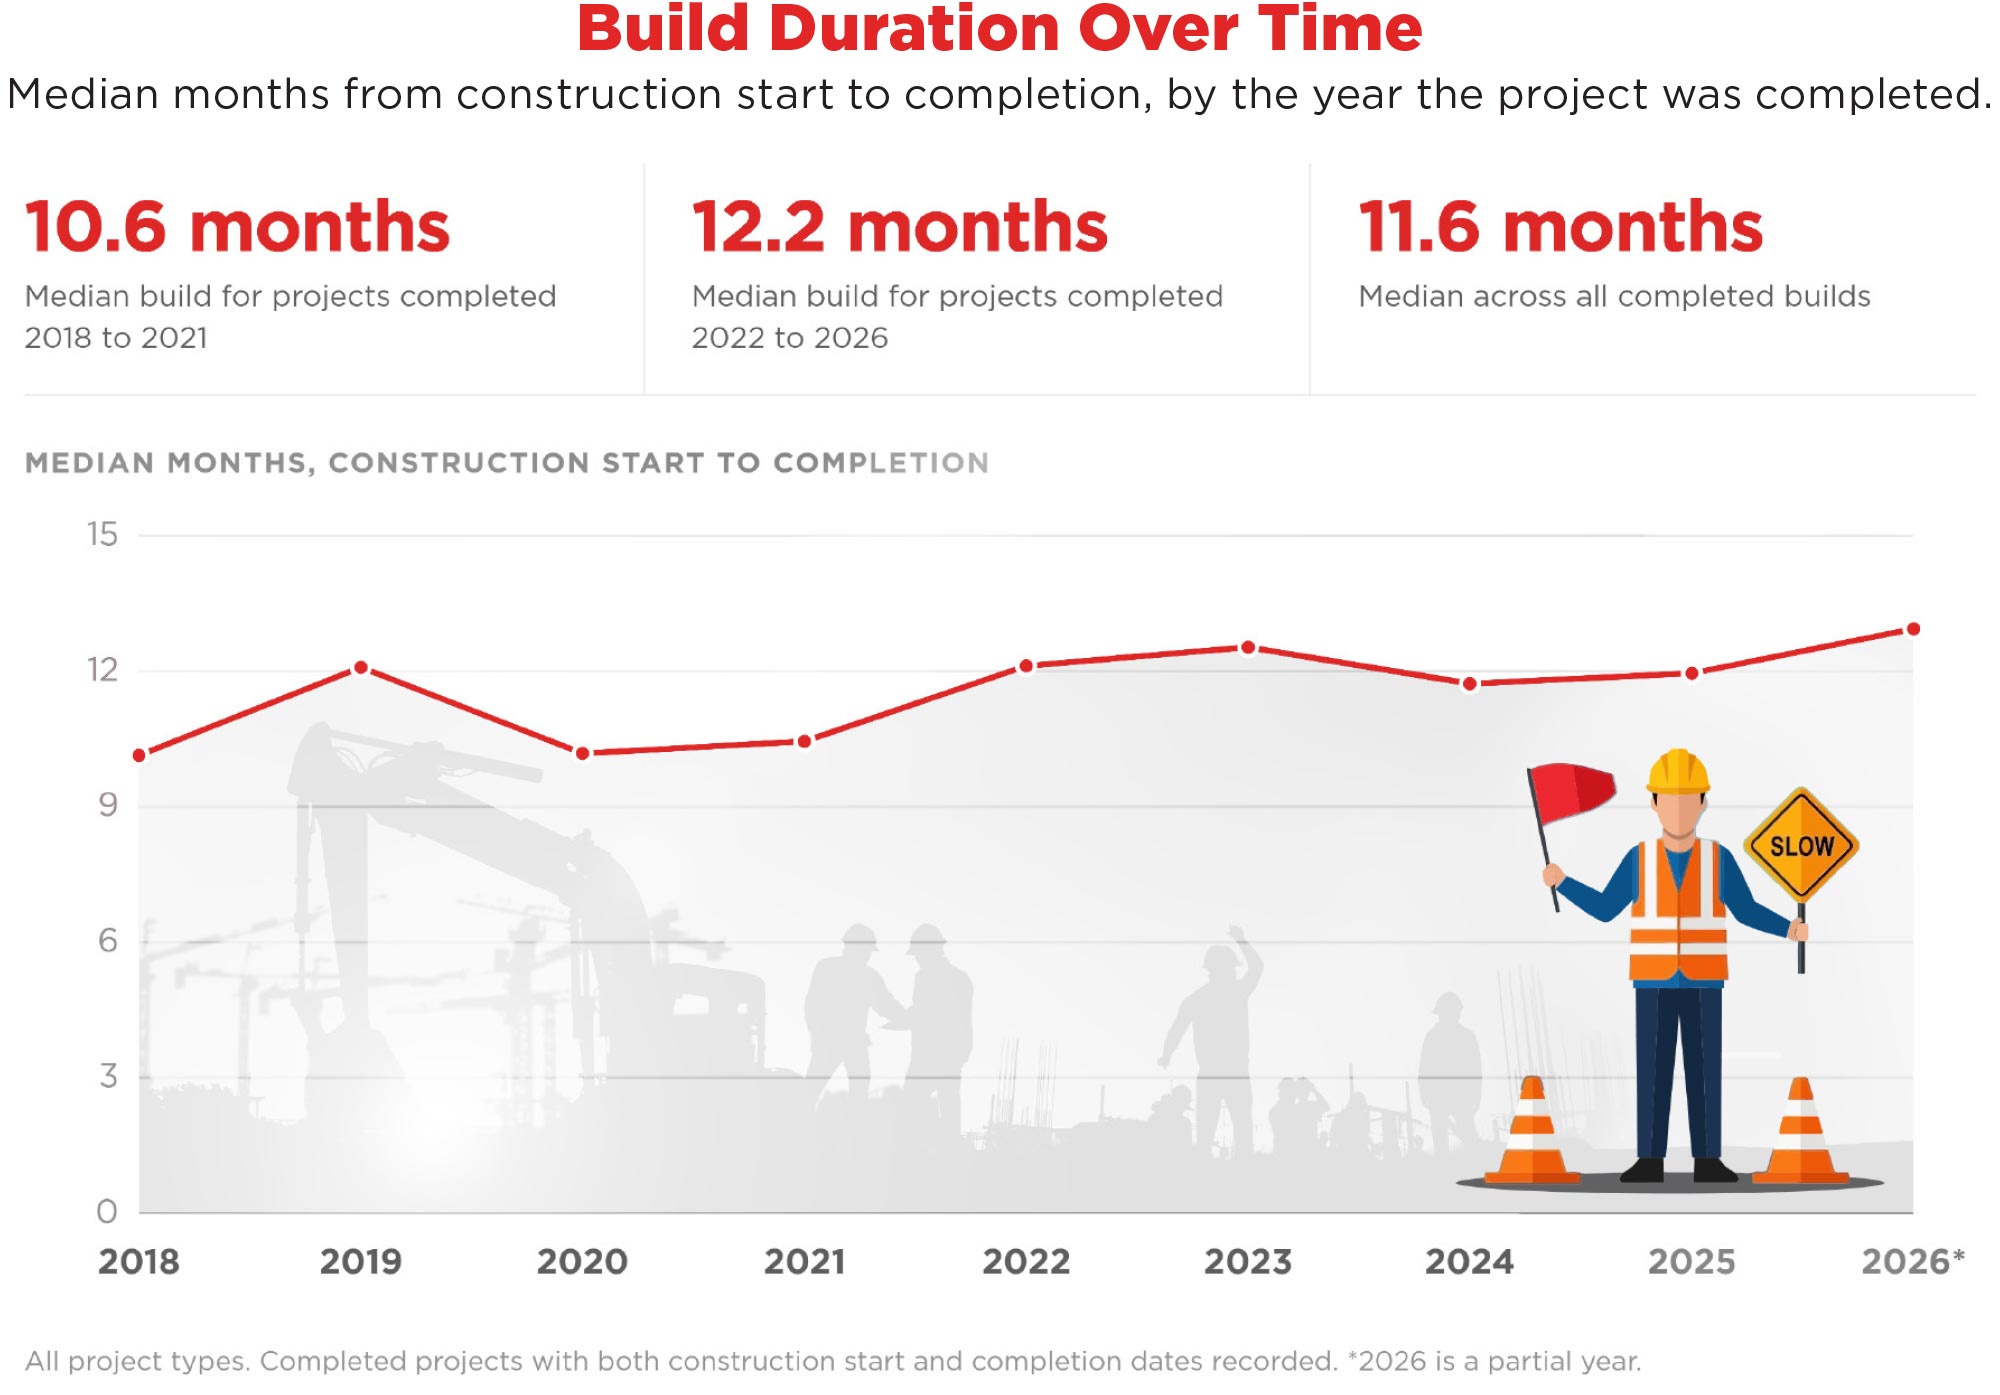
lower supply meets a long road to recovery. A Yardi Matrix team attended the Self Storage Association National Fall Conference Sept. 8 to 11 in Las Vegas and presented Self Storage Odyssey 2026: Navigating an Evolving Market. Slides are available upon request. Like Odysseus’ journey home, the sector’s recovery has been long and marked by obstacles, many stemming from its record-setting pandemic performance. Demand from domestic migration and home sales remains in a three-year slump, while renewed inflation poses another threat to normalization. Attendees confirmed that fundamentals weakened in August and early September. Near-term improvement will depend largely on declining new supply, but record oversupply in many markets could prolong recovery for years. Nationally, supply delivered from 2023 through 2025 nearly matched the previous peak from 2018 through 2020, without the COVID-era demand surge that accelerated lease-ups. Although occupancy appears to have stabilized, revenue growth remains pressured by the historically wide gap between in-place and street rates. Contributions from existing customer rate increases should also diminish as move-in and move-out activity normalizes. Despite these challenges, the sector remains favored by large investors, while transaction activity and pricing have continued their gradual recovery in 2026.
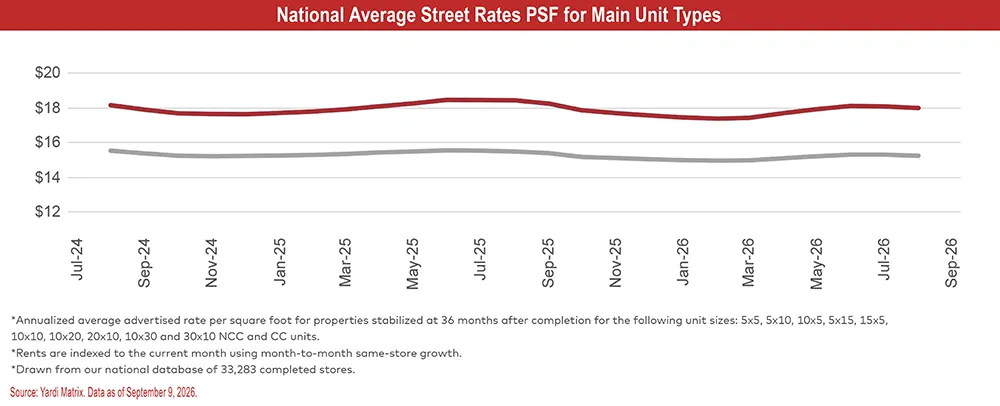
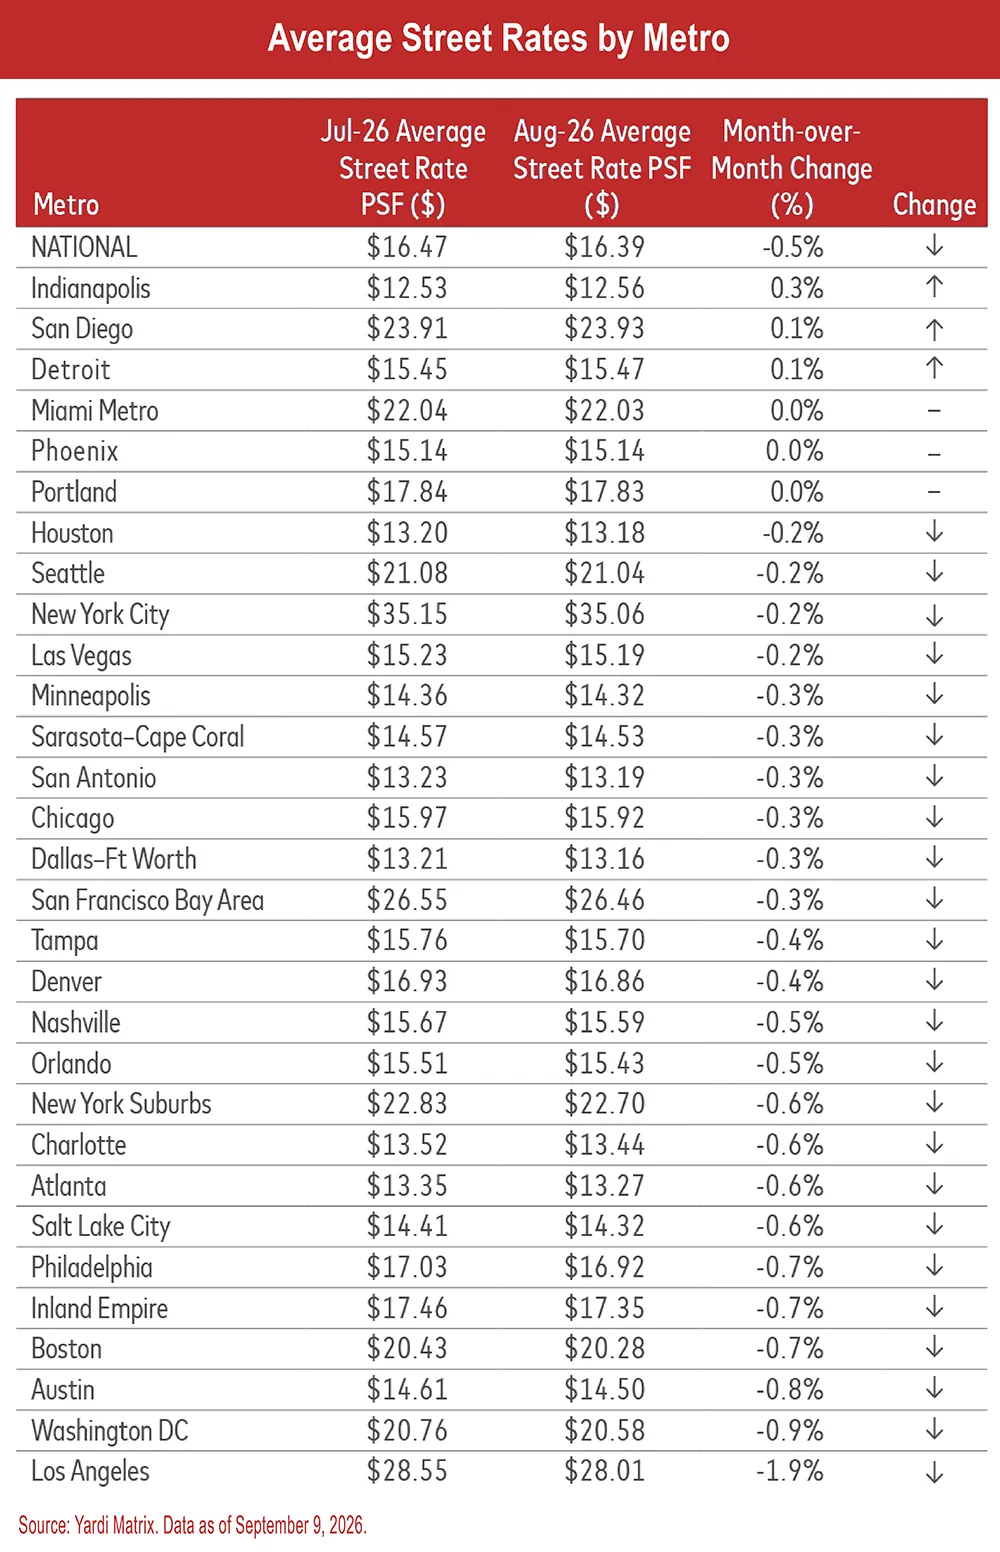
Advertised rate declines widen despite slowing supply. Advertised rate performance weakened in August as soft demand and lingering lease-up supply pressures outweighed the benefits of a slowing national development pipeline. Nationally, advertised rates declined 1.9 percent year over year in August, compared with declines of 1.6 percent in July and 1.5 percent in June. The national average rate dropped to $16.39 per square foot.
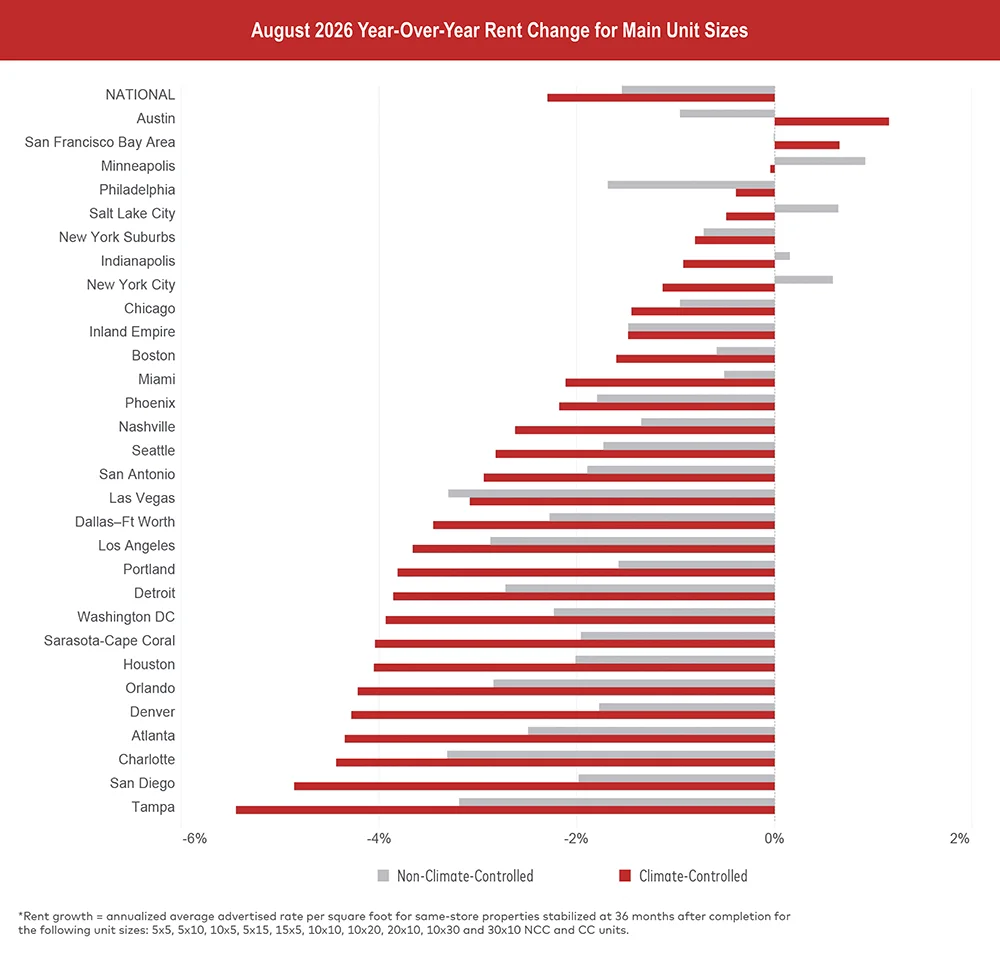
Most of Yardi Matrix’s top 30 metros recorded larger year-over-year advertised rate declines in August than in July 2026 or August 2025, pointing to broad-based weakness. Only four top metros experienced an annual increase in advertised rates for non-climate-controlled (NCC) units, while Austin and San Francisco were the only two markets where rates for climate-controlled (CC) units increased.
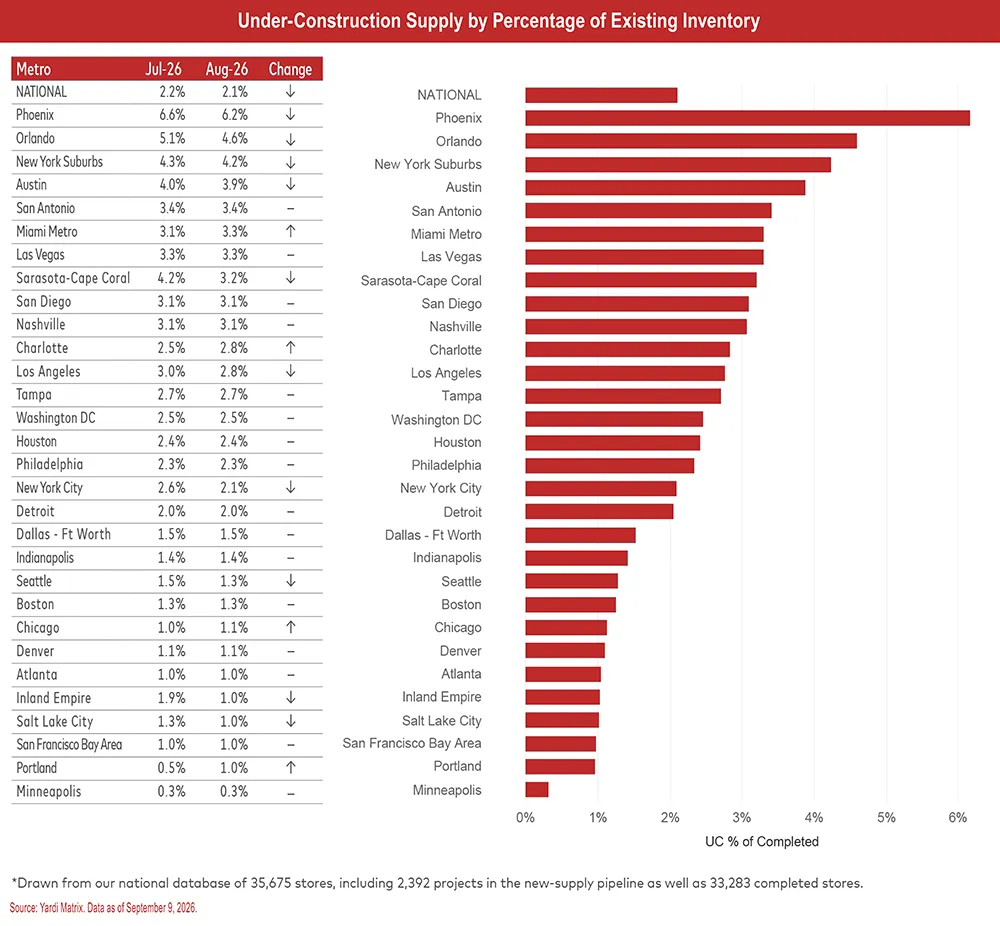
Nationally, Yardi Matrix tracks a total of 2,392 self-storage properties in various stages of development, including 594 under construction, 1,499 planned, and 299 prospective properties. Under-construction projects represented 2.1 percent of existing stock by NRSF at the end of August, down 10 basis points month over month. Yardi Matrix also maintains operational profiles for 33,283 completed self-storage facilities in the U.S., bringing the total dataset to 35,675.
REIT advertised rates declined 3.1 percent year over year and 0.9 percent month over month in August, compared with declines of 1.2 percent and 0.3 percent, respectively, among non-REIT competitors. The sharper REIT declines reflect their more responsive pricing strategies amid weaker seasonal demand.
See August 2026 Year-Over-Year Rent Change for Main Unit Sizes chart.
Month-over-month declines were widespread in August, with 24 of the top 30 metros posting decreases in advertised rates.
See National Average Street Rates PSF for Main Unit Types chart and Average Street Rates by Metro table.
San Francisco has the strongest demand backdrop of the four, combining limited lease-up supply with the highest population and multifamily rent growth among the top 30 metros. Minneapolis and Salt Lake City also benefit from comparatively modest lease-up supply and improving demand fundamentals. Slowing development is supporting rents in Minneapolis, while Salt Lake City’s positive performance contrasts with continued declines across several higher-supply Mountain West markets.
See Self-Storage Major Metro Summary chart.
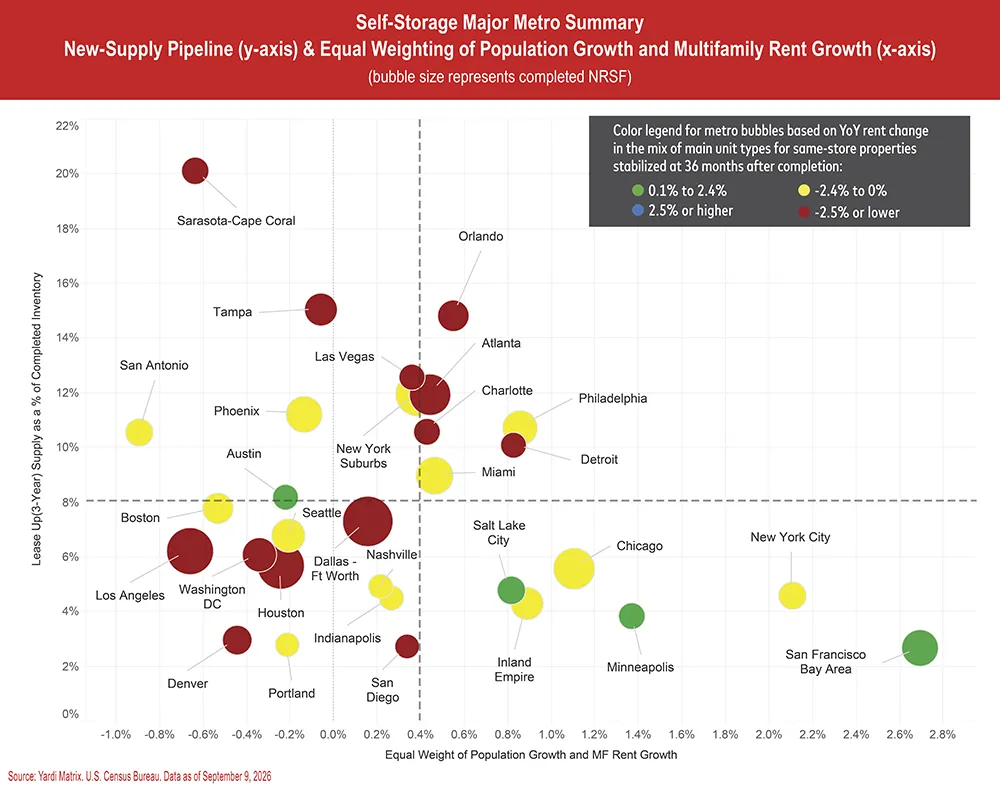
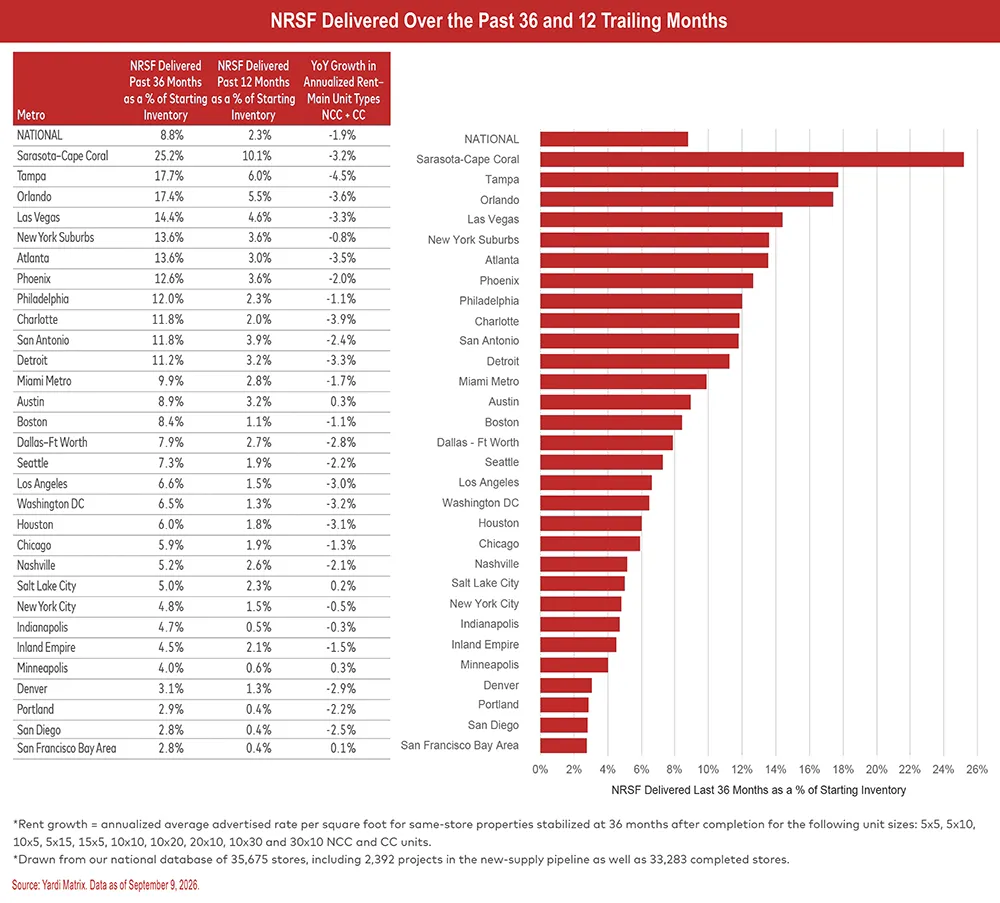
COVID-era growth markets continue to weigh disproportionately on national performance as operators work through elevated lease-up supply. Sarasota–Cape Coral remains the most heavily supplied top-30 metro, as total inventory has grown by one-quarter in just three years, while Tampa and Orlando also remain near historically high lease-up supply levels. Although deliveries are slowing, these Sun Belt markets will need time to absorb existing lease-up inventory, and their large storage footprints amplify their impact on national trends.
See NRSF Delivered Over the Past 36 and 12 Trailing Months table and chart.
San Diego’s under-construction supply was unchanged in August but has more than doubled from 1.4 percent of stock a year ago, while planned supply has risen to 6.1 percent of inventory. After benefiting from limited recent deliveries, the metro could face renewed supply pressure as its expanding pipeline begins to deliver.
See Under-Construction Supply by Percentage of Existing Inventory table and chart.

Whatever you’re imagining, let’s build it.
StorageCafe survey of more than 1,400 Americans found that lack of space—not moving—is now the leading reason people rent a unit. More than one in three respondents said clutter at home regularly overwhelms them. About one in four Americans currently uses self-storage, while another one in four is actively searching for a unit online.
Demand is strongest among people living in mid-size homes: 37 percent use self-storage, compared with 22 percent of those in smaller homes. Four in five renters visit their unit at least monthly, suggesting that storage units function as an extension of the home rather than simply a place to keep forgotten belongings.
Gen X leads all generations in current use at 35 percent, while Gen Z has the lowest rate (13 percent) but the highest future intent: Nearly one in three non-users plan to rent a unit. Hybrid workers also lead all work arrangements in current use at 34 percent, as their homes serve simultaneously as offices, living spaces, and storage areas. Meanwhile, self-storage searches across the 150 largest U.S. cities rose 23 percent year over year in 2025, nearly triple the 8 percent growth recorded in 2024.
In this housing context, a household may need another bedroom, a dedicated office, more room for children, or somewhere to put years of accumulated belongings. Moving could solve the problem, but higher home prices, mortgage rates, and transaction costs make an upgrade difficult.
A storage unit offers a pointed solution: While it does not add living space, it can relieve pressure inside the home without forcing the household into an unaffordable property.
The issue is not even confined to smaller places. In fact, the survey shows that 37 percent of people living in mid-size homes use self-storage, compared with 22 percent of those living in smaller homes. Therefore, more space does not eliminate storage demand; it may even make households more open to buying new belongings, supporting additional family members, or taking on new responsibilities.
Plus, homeowners are already more likely than renters to use self-storage, at 29 percent compared with 21 percent. They also have stronger future intent. Thirty-six percent of homeowners plan to use self-storage, compared with 15 percent of renters.
The two groups face different pressures. Renters are more likely to focus on the immediate cost of a unit. Homeowners are more likely to be managing long-term accumulation and the limits of a property they cannot, or do not want to, replace.
Four in five current users visit their units at least once a month, while 28 percent visit weekly. These customers are using their units as parts of their day-to-day lives, rather than a place you leave and forget your belongings for months on end.
Four-person households are the most frequent visitors, with 52 percent making weekly trips. Renters visit more often than homeowners, too. The survey found that 36 percent of renters visit weekly, compared with 25 percent of homeowners.
The stored items help explain these frequent visits: seasonal belongings, clothing, furniture, sporting equipment, and household overflow rotate between the home and the facility as needs change throughout the year. To operators, this means that customers who visit once a year have different expectations from those who use a facility as an additional room. Access, location, security, hours, and ease of entry become more important when storage is part of ordinary household life.
Remote and hybrid work have continued to intensify the pressure on residential space, too. Hybrid workers have the highest current self-storage use among work arrangements at 34 percent. Their homes may need to serve as offices, living areas, and storage spaces at the same time.
See Storage Use by Work Setup chart.
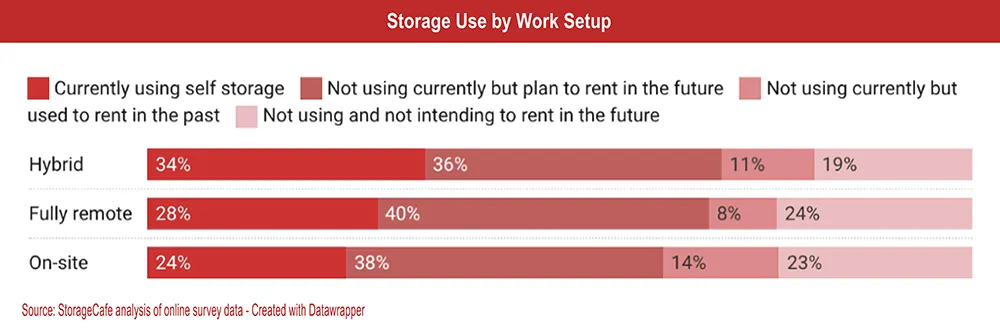
Therefore, while hybrid workers have already crossed into active use, fully remote workers may represent a future source of demand as permanent home offices continue to compete with household space.
This demographic data hints at the space pressures facing households that support children, adult children, and aging parents, since more people under one roof means more belongings competing for the same closets, rooms, garages, and spare corners.
See Self-Storage Across Generations (Present) chart.
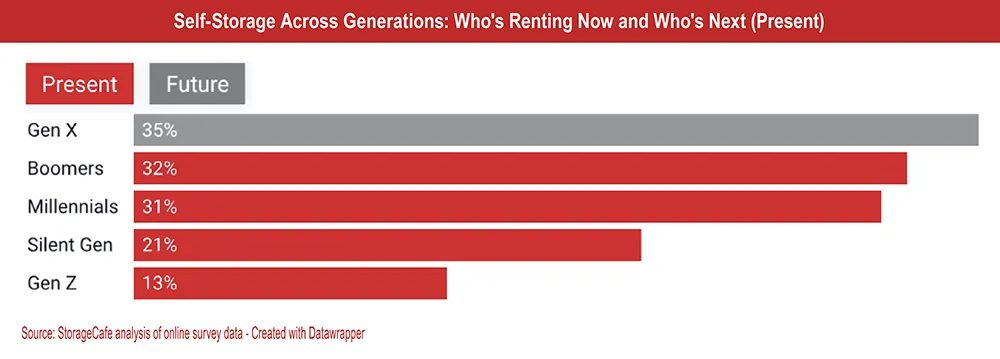
The demand is consistent with households managing belongings across multiple generations: One home may contain children’s furniture, aging parents’ possessions, seasonal equipment, and the accumulated contents of a household that has not yet reached a stable configuration.
See Self-Storage Across Generations (Future) chart.
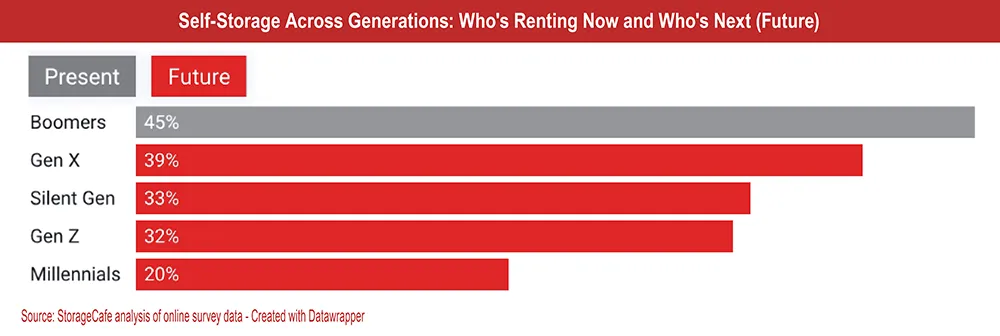
Gen Z is also the most space-starved and clutter-overwhelmed generation. Its future intent is more than double its current use, which suggests that storage is already part of how many younger adults think about housing, even before they become customers.
For this younger group, homeownership competes with rent, student debt, and everyday expenses. Many young adults are building full lives in smaller apartments while waiting for a more affordable opportunity to buy. A storage unit can help manage the interim: It can hold belongings between moves, support a smaller apartment, or accommodate items that do not fit in a first home.
Clothing ranks second, at 15 percent, and is especially prominent among residents of studios and one-bedroom residences, where 21 percent identify clothing as a stored category, compared with 7 percent of residents in four-bedroom homes. For smaller households, the unit can function as an overflow wardrobe.
See What Americans Demand From Their Storage Facility chart.
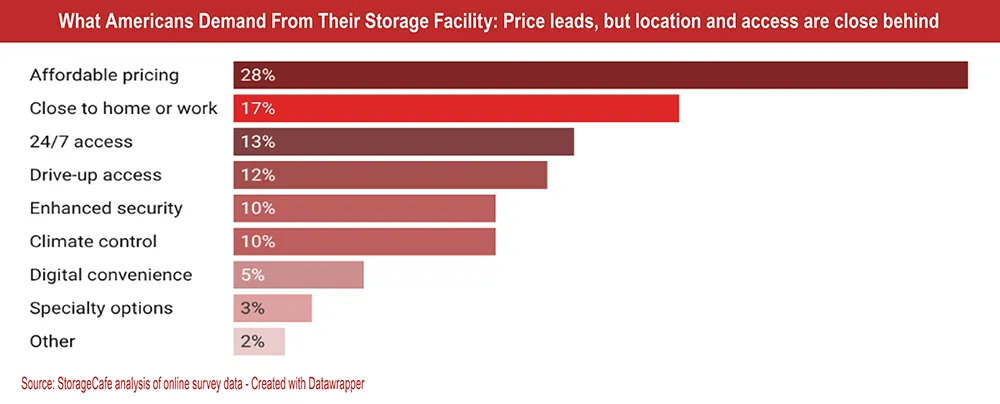
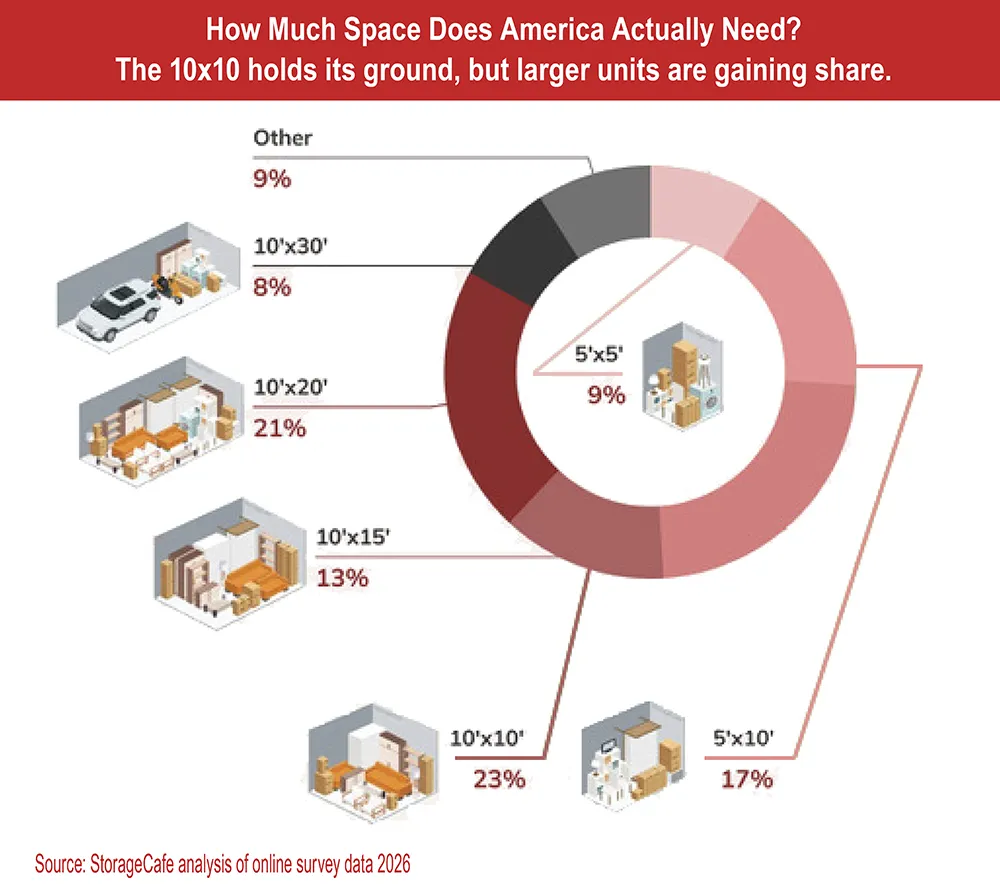
Homeowners are using storage to remain in homes that no longer provide enough room. Renters are using it to manage smaller apartments and frequent moves. Gen X is storing belongings associated with multigenerational households, while Gen Z is preparing for a housing market in which additional space may remain difficult to afford.
Hybrid work is increasing pressure inside the home. Clutter is making the shortage more visible. Rising search activity shows that consumers are actively looking for solutions.
The broader shift is clear. Self-storage is becoming part of how Americans make existing housing work.
As moving becomes more expensive and homes become less spacious, the storage unit is no longer only a temporary holding place. For a growing share of households, it is the additional room they cannot afford to build or buy.
Against that backdrop, TBS Companies is taking a different approach to what a construction and manufacturing partner can be.
With a corporate rebranding earlier this year, TBS Companies (formerly known as Trachte Building Systems) is a 125-year-old, 100 percent employee-owned parent organization bringing together four specialized businesses (Trachte, Trac-Rite, MakoRabco, and Fire Facilities) under one platform. Each company maintains its own expertise and market identity, while the larger organization creates opportunities to connect capabilities, resources, and experience.
or self-storage developers, owners, and operators, that means access to a broader range of expertise without sacrificing the specialized knowledge that made each business successful in the first place.
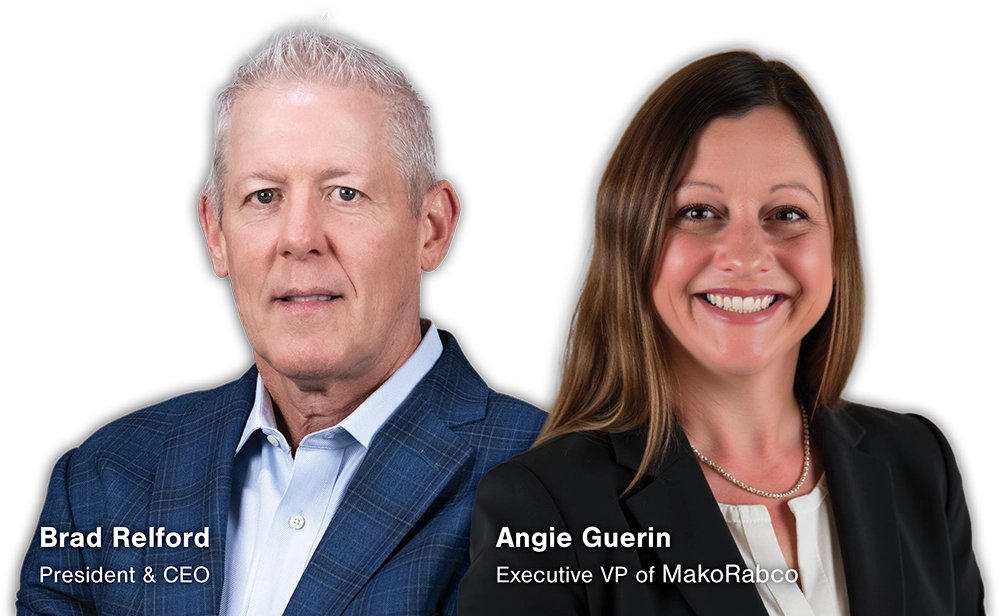
“Our philosophy is captured in the TBS tagline, ‘Together Building Stronger,’ which is more of a guiding principle than an acronym,” noted Brad Relford, president and CEO. “Our platform of brands allows us to provide meaningful solutions that help new and existing customers develop successful self-storage businesses.”
Four Companies, One Broader Resource
TBS Companies’ force as an industry leader comes from preserving the unique strengths of its three self-storage businesses while making those capabilities more accessible to customers through a united parent brand.
Trachte designs, manufactures, and constructs pre-engineered steel self-storage systems. Its roots in self-storage reach back to the 1970s, but the company’s manufacturing heritage traces to 1901.
Founded as a roll-up door manufacturer in 1981, Trac-Rite brings expertise in attractive, low-maintenance door and door corridor systems that serve a variety of verticals and complement the broader building capabilities available through TBS.
MakoRabco adds full-service design-build construction and structural engineering expertise, with particular experience in complex self-storage developments, including multistory projects where tight sites, architectural requirements, and coordination can add significant layers of complexity.
Fire Facilities extends the platform beyond self-storage, providing specialized training structures and equipment for fire and public safety professionals.
Together, the businesses create a platform capable of supporting a wide range of construction and manufacturing needs while allowing each brand to remain focused on the customers and markets it knows best.
For a developer, that distinction can make a significant difference. Not every project needs every TBS company, but the value is having the right expertise available when the project calls for it.
Experience That Starts Before The Jobsite
A successful storage project involves far more than selecting a building or a door. Site utilization, design, engineering, materials, manufacturing, installation, and long-term maintenance all influence how a facility ultimately performs.
TBS Companies brings those considerations together through teams with extensive experience in both manufacturing and construction.
That experience can become especially valuable early in the development process. Developers evaluating a parcel may benefit from construction expertise before plans are finalized, while owners or contractors with completed permit drawings may need a partner focused on execution. TBS is structured to engage at either point or virtually anywhere in between.
Early involvement can help uncover opportunities and potential complications before they become costly changes in the field. Experienced teams can examine how a design will translate from drawings into manufacturing and actual jobsite conditions, bringing real-world considerations into decisions. Over time, TBS can also provide repair and replace solutions to maintain the safety, curb-appeal, and rental rates for aging buildings.
That makes TBS more than a supplier of individual components. It positions the organization as a resource that can help customers think through the broader project, which is becoming increasingly important for storage developers and owners.
Built For A More Creative Development Landscape
The next several years are expected to bring continued innovation in how self-storage facilities are developed and constructed. Constrained land and changing project economics are encouraging developers to maximize available sites, incorporate different types of storage solutions on a site, and explore conversions and renovations.
TBS Companies is structured for that environment.
Its combination of building systems, doors, design-build construction, structural engineering, and renovation capabilities gives customers options as project requirements change. The addition of MakoRabco has strengthened the organization’s ability to address complex construction, while the company’s focus on flex-space buildings and adjacent pre-engineered building opportunities demonstrates an effort to anticipate emerging needs rather than simply respond to established ones.
“What made TBS feel like the right home for MakoRabco was that they understood what had made us successful—and honored the ways our businesses served the self-storage industry differently. We’ve always been a relationship business. We care deeply about our customers, and when something needs to get done, our people figure out how to get it done.
TBS recognized that culture rather than wanting to change it. We shared the same commitment to people, service, and doing business the right way, while bringing complementary strengths in the projects, expertise, and customers each company was known for.
“For me, that was incredibly important. MakoRabco joined an organization that shares the values we’ve spent years building, with the leadership and vision to bring our collective strengths together and create even more for our customers and the self-storage industry,” shared Angie Guerin, executive vice president of MakoRabco.
That forward-looking mindset extends to manufacturing technology and project support. The next generation of owners and developers is entering an industry where information, efficiency, and rapid decision-making are increasingly important. TBS is combining decades of self-storage experience with continued investment in manufacturing technology to address those expectations.
The objective is the practical combination of innovation and experience, using modern capabilities while retaining the industry knowledge needed to apply them effectively.
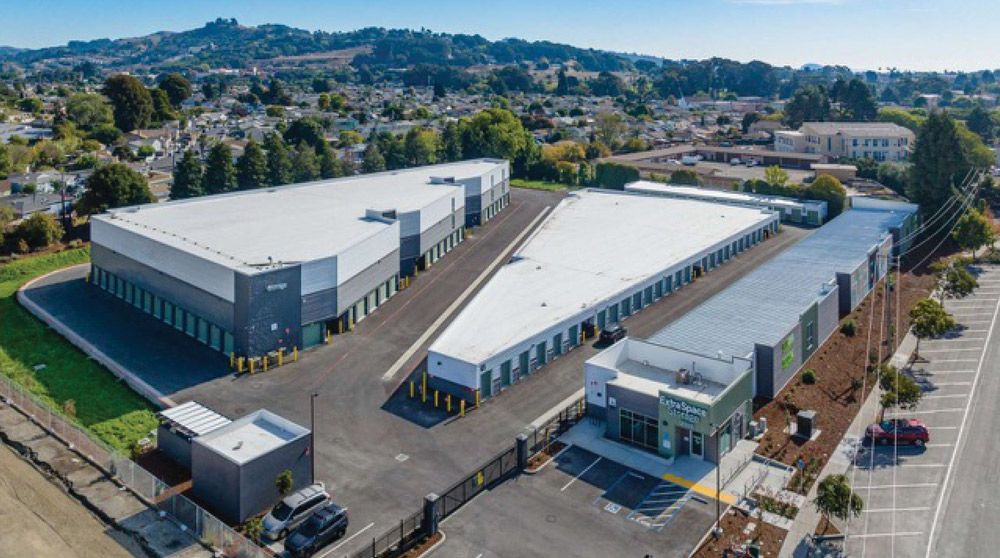
For TBS Companies, the project lifecycle does not necessarily end when a facility opens. As existing facilities age, owners must continually consider repairs, replacements, modernization, and improvements that preserve appearance, functionality, and asset value.
TBS can support those needs through renovation and repair-and-replace work, including projects involving doors, roofing, and other building requirements. This creates an important distinction for owners building portfolios: A relationship with TBS can begin with a new facility and continue through future development, replacement projects, and reinvestment in existing assets. For developers who build, lease-up, and move on to the next opportunity, a partner with a long-term understanding of their business can become an increasingly valuable resource. The same teams that understand how a facility was built can potentially support future projects as an owner’s portfolio expands. In that sense, TBS is built around the full lifecycle of a storage asset rather than a single transaction.
Employee Ownership With A Long-Term Perspective
One of the most distinctive characteristics of TBS Companies is its ownership structure.
The organization is 100 percent employee-owned through an Employee Stock Ownership Plan, giving employees a direct stake in the company’s long-term performance.
That structure is intended to influence more than financial participation. It creates an ownership mindset that connects day-to-day performance with the company’s future and places an emphasis on quality, accountability, and customer relationships.
For an industry built on repeat business and long-term relationships, that philosophy is particularly relevant.
Every project contributes to the reputation of the organization, and every customer relationship has the potential to extend well beyond a single job. Employee ownership provides a direct connection from daily performance to the future they are helping build.
The result is a culture designed around commitment and accountability—qualities that become especially important when projects are complex, schedules are demanding, and multiple areas of expertise must work together.
The Value Of Collective Expertise
The real strength of TBS Companies is not simply the number of products or services available through its four businesses. It is the ability to connect specialized expertise around a customer’s needs.
A developer working on a conventional single-story facility may need a building package and door systems. A contractor tackling a complex multistory development may require design-build and structural engineering capabilities. An owner with an established portfolio may need replacement components or a renovation partner years after a facility was completed. Those are different challenges, but they all fall within the TBS platform of brands.
The organization’s structure also gives customers access to teams that understand the broader project rather than viewing an individual product or service in isolation. When building systems, doors, engineering, and construction overlap, coordination can help identify challenges earlier and create a more connected path from concept to completion.
That breadth is particularly valuable when it translates into practical solutions, service, and expertise rather than simply a larger list of offerings.
Preparing For The Industry Ahead
TBS Companies is being built to serve the self-storage industry of today and tomorrow. Its vision is not simply to become larger. It is to become more valuable to the storage customers it already serves—and to those it has yet to meet—while protecting the relationships, people, and culture that have sustained its businesses for generations.
That balance between scale and specialization, innovation and experience, and new construction and long-term asset support is at the heart of the TBS Companies model.
From a developer evaluating its next site, to a contractor managing a highly complex building, or an owner preparing to reinvest in an aging facility, TBS offers a broader resource built around the realities of today’s storage market.
After 125 years, the company is not merely carrying its history forward. It’s putting that experience to work in a new structure designed to help customers build smarter, adapt faster, and create facilities that last.
TBS Companies has brought four established businesses together with one objective: building stronger together for what comes next.
Phone: 800-356-5824 Email: info@tbscompanies.com Web: tbscompanies.com
f you pay for Google or Meta ads, the report you get back probably leads with cost per lead. That number is close to useless for a storage business, and budgets allocated on it flow to exactly the wrong campaigns more often than most owners realize. The only acquisition number that should drive a decision in this industry is cost per move-in.
I ran facilities for 13 years before I moved to the systems side, and the gap between those two numbers (per lead and per move-in) is where I watched ad spend quietly leak out of otherwise well-run operations, not because anyone was careless but because the report ended one step too early.
Cost per lead measures the first link and stops, so a campaign can look cheap while producing inquiries that never become tenants, such as tire-kickers, people in the wrong part of town, or someone comparing prices for a move that is still three months out. Meanwhile, a different campaign looks expensive on the same report while quietly producing the customers who show up, rent, and stay.
Nobody wakes up wanting self-storage. Something happened in their life that forced the decision. The person who searched “cheap storage near me” and the person who searched your neighborhood by name and looked at your rates before calling are in different places in that decision. The first report treats them as identical. Your bank account does not.
Campaign A targets “cheap storage near me.” Spend is $600; it generates 100 leads, and cost per lead comes out at $6. On the agency dashboard, it is the star.
Campaign B targets “storage units” plus your city or neighborhood, and the landing page shows a price. Spend is $570; it generates 30 leads, and cost per lead is $19. On the same dashboard, it is the campaign someone will suggest cutting.
Now follow both to the rental record. Campaign A’s bargain hunters convert at 4 percent. That is four tenants, mostly in the smallest units. Cost per move-in is $150. Campaign B’s inquiries convert at 20 percent (six tenants). Cost per move-in is $95.
Judged on cost per lead, you move budget from B to A and feel good about it. Judged on cost per move-in, B is producing tenants at roughly two-thirds the cost. And in my experience, the gap widens from there because the customer who searched your location and saw a price before picking up the phone tends to stay longer than the one who searched “cheap.”
It’s the same ad account and same month but opposite decisions. That is what reporting on the wrong number does.
One more thing to notice in the example is that Campaign A’s four tenants took the smallest units; Campaign B’s six did not, so even cost per move-in undersells the gap. The number an owner actually wants is revenue per move-in by campaign. Ask yourself these two questions: What did we pay to acquire this tenant, and what is that tenant worth in rent over the time they stay?
John Reinesch, who owns facilities and runs the self-storage marketing agency StorIQ, says, “Even cost per move-in is only half the equation. The bigger opportunity is lifetime value. There’s a practical floor to how cheaply you can acquire a tenant, but there’s much more room to increase what that tenant is worth. If one operator can profitably acquire a tenant for $500, while a competitor can only afford $250, they can bid more aggressively and capture more demand.”
That is the part most operators never get to, because they are still arguing about cost per lead. Once you have cost per move-in wired up, lifetime value is one more column, and it is the one that decides who wins the auction for the next customer.
That produces an optimization loop pointed at the wrong target. The agency tunes campaigns to make leads cheaper, which usually means more bargain hunters, which pushes the real number the wrong way while the reported number improves. Everyone looks at the chart, the chart looks better every quarter, and the facility is paying more per tenant than it was a year ago.
Fixing that is on the operator, not the agency. Nobody else can connect your spend to your tenants, because nobody else has both halves of the data.
It also distorts the numbers people use to value an operation. Marketing cost per move-in, multiplied by average length of stay and rental rate, is the closest thing this industry has to a true customer acquisition economics figure. If the input is cost per lead instead, every downstream calculation about marketing efficiency inherits the error. An owner comparing two managers, two markets, or two agencies on lead metrics is comparing them on something that does not predict rent.
Tag the source on every inquiry. Where did this person come from—which campaign, which channel? Add Urchin Tracking Module (UTM) parameters on web forms, tracking numbers on phone lines, and channel tags on chat and text. If your inquiries already land in one place, this is a settings exercise. If they are scattered across five inboxes and a voicemail box, fix that first. It is the same plumbing problem in a different jacket.
Carry the tag through to the rental record. When the inquiry becomes a tenant, the source needs to ride along into the property management system or be joined to it later in a report. This is the link almost everyone is missing, and it is the cheapest one to build. Most modern platforms have a field for it. It just sits empty.
Report spend against move-ins by campaign. Once the tag reaches the rental record, the chart your agency already sends becomes a chart worth reading: dollars in, tenants out, campaign by campaign. Add length of stay and you have revenue per campaign, which is the number that actually belongs in an owner’s monthly pack.
The usual objection is that most inquiries come by phone and phone leads cannot be traced. They can be traced. Campaign-level tracking numbers have been available for years, and the cost is trivial next to the ad budget they are measuring. The second objection is that the PMS cannot take the data. However, in almost every case, it can. Someone just has to decide the field matters.
Once it is wired, it runs on its own. Every future ad dollar gets judged against the truth instead of a proxy.
A good agency will tell you they need move-in data from your side and offer to help build the link. Keep them. An agency that responds with a better-looking cost-per-lead chart has told you something useful too.
If the answer is a shrug, you have just found wasted spend without opening a single report. Right now you do not know which half of your budget is working. Neither does anyone else.
t’s crystal clear where the older generations are moving so far in 2026: southern destinations.
It’s a mixed bag for the younger generations, though, with a few prominent out-migration states such as California and New York witnessing a welcome uptick in arrivals from Gen Z.
For its 2026 midyear migration report, U-Haul analyzed one-way transactions based on the generational group of its renters, considering customer moves over a 52-week period from July 2025 through June 2026. The analysis examines both national migration patterns and departing one-way traffic from every U.S. metro with a population of 1 million or more.
U-Haul, the industry leader in DIY moving and home of the 1-Year Storage Price Lock, facilitates millions of one-way transactions annually through accessible, affordable mobility solutions.
The data indicates the renter’s generation, or stage of life, plays a vital role in where their moving truck, trailer, or U-Box® moving container is going.
Sorting by generation groups and based on each state’s net gain or loss of one-way U-Haul equipment from July 2025 through June 2026, the national data shows some clear generational distinctions:
- Baby Boomers are flocking to the Carolinas. Six of the top seven net-gain states for boomers are in the sunny Southeast and the other is Arizona—all hot spots for retirees or winter homes.
- Generation X and millennials are typing Florida and Texas in their GPS more than anywhere else. However, each group’s preferences differ after that. Gen X keeps to the Southeast and Mountain West. Millennials are scattering to California and several Midwest states for their careers.
- Generation Z is gravitating to densely populated markets with numerous colleges, entry-level jobs, and apartment access. Texas and California top their list. New York, Illinois, and Colorado follow, reflecting a diverse blend of geography and politics in their destinations.
The metro-level data reinforces those differences while showing that migration patterns can vary significantly depending on where a mover is starting. Across the major U.S. metros tracked in the report, boomers generally favor destinations in the Southeast, Southwest, and other areas associated with retirement and second-home living. Gen X tends to remain concentrated in the Southeast and Mountain West, while millennials show a broader mix of Sun Belt, Midwest, and Western destinations.
Gen Z stands apart from the older generations. Its leading destinations include some of the nation’s largest and most densely populated metropolitan areas, including New York City, Chicago, Los Angeles, Dallas-Fort Worth, and the San Francisco Bay Area. The metro-level results suggest that younger movers are continuing to gravitate toward markets offering colleges, jobs, and access to apartments and other rental housing.
For example, Atlanta’s departing U-Haul traffic shows South Carolina, North Carolina, and Alabama among the top destinations for boomers, while Texas and Florida lead the Gen X and millennial lists. For Gen Z movers leaving Atlanta, Texas, New York, and California are the leading states.
Similar patterns emerge in other major markets. Boomers leaving Chicago are most likely to head toward Wisconsin, Florida, and Michigan, while Gen X and millennials also show strong ties to the Midwest and Florida. Gen Z movers leaving Chicago, meanwhile, favor New York, California, and New Jersey.
In California, the picture is somewhat different. The report shows that younger generations are not simply abandoning the state. Among Gen Z movers leaving Fresno, for example, Colorado, Arizona, Nevada, Texas, and Oregon are the leading destinations, while the San Francisco Bay Area remains a prominent net-gain metro for younger movers. Millennials leaving Los Angeles show Texas, Oregon, Tennessee, Colorado, and Utah among their leading states.
The findings illustrate why national migration trends can sometimes obscure significant differences between generations and individual metropolitan areas.
The following is a further breakdown of generational relocations on a national scale.
(July 2025 to June 2026)
- South Carolina
- North Carolina
- Florida
- Arizona
- Alabama
- Tennessee
- Arkansas
- Idaho
- Oklahoma
- Georgia
Top U-Haul Net-Gain Metros
(July 2025 to June 2026)
- Gainesville-Ocala, Fla.
- Myrtle Beach, S.C.
- Phoenix, Ariz.
- Charleston, S.C.
- Lake Havasu City-Kingman, Ariz.
- Daphne-Fairhope-Foley, Ala.
- Spokane, Wash.
- Tucson, Ariz.
- Daytona Beach, Fla.
- Wilmington, N.C.
(July 2025 to June 2026)
- Florida
- Texas
- South Carolina
- Tennessee
- Alabama
- Utah
- Idaho
- North Carolina
- Arizona
- Arkansas
Top U-Haul Net-Gain Metros
(July 2025 to June 2026)
- Fort Myers, Fla.
- Charleston, S.C.
- North Port-Sarasota-Bradenton, Fla.
- Miami-Fort Lauderdale-West Palm Beach, Fla.
- Nashville, Tenn.
- Salt Lake City, Utah
- Wilmington, N.C.
- Tampa, Fla.
- San Diego, Calif.
- Gainesville-Ocala, Fla.
(July 2025 to June 2026)
- Florida
- Texas
- California
- Ohio
- Idaho
- Indiana
- Minnesota
- Wisconsin
- Washington
- Virginia
Top U-Haul Net-Gain Metros
(July 2025 to June 2026)
- Dallas-Fort Worth, Texas
- Houston, Texas
- Orlando, Fla.
- San Francisco Bay Area, Calif.
- North Port-Sarasota-Bradenton, Fla.
- Lakeland-Winter Haven, Fla.
- Boise, Idaho
- Palm Bay-Melbourne-Titusville, Fla.
- Brownsville-McAllen, Texas
- Huntsville, Ala.
(July 2025 to June 2026)
- Texas
- California
- New York
- Illinois
- Colorado
- Washington
- New Jersey
- Florida
- Pennsylvania
- Nevada
Top U-Haul Net-Gain Metros
(July 2025 to June 2026)
- New York City, N.Y.
- Dallas-Fort Worth, Texas
- Chicago, Ill.
- San Francisco Bay Area, Calif.
- Los Angeles, Calif.
- Austin, Texas
- Charlotte, N.C.
- Denver, Colo.
- Seattle, Wash.
- Houston, Texas
*Customers must be 18 to rent a U-Haul truck and 16 to rent a U-Haul trailer
Florida is the lone state with a top-10 net gain among all four generations. Texas ranks very high for everyone but boomers, while Idaho makes it on three lists.
The metro-level report further illustrates the strength of Florida and Texas as destinations for multiple generations. Major markets including Dallas-Fort Worth, Houston, Orlando, Miami, Tampa, and Fort Myers appear repeatedly among the leading destinations, although their appeal varies by generation and point of origin.
For older movers, the Carolinas, Florida, Arizona, and other Sun Belt destinations remain particularly prominent. The U-Haul metro data also highlights retirement-oriented destinations such as Myrtle Beach, Gainesville-Ocala, Phoenix, Charleston, and Fort Myers.
Younger generations have a wider geographic footprint. Gen Z’s national list includes Texas, California, New York, Illinois and Colorado, while its metro destinations are dominated by major population centers. New York City ranks No. 1, followed by Dallas-Fort Worth and Chicago, with the San Francisco Bay Area and Los Angeles also making the top 10.
Metro areas like College Station, Gainesville, Lubbock, Lexington, Tallahassee, Manhattan (Kan.), Champaign, Madison, and Baton Rouge show sizeable gains among Gen X contract holders, indicating many parents help their university-bound children move.
The presence of college-oriented markets throughout the metro data provides another indication of the different life stages represented in the migration figures. While retirees may be seeking warmer climates and lower-cost or lifestyle-oriented destinations, younger movers can be influenced by education, employment, and housing opportunities.
U-Haul’s midyear analysis offers a snapshot of those shifting preferences based on actual one-way equipment movements. The full report includes migration trends for major U.S. metros with populations greater than 1 million, allowing the national findings to be viewed through the lens of individual markets. Find the 2025 recap and more U-Haul migration trends reports and rankings at uhaul.com/about/migration.
in Self-Storage Construction
SBS CONSTRUCTION EAST
Roc Hughes!
at The Show in Atlanta, GA
November 4-6
Booth #345



TEXAS • LOUISIANA • KANSAS • MISSOURI • FLORIDA • ALABAMA • MISSISSIPPI • ARKANSAS • OKLAHOMA • GEORGIA • TENNESSEE • NORTH CAROLINA • SOUTH CAROLINA
17 Scenic Loop Rd.,
Boerne, TX 78006
830-388-7620
SBS East Office:
Atlanta, GA
678-409-1831
TEXAS • LOUISIANA • KANSAS • MISSOURI • FLORIDA • ALABAMA • MISSISSIPPI • ARKANSAS • OKLAHOMA • GEORGIA • TENNESSEE • NORTH CAROLINA • SOUTH CAROLINA
17 Scenic Loop Rd.,
Boerne, TX 78006
830-388-7620
SBS East Office:
Atlanta, GA
678-409-1831
n 2002, Ramey Jackson joined Janus International—the same year the company opened its doors. Jackson has spent nearly 25 years helping grow the business alongside a self-storage industry that has changed dramatically over that time. Jackson’s path from forward-thinking sales leader and industry advocate to a national Self Storage Association board member and now CEO of Janus International has been defined by a focus on moving self-storage forward, anticipating what’s next, championing innovation, and staying closely connected to the developers and operators who have helped shape the industry.
Throughout his career, Jackson has witnessed self-storage evolve through shifting development cycles, growing demand for facility redevelopment, and the emergence of smart locks, automation, and AI. And, in many cases, he has played a role in driving that evolution. But for Jackson, the Janus story has never been simply about making doors or developing the next technology. It’s about investing in the industry, listening to customers, and evolving alongside them to meet their needs today while anticipating what comes next.
As the self-storage industry has grown and become more sophisticated, so too have the challenges facing owners, developers, and operators. Projects have become larger and more complex, portfolios have expanded, and owner-operators increasingly need partners capable of delivering consistency and support at scale. Under Jackson’s leadership, Janus has continued to evolve around those needs, expanding beyond products alone to help customers plan, build, modernize, and operate facilities throughout their lifecycle.
The Janus Model 650 door quickly became the most installed roll-up door in self-storage, and it remains so today. Purposefully designing doors for easier and faster installation, better performance over time, and less susceptibility to shipping damage established an early philosophy at Janus: Listen to the industry, solve practical problems, and build better solutions specifically for self-storage.
Building better product was only part of the equation. Janus also recognized that even the best door delivers limited value if a customer cannot get product delivered where they need it, when they need it, and installed quickly and professionally. As the industry expanded, Janus built the infrastructure to grow with it, supporting customers with unit layouts, dedicated project managers, superior manufacturing capability, experienced install crews, and industry-leading warranties.
That approach became an important differentiator. In a market where manufacturers often try to compete primarily on producing the lowest-cost door, Janus has remained focused on the total value of the project. Reducing material or manufacturing costs can create tradeoffs elsewhere, from installation time and durability to service requirements and long-term operating costs.
For Jackson, that broader view of the customer relationship has remained central as Janus has grown. The goal is not simply to sell what a facility needs today but to understand where the industry is heading and build the products, services, technology, and infrastructure customers will need next. It is the same principle that led Janus to rethink the self-storage door more than two decades ago—and one that continues to guide the company as the industry enters its next era.
“Innovation has always started with listening to our customers and understanding the problems they need us to solve,” says Jackson. “That was true when Janus developed its first door, and it’s still how we think about the business today.”
As Janus expanded into a truly global self-storage solutions provider, Jackson remained focused on ensuring that growth strengthened the company’s connection to the industry rather than distancing it from the customers who helped build it.
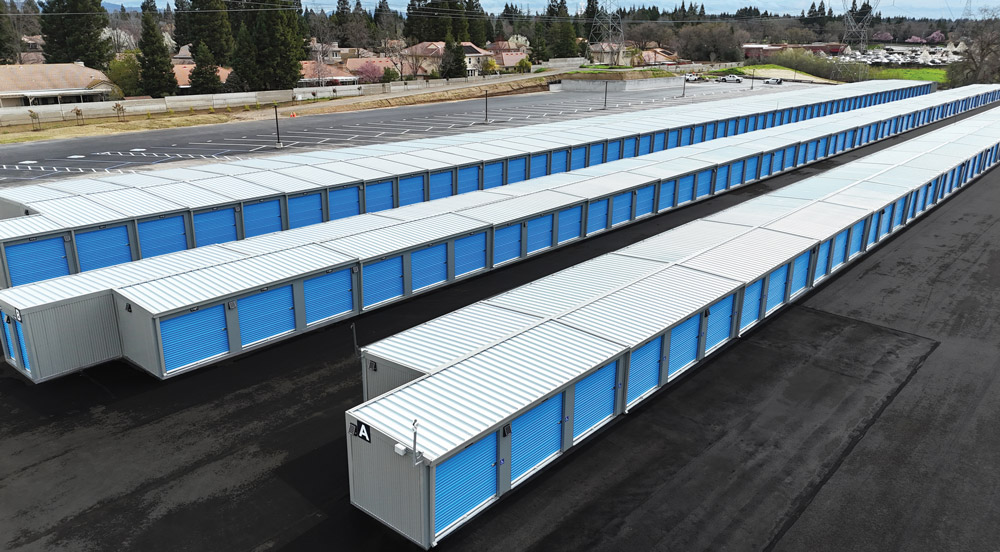
The product portfolio progressed alongside that footprint. What began with a better roll-up door expanded to include swing doors, lockers, complete interior hallway systems and an increasingly broad range of door solutions, including the 750 and 850 wind-rated models and the NS Series, which was designed to make the door secure and more robust against common break-in methods.
“As our customers in Texas and Florida saw a need for wind-rated solutions, we quickly responded with our 750 and 850 door models,” says Jackson. “Similarly, as owner-operators recently began reporting more sophisticated break-in attempts, we built our NS Series for both new construction and retrofits to help protect against those attempts. Our view is simple: Our products need to work.”
Each expansion—geographically and in product development—reflected the same underlying objective: Understand what customers need to build and operate better facilities and develop the products and infrastructure to deliver it at scale.
“We responded to the changing needs by expanding our capabilities around the entire lifecycle of a self-storage facility,” says Jackson. “First with our R3 Program and again with our Nokē Smart Entry platform.”
The development and evolution of the R3 Program (Restore, Rebuild, Replace) created a more comprehensive approach to facility improvement. What began with replacing aging doors grew to encompass hallway reskins, unit remixing, office remodels, building renovations, and MASS relocatable storage. Rather than approaching each improvement as an isolated project, R3 gave operators a way to rethink underperforming properties more holistically, improving appearance and functionality while creating opportunities to add rentable space and generate additional revenue.
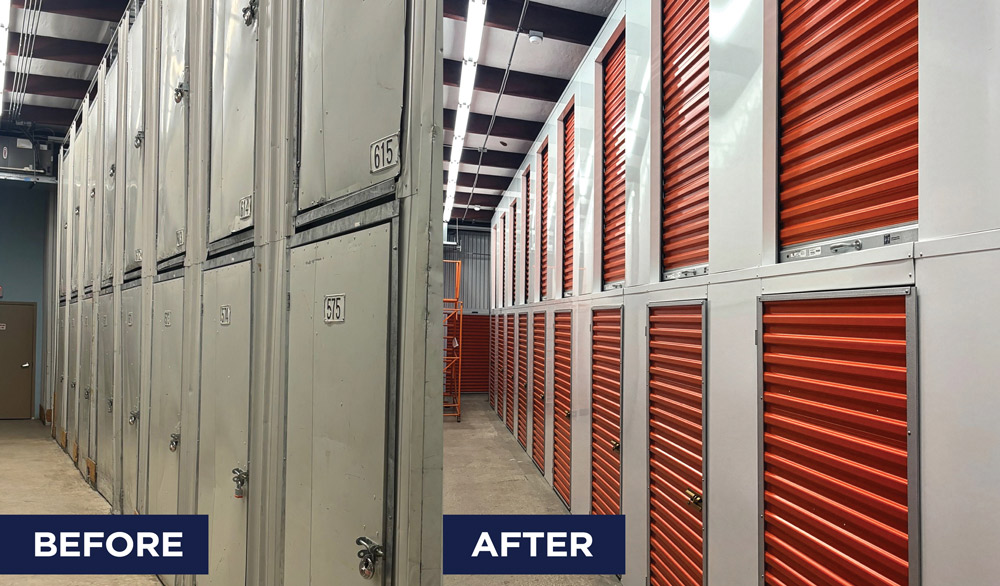
A decade later, another shift was beginning to reshape self-storage. Operators were looking for better ways to secure individual units while also reducing the operational burden associated with traditional locks, keys, and overlocks. Janus saw an opportunity to apply the same philosophy that had driven its physical products for years: Listen to the challenges operators were experiencing and invest in a better solution.
From there, the Nokē Smart Entry System by Janus International was born. With Nokē, Janus helped pioneer the move toward smart security at the individual unit level. By bringing smart locking technology directly to the unit door and connecting it to a broader smart entry platform, operators gained greater visibility and control across their facilities while tenants gained a simpler, more seamless way to access their units.
But Jackson and the Janus team saw the potential for the technology to go much further than replacing a traditional lock. Smart locking technology could become the foundation for a more connected, automated facility. Operators could remotely manage entry, automate access based on a tenant’s account status, better understand activity across a property, and reduce many of the manual processes traditionally associated with facility management.
That vision has continued to drive investment in Nokē. What began as a better way to secure and access an individual storage unit has evolved into a growing ecosystem of smart locks, smart keypads, keyless facility entry points, connected sensors and cameras, mobile applications, and integrated cloud-based management portal. As the industry looks toward increasingly remote and centralized operating models, Janus continues to invest in developing technology designed not only to improve security but to help operators simplify operations, create better tenant experiences, and uncover new opportunities to generate revenue.
At the same time, Janus saw an opportunity to bring that same customer-focused approach to another critical part of the development process: the building itself. As development costs increased and projects became more complex, owners and developers needed solutions that could help them build more efficiently, maximize the potential of each site, and create long-term value without compromising quality.
Janus expanded its building capabilities around that need, bringing together design, engineering, manufacturing, and construction expertise to provide more efficient, value-engineered solutions for self-storage developments of virtually every shape and size. From traditional single-story facilities and large multistory developments to conversions, expansions, and more complex site configurations, Janus works with customers early in the process to identify opportunities to optimize building design, unit mix, materials, and constructability.
That ability to engage earlier allows Janus to look beyond individual components and consider how the pieces of a project work together. By combining deep self-storage expertise with building systems, doors, hallway systems, smart technology, and installation capabilities, Janus helps developers reduce complexity, identify efficiencies, and make informed decisions that support both the economics of construction and the long-term performance of the facility.
Just as importantly, Janus has built these capabilities to scale across North America. Whether a customer is developing a single facility or executing a multi-market development program, the goal is the same: Deliver a consistent, efficient, and value-engineered approach that helps turn a development opportunity into a successful operating asset.
For Jackson, answering that question means continuing to invest ahead of where the industry is going by developing smarter products, creating more efficient building solutions, helping operators transform existing facilities, and advancing smart security technology that can fundamentally change how the next generation of self-storage facilities are developed and operated.
That starts with having the right people in the right seats. As Janus has expanded, the company has continued to invest in teams with deep expertise across self-storage, from engineering and manufacturing to estimating, project management, installation, technology, and customer support. For Jackson, having that experience throughout the organization is critical. It allows Janus to understand not only the product it is providing but how that product fits into the larger realities of developing, renovating, and operating a self-storage facility.
Different challenges have required different solutions, but the process has remained the same: Listen first, invest in understanding the problem, and then build the teams, products, and infrastructure required to solve it.
There is also a simpler commitment behind that philosophy: getting the job done. For customers investing millions of dollars in a new development, renovating an operating facility, or implementing new technology across a portfolio, execution matters. Products must arrive. Projects need to stay on track. Installations must be completed with minimal disruption. And when challenges inevitably arise, customers need a partner willing to take accountability and work through them.
That sense of responsibility has helped Janus build relationships that extend across projects, portfolios, and decades. And as the industry enters another period of change—driven by evolving development economics, increasingly sophisticated operators, greater automation, connected facilities, data, and AI—Jackson sees Janus’ role much as he did at the beginning: Listen closely, invest around the need, and help move the industry forward.
“At the heart of Janus is a commitment to putting customers first, working as a trusted partner to deliver high-quality, innovative solutions while holding ourselves accountable for every commitment we make,” says Jackson. “We strive to make doing business simple and bring the expertise, bold thinking, and global capabilities needed to support our customers wherever they are and wherever their businesses take them.”



From occupancy to revenue.
With your live Hummingbird data.

15 tools. 1 prompt.
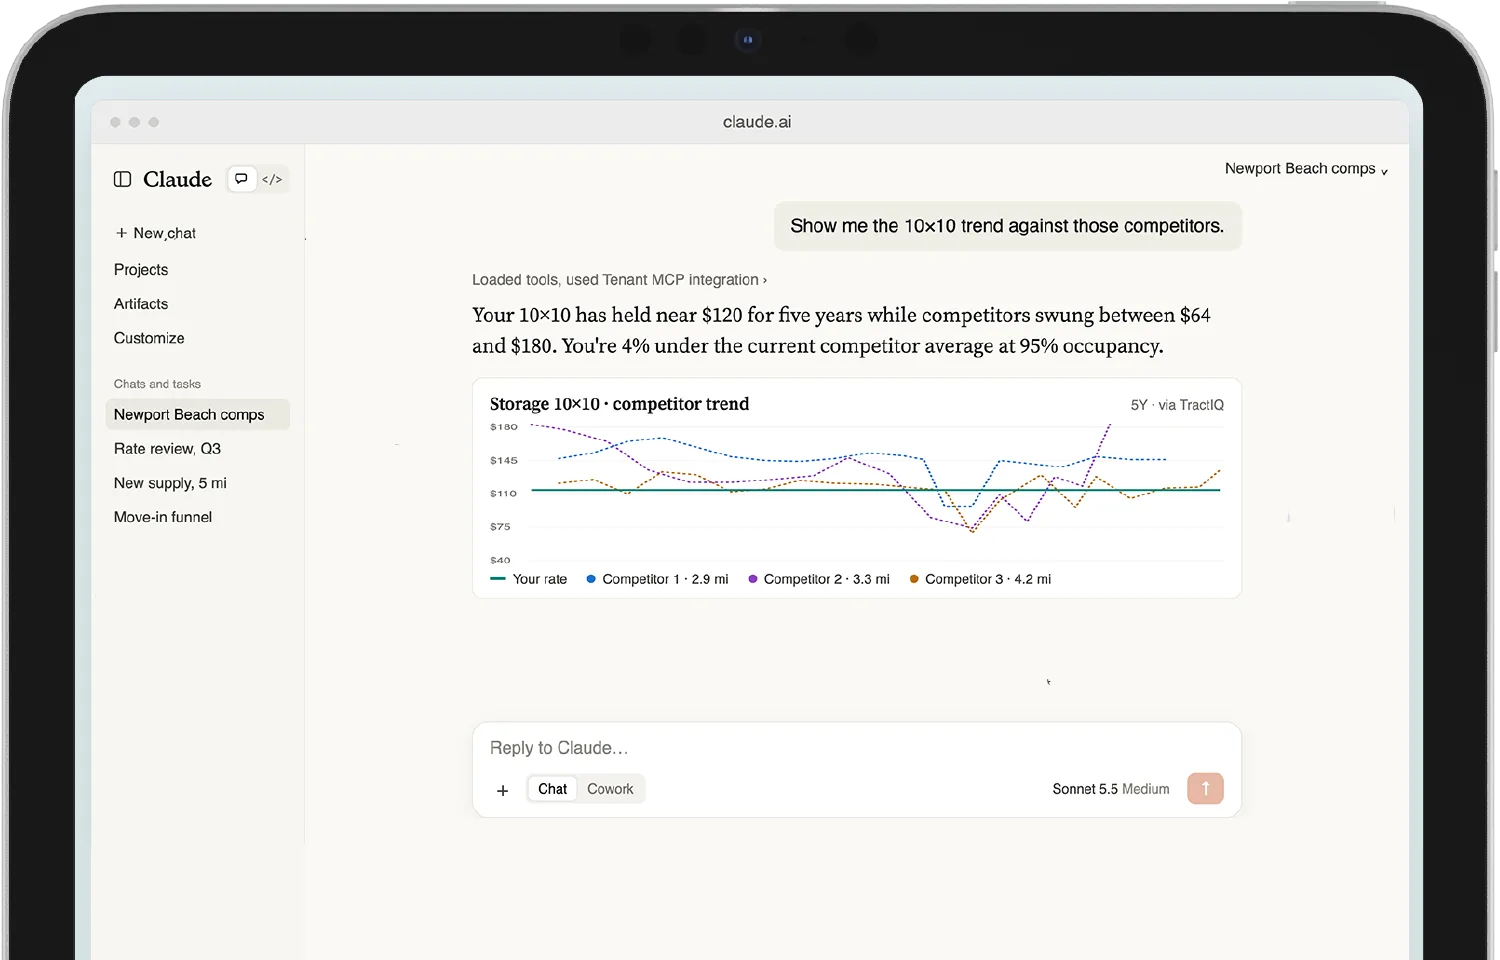
t’s finally here! It’s a whole new ballgame in self-storage, and we have a show for you: big names, big ideas, and experiences unlike anything you’ll find at other self-storage events. Here’s the highlight reel.
Click below to see the full schedule for each event day.
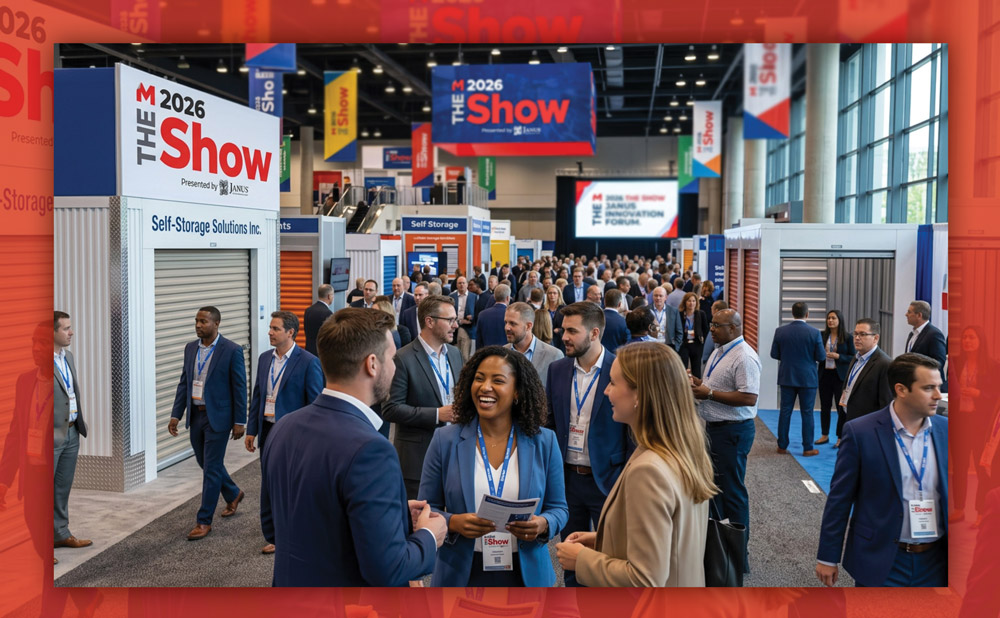
See the full trade show and conference map by downloading the mobile app or by visiting the official event website.
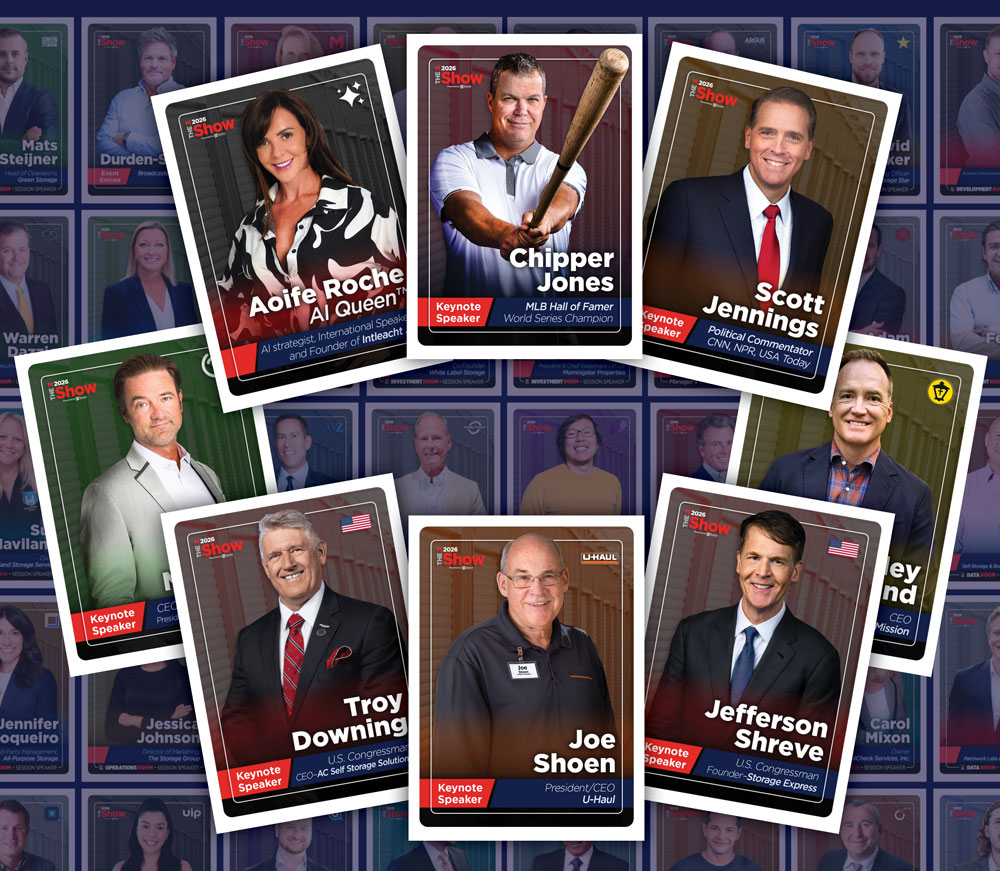
More than 70 industry experts and influential voices address those four pillars, from self-storage veterans to nationally recognized thought leaders. They bring insight, fresh perspectives, and ideas you can put to work as soon as you return from Atlanta.
A versatile and accomplished host, Mark is a trusted choice for a wide range of organizations and events, many of which invite him back year after year. His clients include Samsung, Adobe, Nestlé, Jet Airways, and The World’s 50 Best Restaurants. MSM is thrilled to join the roster and welcome Mark to THE Show!
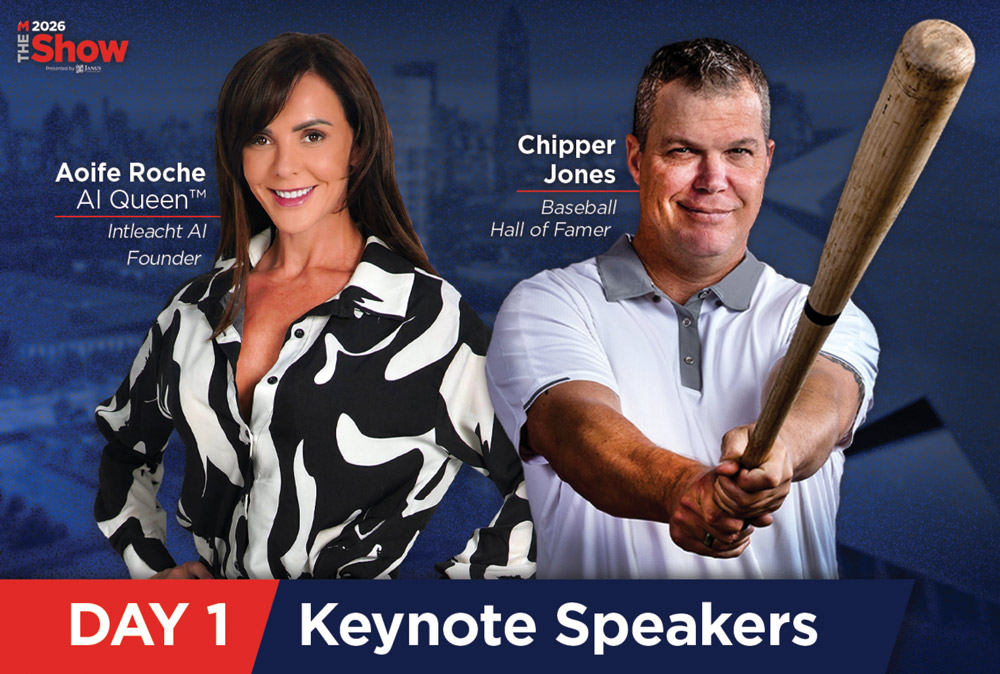
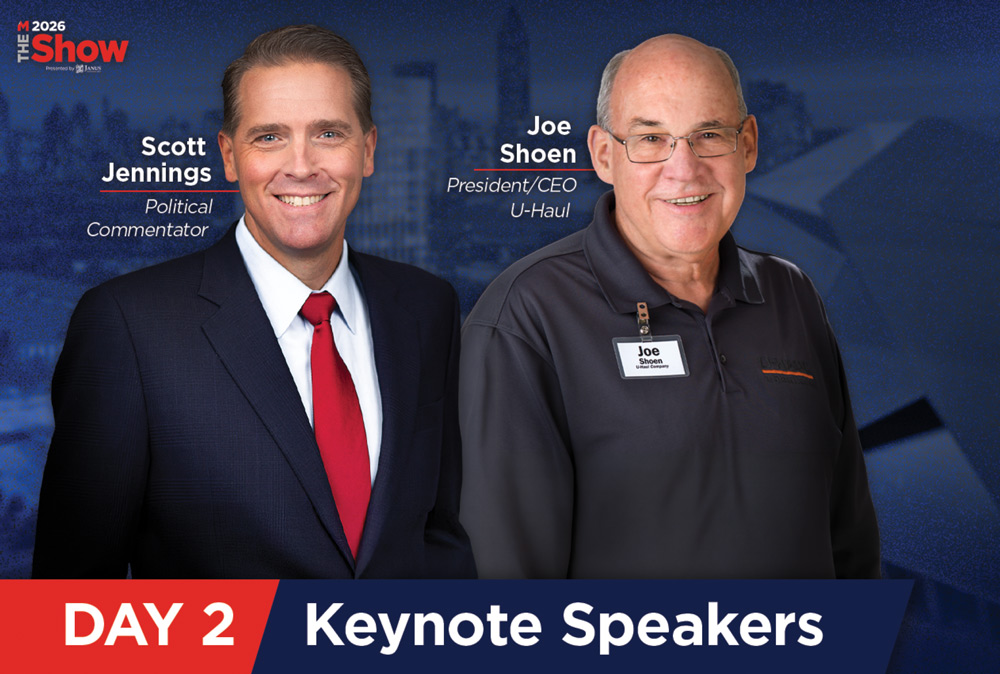
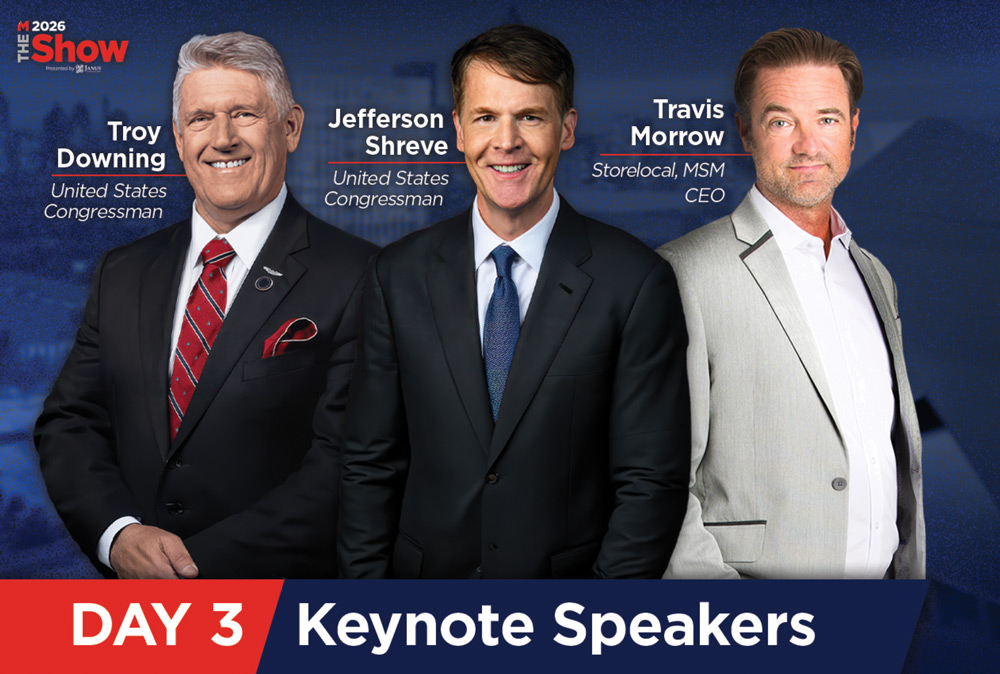
It’s hands-on, actionable education designed to help managers sharpen their skills and solve everyday challenges.
The Deal Room connects self-storage buyers, sellers, investors, and dealmakers in a dedicated space where properties and portfolios are presented and sales and acquisitions are completed.
Powered by TractIQ’s industry data and market intelligence, The Deal Room is where handshakes happen, whether you’re looking to buy, sell, or simply see what’s moving in the market.
This is your chance to exchange ideas, share experiences, and hear how others are tackling the same challenges you face. These candid, peer-to-peer conversations are designed to involve everyone at the table.
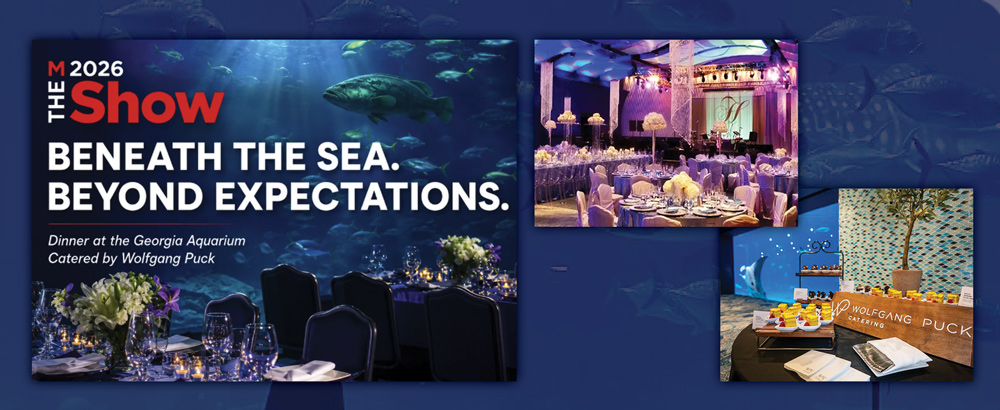
8 p.m. – Red Carpet, Dinner, Awards |
Three days, more than 70 speakers, big names, big ideas, and a whole new self-storage ballgame—welcome to the big leagues. Welcome to THE Show.
Unlock the Power of
Innovation & Technology with

Why Owner/Operators Choose TPP

verall, the U.S. economy experienced unspectacular growth in 2026, with inflation hovering around 3 percent and a mostly cautious Federal Reserve interest rate environment. The housing market has been slowly thawing as mortgage rates stabilize, but people aren’t moving as freely as they once did. Instead of purchasing larger homes, people are opting to store their excess clutter to free up space within their current homes. This lack of movement has fueled longer tenancy at self-storage facilities, which is good for occupancy stability. Rentals rates and new development, on the other hand, have both faced downward pressure due to excess inventory, especially in high-growth markets within the Sun Belt region.
To reach financial goals, some self-storage companies pursued economies of scale through strategic alliances. For instance, Public Storage acquired National Storage Affiliates (NSA) in an all-stock deal valued at approximately $10.5 billion. The merger added more than 1,000 properties, 550,000 units, and roughly 69 million rentable square feet to Public Storage’s portfolio across 37 states and Puerto Rico. Less than two months after that transaction was completed, the REIT acquired the 68-property Public Storage Canada portfolio for approximately $1.2 billion (about $1.67 billion CAD). It totaled 5.3 million rentable square feet within the key markets of Toronto, Vancouver, Montreal, Calgary, and Ottawa. After three consecutive years in second place, these two major wins pushed Public Storage back into the No. 1 spot as the world’s largest self-storage operator.
Dropping down to second is Extra Space Storage, which reported a total of more than 241 million net rentable square feet (NRSF). Since the 2025 Top Operators survey was completed, Extra Space has added approximately 17 million net rentable square feet to its management portfolio, retaining its crown as the largest third-party management company in the industry. In fact, it manages nearly four times as much NRSF as it owns.
Still in third place is CubeSmart with almost 106 million NRSF in its portfolio. CubeSmart manages around 9 million more net rentable square feet than it owns; it has the second-largest third-party management portfolio with 57.5 million NRSF. At 30 million NRSF, Public Storage’s third-party management portfolio remains the fourth largest by NRSF.
With the addition of approximately 10 million NRSF, U-Haul International managed to hold onto fourth place again in 2026. Then, moving up in the ranks to take over NSA’s coveted No. 5 spot is Storage Asset Management (SAM) with almost 40 million NRSF across 657 properties; SAM added roughly 2 million NRSF to its portfolio since last year.
SmartStop Self Storage, which became a publicly traded company in 2025, is now in sixth place, while Storage Rentals of America (SROA) and StorageMart have each moved up two places to No. 7 and No. 8, respectively. Rounding out the top 10 are Prime Group Holdings and Merit Hill Capital.
Unlike last year, none of the 18 newcomers to the list ranked within the top 25. The highest-ranking novice to the list is Storage Star Management at No. 26. Its portfolio totals 9.1 million NRSF. Another noteworthy addition is Legacy Self Storage Management at No. 49. This third-party management company was founded in 2026; a portion of its portfolio was managed by TNT Self Storage Management (No. 77) in 2025.
On the following pages, we present the 2026 Top Operators. As in the past, this list of 100 operators is compiled solely from information submitted in MSM’s annual Top Operators survey and ranked by total net rentable square feet. Please note: Self-storage facilities that are owned and managed by the same company are only tallied in the “Facilities Owned” section of the table. International facilities are included in the grand totals but not listed within the table; that data can be found in MSM’s Top Operators kit.
We would like to extend our congratulations to all the top operators for their ability to adapt and reach new heights despite adversity. Their fortitude and flexibility are certainly worthy of admiration and applause!
- Public Storage**
- Extra Space Storage
- CubeSmart
- U-Haul International**
- Storage Asset Management
- SmartStop Self Storage**
- Storage Rentals of America (SROA)**
- StorageMart**
- Prime Group Holdings (Prime Storage)**
- Merit Hill Capital
- City Line Capital
- William Warren Group (StorQuest Management)
- Westport Properties, Inc. (US Storage Centers)
- Derrel’s Mini Storage
- Andover Properties LLC
- Inland Devon Self Storage
- White Label Storage
- West Coast Self-Storage
- Go Store It
- StoragePRO Management, Inc.
- Absolute Storage Management
- Reliant Real Estate Management, LLC (Midgard Self Storage)
- Amsdell Companies (Compass Self Storage)
- Universal Storage Group
- KO Storage
- Storage Star Management
- Storelocal Storage***
- Brookwood Properties
- Store Space Self Storage
- Rosewood Property Company
- Spartan Investment Group
- Advantage Storage
- 10 Federal Storage
- Baranof Holdings
- Safeguard Self Storage
- Right Move Storage
- Copper Storage Management
- Arcland Property Company LLC
- Trojan Storage
- Space Shop Self Storage
- Guardian Storage Centers
- Urban Self Storage Inc.
- National Storage Management Co.
- Baco Properties
- Avid Storage
- A-1 Self Storage
- Anytime Storage Property Management
- Strat Property Management
- Legacy Self Storage Management
- The Jenkins Organization, Inc.
- Metro Mini Storage
- Cubix Asset Management
- Prestige Capital Management
- Wentworth Property Company
- Dahn Corporation
- Guardian Storage
- Stor-It Self Storage
- Crescendo Self Storage Management
- All-Purpose Storage Management
- 4217 Storage Management
- Packed Planet Self Storage Management
- Budget Store & Lock Self Storage
- Boardwalk Development Group
- StoreAssure
- Five Star Storage
- SKS Management LLC
- SAFStor
- Storage of America
- Stein Investment Group
- All Aboard Storage
- A-American Self Storage
- StorageMax
- Superior Storage
- The Storage Mall Management Group
- DXD Capital
- JustStorage
- TNT Self Storage Management
- Sentry Self Storage Management
- Crescendo Properties
- Artisan Properties
- National Business Management
- Access Self Storage
- Donald Jones Consulting
- Epic Storage Group
- NitNeil Partners
- StorSafe Self Storage Management
- Northwest Building LLC
- Nolan Inc. / Nolan Bros of Texas
- McGregor Interests Inc
- Synergy Storage Group
- Columbia Storage Group
- Haviland Storage Services
- Cox's Armored Mini Storage Management, Inc.
- Storage Corner Group, LLC
- Just-A-Closet Self Storage
- Peoples Choice Storage
- Advantage Consulting & Management
- Uplift Real Estate Services
- RHW Capital Management Group LLC
- Pankey Properties LLC
-
2811 Internet Boulevard
Frisco, TX 75034Phone: (469) 649-9486
Email: mbarnett2@publicstorage.com
Website(s): www.publicstorage.com
OWNER/PRESIDENT: Tom Boyle
Contact: Mary Beth Barnett
Founded: 1972
Number of Facilities: 4,731
Total net rentable square footage: 336,300,000 -
2795 E. Cottonwood Parkway, #300
Salt Lake City, UT 84121Phone: (801) 562-5556
Email: info@extraspace.com
Website(s): www.extraspace.com
OWNER/PRESIDENT: Publicly Traded
Contact: Grace Houser
Founded: 1977
Number of Facilities: 4,410
Total net rentable square footage: 241,046,352
Expansion plans: Extra Space will continue to expand strategically over the next 12 months through acquisitions, third-party management growth, and investments that strengthen its market position. -
5 Old Lancaster Road
Malvern, PA 19355Phone: (610) 535-5700
Email: jschutzer@cubesmart.com
Website(s): www.cubesmart.com
OWNER/PRESIDENT: Chris Marr
Contact: Josh Schutzer
Founded: 2004
Number of Facilities: 1,534
Total net rentable square footage: 105,967,567
Number of Facilities in Development: 1
Expansion plans: The company will be targeting continued investment aligned with its core strategy to expand in high-demographic, top-40 MSAs. -
2727 N. Central Avenue
Phoenix, AZ 85004Phone: (602) 263-6811
Email: uhaul_publications.com
Website(s): www.UHaul.com
OWNER/PRESIDENT: Joe Shoen
Contact: Sebestien Reyes
Founded: 1945
Number of Facilities: 2,138
Total net rentable square footage: 101,035,015
Number of Facilities in Development: 175
Expansion plans: The company plans to expand through new construction, conversions of existing facilities, and acquisition of existing storage facilities. -
3501 Concord Road, Suite 200
York, PA 17402Phone: (717) 779-0044
Email: info@storageasset.com
Website(s): www.storageassetmanagement.com
OWNER/PRESIDENT: Alyssa Quill
Contact: Melissa Stiles
Founded: 2010
Number of Facilities: 657
Total net rentable square footage: 39,454,199
Expansion plans: The company’s priority is delivering exceptional results for the properties it currently manages. By maintaining an owner’s mindset and consistently creating value, it can build strong relationships and earn opportunities to bring new properties into the SAM portfolio when their goals align and they are the right fit for a successful partnership. SAM also has contracts in place with four facilities that are in development. -
10 Terrace Road
Ladera Ranch, CA 92694Phone: (949) 429-6600
Email: info@smartstop.com
Website(s): www.smartstop.com
OWNER/PRESIDENT: H. Michael Schwartz
Contact: Rhonda Williams
Founded: 2005
Number of Facilities: 461
Total net rentable square footage: 35,827,000
Number of Facilities in Development: 9
Expansion plans: The company plans to grow through targeted growth and stabilized assets in markets across the U.S., either through acquisition or management of properties through SmartStop3PM, where they believe they can achieve economies of scale. In addition, SmartStop is targeting growth in the Greater Toronto Area and other major CMAs across Canada. -
2751 S. Dixie Highway, Suite 450
West Palm Beach, FL 33405Phone: (561) 412-4719
Email: pkennedy-whann@sroa.com
Website(s): www.SROA.com
OWNER/PRESIDENT: Benjamin Macfarland
Contact: Melissa Cartagena
Founded: 2013
Number of Facilities: 719
Total net rentable square footage: 33,808,310
Number of Facilities in Development: 2
Expansion plans: The company plans to add 10 facilities to its portfolio. -
215 N. Stadium Boulevard, Suite 207
Columbia, MO 65203Phone: (573) 268-0997
Email: sarah.little@storage-mart.com
Website(s): www.storage-mart.com
OWNER/PRESIDENT: Cris Burnam
Contact: Sarah Little
Founded: 1999
Number of Facilities: 374
Total net rentable square footage: 33,799,000
Number of Facilities in Development: 3
Expansion plans: The company’s growth strategy is deliberate and market-driven, focused on acquisition opportunities, third-party management, and new development in markets where population density, housing dynamics, and competitive supply create favorable long-term conditions. The company prioritizes markets where it can achieve meaningful local scale rather than isolated single-site entry. It’s equally focused on optimizing performance within its existing portfolio by improving the customer experience, digital visibility, and revenue per square foot as it is on adding net new locations. -
395 Broadway
Saratoga Springs, NY 12866Phone: (518) 615-0552
Email: mitchell.rager@goprimegroup.com
Website(s): www.goprimegroup.com
OWNER/PRESIDENT: Robert J. Moser
Contact: Mitchell Rager
Founded: 2013
Number of Facilities: 359
Total net rentable square footage: 27,620,000
-
41 Flatbush Avenue, Suite 5A
Brooklyn, NY 11217Phone: (917) 398-5152
Email: ir@merithillcapital.com
Website(s): www.merithillcapital.com
OWNER/PRESIDENT: Liz Raun Schlesinger
Contact: Jennifer Builes
Founded: 2016
Number of Facilities: 371
Total net rentable square footage: 24,254,497
Expansion plans: The company plans to acquire one-off and small portfolios with value-add or turnaround components in markets that have compelling supply-and-demand fundamentals. -
1 Presidential Boulevard
Bala Cynwyd, PA 19004Phone: (518) 944-0741
Email: rschontz@citylinecapital.com
Website(s): www.citylinecapital.com
OWNER/PRESIDENT: Richard Schontz
Founded: 2017
Number of Facilities: 320
Total net rentable square footage: 20,200,000
Expansion plans: The company plans to acquire 50 properties annually. -
100 Wilshire Boulevard, Floor 4
Santa Monica, CA 90401Phone: (301) 451-2130
Email: jciminillo@williamwarren.com
Website(s): www.williamwarren.com
OWNER/PRESIDENT: William Hobin
Contact: Jennifer Ciminillo
Founded: 1994
Number of Facilities: 268
Total net rentable square footage: 17,523,006
Number of Facilities in Development: 2
Expansion plans: The company plans to add one facility to its portfolio. -
660 Newport Center Drive, Suite 1450
Newport Beach, CA 92660Phone: (949) 748-5900
Email: info@westportproperties.net
Website(s): www.westportproperties.net
OWNER/PRESIDENT: Drew Hoeven
Contact: Jason Lopez
Founded: 1985
Number of Facilities: 229
Total net rentable square footage: 16,422,985
Number of Facilities in Development: 4
Expansion plans: The company plans to opportunistically develop, acquire, and manage facilities within the major MSAs and within its existing footprint. -
3239 W. Ashlan Avenue
Fresno, CA 93722Phone: (559) 224-9900
Email: contactus@derrels.com
Website(s): www.derrels.com
OWNER/PRESIDENT: Derrel A. Ridenour
Contact: Gabriel Luna
Founded: 1963
Number of Facilities: 70
Total net rentable square footage: 15,915,245
Number of Facilities in Development: 8
Expansion plans: The company plans to add eight facilities to its portfolio. -
780 3rd Avenue
New York, NY 10017Phone: (212) 813-0141
Email: mwachsman@andoverprop.com
Website(s): www.storagekingusa.com; www.andoverprop.com
OWNER/PRESIDENT: William Cohen and Brian Cohen
Contact: Adam Kutner
Founded: 2003
Number of Facilities: 179
Total net rentable square footage: 15,116,904
Expansion plans: The company plans to continue to own, acquire, develop, manage, and finance facilities throughout the country, ranging from value-add properties to stabilized assets in core to tertiary markets. It has active expansion plans for many of its existing facilities. In addition to self-storage, it’s active in other alternative real estate asset classes, such as RV parks, manufactured housing, small bay industrial, and car washes, and has a financing arm for all of these verticals as well. -
2901 Butterfield Road
Oak Brook, IL 60253Phone: (630) 218-8000
Email: nicole.spreck@inlandgroup.com
Website(s): www.devonselfstorage.com
OWNER/PRESIDENT: Matthew Tice
Contact: Nicole Spreck
Founded: 1985
Number of Facilities: 212
Total net rentable square footage: 13,823,356
Number of Facilities in Development: 1
Expansion plans: At Devon Self Storage, the growth strategy over the next 12 months remains focused on disciplined expansion, operational excellence, and delivering an exceptional customer experience. Devon intends to continue growing its portfolio through strategic acquisitions and third-party management opportunities in markets that align with its long-term investment objectives. In addition to expanding its footprint, Devon is investing in technology, digital marketing, and revenue management initiatives that enhance operational efficiency and drive performance across its properties. Devon remains committed to building strong partnerships with property owners, optimizing asset value, and identifying opportunities where its management platform and customer-centric approach can create measurable results. Its goal is not simply to add locations but to ensure sustainable growth by bringing best-in-class operations, marketing, and customer service to every facility it manages. -
214 Greene Avenue
Brooklyn, NY 11238Phone: (626) 590-0423
Email: contact@whitelabelstorage.com
Website(s): www.whitelabelstorage.com
OWNER/PRESIDENT: Peter Smyth, Alex Hartman
Contact: Liisi Fall
Founded: 2018
Number of Facilities: 396
Total net rentable square footage: 12,501,417
Expansion plans: White Label Storage’s expansion plans center on two areas: continued investment in its proprietary technology platform and disciplined growth of its managed portfolio. On the technology side, White Label is expanding its in-house product suite, building on the recent launch of RevMan ai (revenue management) with additional proprietary tools designed to drive NOI for facility owners. On the portfolio side, White Label is focused on deepening its footprint with independent owners and portfolios across its existing 43-state footprint. Its growth strategy remains rooted in its founding principle of delivering institutional-quality management to independent operators without long-term contracts, earning client retention through performance rather than contractual lock-in. -
808 134th Street SW, Suite 211-B
Everett, WA 98204Phone: (206) 501-2234
Email: jeisenbarth@wcselfstorage.com
Website(s): www.WestCoastSelfStorage.com
OWNER/PRESIDENT: Jim McNamee
Founded: 2006
Number of Facilities: 170
Total net rentable square footage: 12,262,065
Number of Facilities in Development: 1
Expansion plans: West Coast Self-Storage plans to grow 15 to 20 stores through management, acquisition, and development. -
4210 Yancey Road
Charlotte, NC 28217Phone: (828) 676-3888
Email: ajones@gostoreit.com
Website(s): www.gostoreit.com
OWNER/PRESIDENT: Ryan Hanks
Contact: Andrew Jones
Founded: 2013
Number of Facilities: 202
Total net rentable square footage: 11,400,000
-
1615 Bonanza Street, Suite 208
Walnut Creek, CA 94596Phone: (925) 938-6300
Email: results@storagepro.com
Website(s): www.storagepromanagement.com
OWNER/PRESIDENT: Stephen Mirabito
Contact: Melissa Shandor
Founded: 1974
Number of Facilities: 169
Total net rentable square footage: 11,220,875
Expansion plans: The company plans to continue to expand its footprint throughout the United States. -
1630 Bonnie Lane, Suite 106
Cordova, TN 38016Phone: (678) 779-1978
Email: jasmin.allen@absolutemgmt.com
Website(s): www.aboutASM.com
OWNER/PRESIDENT: Scott Beatty
Contact: whitney.wood@absolutemgmt.com
Founded: 2002
Number of Facilities: 169
Total net rentable square footage: 10,782,391
Number of Facilities in Development: 8
Expansion plans: Over the next 12 months, Absolute plans to strategically grow its third-party management portfolio by expanding its presence in existing markets, entering targeted new markets, growing multi-property partnerships, and increasing remote management opportunities. The company will continue investing in its people, technology, and resources to support sustainable growth. -
1146 Canton Street
Roswell, GA 30075Phone: (770) 609-8276
Email: tallen@reliant-mgmt.com
Website(s): www.reliant-mgmt.com
OWNER/PRESIDENT: Todd Allen, Lew Pollack
Founded: 2010
Number of Facilities: 118
Total net rentable square footage: 10,445,813
Number of Facilities in Development: 3
Expansion plans: The company plans to add more facilities in its existing footprint as well as continue to seek development opportunities. -
20445 Emerald Parkway Drive, Suite 220
Cleveland, OH 44135Phone: (216) 458-0670
Email: tca@amsdellcompanies.com
Website(s): www.compassselfstorage.com
OWNER/PRESIDENT: Todd C. Amsdell
Contact: Katie Fete
Founded: 2007
Number of Facilities: 138
Total net rentable square footage: 10,086,602
Expansion plans: The company plans to continue to acquire existing facilities, develop new sites, and convert existing buildings to self-storage. -
3350 Riverwood Parkway
Atlanta, GA 30339Phone: (231) 447-3874
Email: marketing@universalstoragegroup.com
Website(s): www.universalstoragemanagement.com
OWNER/PRESIDENT: USG Leadership Team/AJ Ross
Contact: Kim Hoelting
Founded: 2013
Number of Facilities: 122
Total net rentable square footage: 9,357,225
Expansion plans: USG plans to continue taking on new management and consulting clients while expanding its operations and corporate teams to continue delivering best-in-class results for its property owners. -
10301 Wayzata Boulevard
Minnetonka, MN 55305Phone: (952) 491-6837
Email: charles@kostorage.com
Website(s): www.kostorage.com
OWNER/PRESIDENT: Andrew Freeman
Contact: Matthew Petersburs
Founded: 2016
Number of Facilities: 247
Total net rentable square footage: 9,255,000
Number of Facilities in Development: 1
Expansion plans: The company plans to add one facility to its portfolio. -
8950 Cal Center Drive
Sacramento, CA 95864Phone: (916) 571-1940
Email: investors@storagestar.com
Website(s): www.storagestar.com
OWNER/PRESIDENT: Matt Garibaldi
Contact: David Decker
Founded: 2017
Number of Facilities: 128
Total net rentable square footage: 9,100,000
Number of Facilities in Development: 3 -
5281 California Avenue, Suite 320
Irvine, CA 92617Phone: (210) 324-8891
Email: info@storelocal.com
Website(s): www.storelocal.com
PRESIDENT: Travis Morrow
Contact: Emily O’Leary
Founded: 2020
Number of Facilities: 102
Total net rentable square footage: 8,100,000
Number of Facilities in Development: 17
Expansion plans: The company is planning significant growth in Idaho, Florida, and California, with additional states on the roadmap as well. -
10202 Jefferson Highway
Baton Rouge, LA 70809Phone: (225) 769-1250
Email: rpiper@thestoragecenter.com
Website(s): www.thestoragecenter.com
OWNER/PRESIDENT: Craig Smith
Contact: R. Piper
Founded: 1986
Number of Facilities: 76
Total net rentable square footage: 7,500,000
Number of Facilities in Development: 5
Expansion plans: Brookwood Properties plans to acquire and develop self-storage facilities within the Southeast United States. -
330 E. Crown Point Road
Winter Garden, FL 34787Phone: (833) 358-2661
Email: inquiries@storespace.com
Website(s): www.storespace.com
CEO: Chris Harris
PRESIDENT: Rob Consalvo
Contact: Eric Mees
Founded: 2017
Number of Facilities: 90
Total net rentable square footage: 7,046,518
Number of Facilities in Development: 1
Expansion plans: The company is excited about the year ahead and is actively looking for opportunities to continue expanding its portfolio. Its focus remains on growing its footprint across the U.S. through strategic acquisitions and expansion opportunities.
-
2101 Cedar Springs Road, Suite 1600
Dallas, TX 75201Phone: (214) 849-9041
Email: bcooke@rosewood.com
Website(s): www.rosewoodproperty.com
OWNER/PRESIDENT: Rick Perdue
Contact: Sunwest Communications
Founded: 1976
Number of Facilities: 86
Total net rentable square footage: 6,876,606
Expansion plans: Rosewood Property Company plans to continue to grow the portfolio through strategic acquisitions, development, and expansions. -
17301 W. Colfax Avenue, Suite 120
Golden, CO 80401Phone: (720) 370-7837
Email: investors@spartan-investors.com
Website(s): www.spartan-investors.com
PRESIDENT/CIO/OWNER: Ryan Gibson
CEO/OWNER: Scott Lewis
Contact: Baptiste Tricoire
Founded: 2014
Number of Facilities: 90
Total net rentable square footage: 6,625,258
Number of Facilities in Development: 1
Expansion plans: Spartan Investment Group plans to continue expanding its portfolio with adding as many of 25 properties in 2027. -
7201 Bishop Road, Suite 250
Plano, TX 75024Phone: (830) 444-1042
Email: trockafellow@advantagestorage.net
Website(s): www.advantagestorage.net
OWNER/PRESIDENT: Cory Horne
Contact: Trent Rockafellow
Founded: 1996
Number of Facilities: 72
Total net rentable square footage: 6,490,722
Number of Facilities in Development: 2
Expansion plans: In 2026, the company has added 18 facilities totaling 1.8 million NRSF. By the end of 2027, it expects to be managing 100 facilities totaling around 10 million NRSF. -
3301 Atlantic Avenue
Raleigh, NC 27604Phone: (855) 744-1010
Email: admin@10federalstorage.com
Website(s): www.10FederalStorage.com
PRESIDENT: Geoff Hayth
Founded: 2015
Number of Facilities: 130
Total net rentable square footage: 6,451,147
Number of Facilities in Development: 2
Expansion plans: The company plans to add two additional ground-up locations located in Charlotte, N.C., and Dallas, Ga. -
2850 N. Harwood Street
Dallas, TX 75201Phone: (972) 402-5710
Email: rfoley@baranofholdings.com
Website(s): www.baranofholdings.com
OWNER/PRESIDENT: Andy Hendricks and Andrew Aiken
Contact: Reaghan Foley
Founded: 2015
Number of Facilities: 98
Total net rentable square footage: 6,227,208
Number of Facilities in Development: 2 -
3348 Peachtree Road NE, Suite 940
Atlanta, GA 30326Phone: (404) 231-4000
Email: kurt@safeguardit.com
Website(s): www.safeguardit.com
OWNER/PRESIDENT: Mark Degner
Contact: Kurt Kleindienst
Founded: 1989
Number of Facilities: 96
Total net rentable square footage: 5,580,150
Number of Facilities in Development: 10
Expansion plans: The company maintains a robust development pipeline and is expanding by 10 to 15 facilities annually through strategic acquisitions. Thanks to its expert team, they are able to sucessfully execute and close transactions within 30 to 45 days. -
5858 Westheimer Road, Suite 100
Houston, TX 77057Phone: (713) 789-2200
Email: dkelley@rightmovestorage.com
Website(s): www.rightmovestorage.com
OWNER/PRESIDENT: Darren Kelley
Contact: Jeremy Rollwitz
Founded: 2014
Number of Facilities: 85
Total net rentable square footage: 5,048,948
Number of Facilities in Development: 5
Expansion plans: The company plans to attend national conferences for networking, attend state conferences for networking, hold local open houses for interested owners, and promote third-party management via website. -
174 Island Breeze Avenue
Daytona Beach, FL 32124Phone: (855) 601-2340
Email: jacob.copper@coppersm.com
Website(s): www.copperstoragemanagement.com
OWNER/PRESIDENT: Jacob Copper
Contact: Tess Toth
Founded: 2019
Number of Facilities: 145
Total net rentable square footage: 5,032,665
Expansion plans: The company expects to onboard three to four facilities per month. -
1055 Thomas Jefferson Street NW
Washington, DC 20007Email: anthony@arc.land
Website(s): www.arc.land
OWNER/PRESIDENT: Noah Mehrkam
Founded: 2006
Number of Facilities: 58
Total net rentable square footage: 4,951,000
Number of Facilities in Development: 15
Expansion plans: The company plans to grow through acquisition and development/construction in Mid-Atlantic and Southeastern U.S. -
222 N. Pacific Coast Highway, Suite 1900
El Segundo, CA 90245Phone: (310) 372-8600
Email: pflorida@trojanstorage.com
Website(s): www.trojanstorage.com
OWNER: Brett Henry
PRESIDENT: Pedro Florida
Contact: Pedro Florida
Founded: 2007
Number of Facilities: 56
Total net rentable square footage: 4,941,825
Number of Facilities in Development: 5
Expansion plans: The company has plans for three expansions in three states.
-
5607 Glenridge Drive NE, Suite 200
Atlanta, GA 30342Phone: (248) 795-8126
Email: alison@spaceshopselfstorage.com
Website(s): www.spaceshopselfstorage.com/third-party-management
OWNER/PRESIDENT: Cliff Hite
Contact: jgunn@spaceshopselfstorage.com
Founded: 2017
Number of Facilities: 56
Total net rentable square footage: 4,900,000
Number of Facilities in Development: 36
Expansion plans: The company plans to strategically enter new markets and continue expanding in its existing markets. -
2042 Business Center Drive, #100
Irvine, CA 92612Phone: (714) 390-5525
Email: john@guardiansc.com
Website(s): www.storamericastorage.com
OWNER/PRESIDENT: John Minar
Contact: Spin Group
Founded: 1999
Number of Facilities: 51
Total net rentable square footage: 4,713,546
Number of Facilities in Development: 3
Expansion plans: The company plans to expand by three to five projects. -
918 S. Horton Street, Suite 1000
Seattle, WA 98134Phone: (206) 322-4868
Email: info@urbanstorage.com
Website(s): www.urbanstorage.com
OWNER/PRESIDENT: Patrick Reilly
Contact: Patrick Reilly
Founded: 1986
Number of Facilities: 82
Total net rentable square footage: 4,555,366 -
32300 Northwestern Highway, Suite 110
Farmington Hills, MI 48334Phone: (248) 855-9676
Email: daniel@nationalstoragemgmt.com
Website(s): www.nationalstoragemgmt.com
OWNER/PRESIDENT: Maurice Pogoda
Contact: Daniel Pogoda
Founded: 1987
Number of Facilities: 74
Total net rentable square footage: 4,400,000
Expansion plans: The company, which is in a heavy growth mode, plans to add five to 10 stores across the midwest. -
128 King Street
San Francisco, CA 94107Phone: (415) 281-3700
Email: mgifford@bacoproperties.com
Website(s): www.bacoproperties.com; www.securitypublicstorage.com
OWNER/PRESIDENT: Ben Eisler
Contact: Matt Gifford
Founded: 1983
Number of Facilities: 53
Total net rentable square footage: 4,294,209 -
8350 N. Central Expressway, Suite 430
Dallas, TX 75206Phone: (214) 389-3939
Email: vstephens@avidstorage.com
Website(s): www.avidstorage.com
OWNER/PRESIDENT: Jarrett Reed and Timothy Springer
Contact: Vanessa Stephens
Founded: 2023
Number of Facilities: 49
Total net rentable square footage: 4,165,424
Number of Facilities in Development: 1
Expansion plans: The company plans to add 10 to 20 locations in the next 12 months. -
4579 Mission Gorge Place, Suite A
San Diego, CA 92120Phone: (800) 210-8979
Email: a1kirkham@a1storage.com
Website(s): www.a1storage.com
OWNER/PRESIDENT: Brian R. Caster
Contact: Margo Tannewitz
Founded: 1983
Number of Facilities: 55
Total net rentable square footage: 4,152,160 -
3400 W. Marshall Avenue
Longview, TX 75604Phone: (903) 470-7995
Email: partner@anytimestorage.com
Website(s): www.TrustASPM.com
OWNER/PRESIDENT: Adam Wagner
Contact: Sydney Marsolan
Founded: 2012
Number of Facilities: 89
Total net rentable square footage: 3,993,655
Number of Facilities in Development: 1
Expansion plans: Over the next 12 months, Anytime Storage Property Management plans to expand its third-party management portfolio while bringing its Remote Concierge Manager (RCM) platform to a broader segment of the self-storage industry. This includes licensing RCM to other operators and management companies, expanding into new markets, and continuing to develop scalable, technology-driven solutions that improve operational efficiency, customer experience, and facility performance. -
2055 3rd Avenue, #200
San Diego, CA 92101Phone: (619) 295-2211
Email: wecare@stratprop.com
Website(s): www.stratprop.com
OWNER/PRESIDENT: Donald Clauson
Contact: Diana Buchheit
Founded: 1999
Number of Facilities: 46
Total net rentable square footage: 3,987,300
Number of Facilities in Development: 2
Expansion plans: The company plans to add or build facilities in the company’s current markets. -
1260 N. Hancock Street, Suite #101A
Anahiem, CA 92807Phone: (714) 900-0579
Email: grady@legacystoragemanagement.com
Website(s): www.legacystoragemanagement.com
OWNER/PRESIDENT: Ray Tuohy
Founded: 2026
Number of Facilities: 54
Total net rentable square footage: 3,813,035
Expansion plans: Legacy Self Storage Management plans to expand management into the same markets it’s in but mainly new markets.
-
10600 Shadow Wood Drive
Houston, TX 77043Phone: (281) 757-3373
Email: dwight@jenkinsorg.com
Website(s): www.jenkinsorg.com
OWNER/PRESIDENT: Ricky Jenkins
Founded: 1989
Number of Facilities: 56
Total net rentable square footage: 3,728,741
Expansion plans: The company plans to add five to 10 third-party management facilities to its portfolio. -
100 Metro Parkway
Pelham, AL 35124Phone: (205) 443-3522
Email: shane@metrocompanies.com
Website(s): www.metroministorage.com
OWNER/PRESIDENT: Eddie Lumpkin
Contact: Shane Sisk
Founded: 1978
Number of Facilities: 26
Total net rentable square footage: 3,650,000
Number of Facilities in Development: 2
Expansion plans: The company is currently adding to four of its facilities. -
PO Box 699
Danville, CA 94526Phone: (925) 489-1114
Email: consulting@cubixstorage.com
Website(s): www.cubixassetmanagement.com
OWNER/PRESIDENT: George Huff, Sean Venezia, Ed Boersma
Contact: Debbie Kuo
Founded: 2007
Number of Facilities: 53
Total net rentable square footage: 3,635,881
Number of Facilities in Development: 3
Expansion plans: The company plans to expand its portfolio with the addition of two facilities. -
383 N. Front Street
Columbus, OH 43215Phone: (614) 930-6021
Email: cory@prestigestorage.com
Website(s): www.prestigestorage.com
OWNER/PRESIDENT: Cory Bonda
Contact: Cory Bonda
Founded: 2016
Number of Facilities: 80
Total net rentable square footage: 3,612,983
Expansion plans: Prestige Capital Management is actively seeking acquisition and development opportunities in new and existing markets, with a goal of adding 10 to 12 properties per year. -
802 N. 3rd Avenue
Phoenix, AZ 85003Phone: (602) 875-5000
Email: sgordon@wentprop.com
Website(s): www.wentworthproperty.com
OWNER/PRESIDENT: James Wentworth
Contact: Stephanie Gordon
Founded: 2005
Number of Facilities: 41
Total net rentable square footage: 3,583,657
Number of Facilities in Development: 8
Expansion plans: The company is anticipating delivering three to five new facilities and acquiring 10 to 20 existing facilities. -
4675 MacArthur Court, Suite 1400
Newport Beach, CA 92260Phone: (949) 752-1282
Email: rbradley@dahncorp.com
Website(s): www.miniustorage.com
OWNER/PRESIDENT: Brian A. Dahn
Contact: Robert Bradley
Founded: 1970
Number of Facilities: 48
Total net rentable square footage: 3,437,781
Expansion plans: The company plans to build or acquire three to five projects per year. -
5879 Centre Avenue
Pittsburgh, PA 15206Phone: (412) 661-7368
Email: coz@guardianstorage.com
Website(s): www.GuardianStorage.com
OWNER/PRESIDENT: Steven Cohen
Founded: 1987
Number of Facilities: 41
Total net rentable square footage: 3,192,424
Number of Facilities in Development: 1
Expansion plans: Guardian Storage will continue to build new ground-up developments and acquire existing properties in locations that meet its criteria. -
PO Box 140337
Boise, ID 83714Phone: (208) 376-8750
Email: contactus@stor-it.com
Website(s): www.stor-it.com
OWNER/PRESIDENT: Avest, LP
Contact: David Hurless
Founded: 1972
Number of Facilities: 20
Total net rentable square footage: 3,146,451
Number of Facilities in Development: 2
Expansion plans: The company plans to continue to purchase, expand, and build. -
3001 Lava Ridge Court, Suite 130
Roseville, CA 95661Phone: (916) 276-6202
Email: jordan@cpinc.us
Website(s): www.propertymanagement.storage
OWNER/PRESIDENT: Jordan Mills
Number of Facilities: 50
Total net rentable square footage: 3,117,513
Expansion plans: Crescendo Self Storage Management plans to continue to expand its third-party footprint throughout the Western U.S. -
250 Marlboro Street, Suite 3
Keene, NH 03431Phone: (203) 565-9189
Email: jenniferb@storeallpurpose.com
Website(s): www.allpurposemanagement.com
OWNER/PRESIDENT: Diane Cyr COO
Contact: Jennifer Barroqueiro
Founded: 1998
Number of Facilities: 100
Total net rentable square footage: 3,000,000
Expansion plans: The company plans to add an additional 24 locations to its portfolio.
-
4217 Lakeway Boulevard
Austin, TX 78734Phone: (281) 235-3528
OWNER/PRESIDENT: Hugh Bellomy
Contact: Brooke White
Founded: 2020
Number of Facilities: 32
Total net rentable square footage: 2,993,777
Expansion plans: The company plans to expand its portfolio by six to eight properties. -
819 W. Little Creek Road
Norfolk, VA 23505Phone: (757) 998-8481
Email: camille@packedplanet.com
Website(s): www.packedplanet.com
OWNER/PRESIDENT: Tom Nicholson III
Contact: Camille Broom
Founded: 1973
Number of Facilities: 47
Total net rentable square footage: 2,942,276
Number of Facilities in Development: 1
Expansion plans: Packed Planet seeks to be awarded new third-party management and stand-alone service contracts while continuing to deliver high-value service and innovative solutions to its current client base. -
1090 MacArthur Road
White Hall, PA 18052Phone: (610) 952-2122
Email: budgetstorageus@yahoo.com
Website(s): www.budgetstorageandlock.com
OWNER/PRESIDENT: Joe Mooney, Mike Moyer
Contact: Mike Moyer
Founded: 1997
Number of Facilities: 54
Total net rentable square footage: 2,877,000 -
1325 Satellite Boulevard NW
Suwanee, GA 30024Phone: (770) 640-0022
Email: dougS@boardwalkstorage.com
Website(s): www.boardwalkselfstorage.com
OWNER/PRESIDENT: Doug Steverson
Contact: amy@boardwalkstorage.com
Founded: 2016
Number of Facilities: 46
Total net rentable square footage: 2,815,016
Number of Facilities in Development: 3
Expansion plans: The company will continue to develop where it makes sense to do so. -
10608 Industrial Avenue, #100
Roseville, CA 95678Phone: (916) 633-6500
Email: jbelles@thomasmanagementllc.com
Website(s): www.storeassure.net
OWNER/PRESIDENT: Jason Belles
Founded: 2012
Number of Facilities: 27
Total net rentable square footage: 2,689,000 -
3255 43rd Street South
Fargo, ND 58104Phone: (701) 367-5860
Email: ben@fivestarstorage.biz
Website(s): www.fivestarstorage.biz
OWNER/PRESIDENT: Ben Hendricks
Contact: Eric Gardner
Founded: 2004
Number of Facilities: 46
Total net rentable square footage: 2,685,000
Expansion plans: The company will continue finding partnerships with owners looking to join its platform through either third-party management or contribute asset(s) to its fund or traditional sale. Small expansion projects at select locations will also be on the table in the next 12 months. -
7901 Stoneridge Drive, Suite 504
Pleasanton, CA 94588Phone: (510) 273-8585
Email: nochi@sksmgmt.com
Website(s): www.SKSMGMT.com
OWNER/PRESIDENT: Natolie Ochi
Contact: Mari Chang-Pepito
Founded: 1998
Number of Facilities: 32
Total net rentable square footage: 2,627,743
Expansion plans: The company will be adding more third-party managed locations to its portfolio. It will be offering maintenance database implementation/management and property condition reports to other operators. -
1175 Peachtree Street NE, Suite 1600
Atlanta, GA 30361Email: info@safstor.com
Website(s): www.safstor.com
OWNER/PRESIDENT: Andrew Young
Founded: 2017
Number of Facilities: 33
Total net rentable square footage: 2,588,184
Number of Facilities in Development: 22
Expansion plans: The company will continue to build its portfolio of facilities throughout the U.S. -
4225 W. 62nd Street
Indianapolis, IN 46268Phone: (801) 652-3134
Email: dwalker@storageofamerica.com
Website(s): www.storageofamerica.com
OWNER/PRESIDENT: Robert Walker
Contact: Derek Walker
Founded: 2003
Number of Facilities: 33
Total net rentable square footage: 2,517,489
Number of Facilities in Development: 16
Expansion plans: The company will be permitting and building out as much of its pipeline as possible. -
5607 Glenridge Drive
Atlanta, GA 30342Phone: (404) 788-7921
Email: jeff@steininvest.com
Website(s): www.steininvest.com
OWNER/PRESIDENT: Jeff Stein
Founded: 2009
Number of Facilities: 33
Total net rentable square footage: 2,500,000
Number of Facilities in Development: 5
Expansion plans: Stein Investment Group will continue to find acquisition and expansion oppourtinities over the next 12 months..
-
5111 S. Ridgewood Avenue
Port Orange, FL 32127Phone: (386) 299-3217
Email: eclark@goallaboard.com
Website(s): www.allaboardstorage.com
OWNER/PRESIDENT: Andy Clark
Contact: marketing@goallaboard.com
Founded: 1983
Number of Facilities: 30
Total net rentable square footage: 2,379,360
Expansion plans: The company is expanding four of its owned locations by adding additional buildings. -
11560 Tennessee Avenue
Los Angeles, CA 90064Phone: (310) 914-4022
Email: claire@aamericanselfstorage.com
Website(s): www.aamericanselfstorage.com
OWNER/PRESIDENT: Claire Shamsid-Deen, Josh Paterson, and Madelline Quijano
Contact: Claire Shamsid-Deen
Founded: 1973
Number of Facilities: 28
Total net rentable square footage: 2,374,111
Expansion plans: A-American Self Storage plans to continue to add properties to its third-party management portfolio. -
599B Steed Road
Ridgeland, MS 39157Phone: (601) 977-0733
Email: nick@stomax.com
Website(s): www.stomax.com
OWNER/PRESIDENT: Robert Lloyd
Contact: Nick Newcomb
Founded: 1993
Number of Facilities: 40
Total net rentable square footage: 2,344,869
Number of Facilities in Development: 1
Expansion plans: The company plans to continue to expand through acquisitions and development throughout the Southeast. -
74 Halbach Court
Fond du Lac, WI 54937Phone: (920) 267-6210
Email: steve@superiorstorage.com
Website(s): www.superiorstorage.com
OWNER/PRESIDENT: Steve Juiris
Contact: Steve Juiris
Founded: 2014
Number of Facilities: 31
Total net rentable square footage: 2,190,691
Expansion plans: The company plans to acquire facilities when strategic opportunities present themselves. -
3340 Monroe Avenue
Rochester, NY 14618Phone: (888) 786-6255
Email: CustomerService@TheStorageMall.com
Website(s): www.TSMMG.com
OWNER/PRESIDENT: Patrick Bailey
Contact: Brittany Bouvy
Founded: 2021
Number of Facilities: 53
Total net rentable square footage: 2,167,446
Expansion plans: The company will continue to expand its portfolio through purchases and onboards. -
6801 Jefferson Street NE, 401-B
Albuquerque, NM 87109Phone: (505) 415-0666
Email: jefferson@dxd.capital
Website(s): www.dxd.capital
OWNER/PRESIDENT: Drew Dolan and Cory Sylvester
Contact: Jefferson King
Founded: 2020
Number of Facilities: 33
Total net rentable square footage: 2,068,755
Number of Facilities in Development: 20
Expansion plans: The company has 12 land/deal closings expected for approximately $203.8 million in combined project cost. It has 10 new construction starts expected in the next 12 months, with approximately 7,438 total units breaking ground. It has five new facilities transitioning from construction into lease-up and five that have broken ground and will open in 2027 (Coleman, Carrollton, Cantera, Richmond, Snohomish) totaling approximately 4,470 units. -
21800 Burbank Boulevard, Suite 350
Woodland Hills, CA 91367Phone: (424) 205-5000
Email: tpayne@justselfstorage.com
Website(s): www.justselfstorage.com
OWNER/PRESIDENT: Dale Payne
Contact: Teddy Payne
Founded: 2024
Number of Facilities: 22
Total net rentable square footage: 1,936,405 -
1001 Avenida Pico, Suite C-611
San Clemente, CA 92673Phone: (717) 777-2015
Email: evan@tntmgmt.com
Website(s): www.tntselfstorage.com
OWNER/PRESIDENT: Dianne Tanna
Contact: Evan Tanna
Founded: 1997
Number of Facilities: 21
Total net rentable square footage: 1,847,687
Number of Facilities in Development: 1
Expansion plans: TNT Self Storage Management, a Southern California–focused management company built on decades of hands-on operating experience, plans to expand its portfolio by continuing to combine institutional-level performance and accountability with the accessibility, attention, and ownership mentality of a family-run organization. TNT treats every property entrusted to them as if their own name and capital were attached to it, driving revenue, protecting the asset, developing great teams, and building long-term value for the owners who trust them with their investments. -
12375 W. Sample Road
Coral Springs, FL 33065Phone: (954) 228-4611
Email: smclaughlin@sentry-selfstorage.com
Website(s): www.sentry-selfstorage.com
OWNER/PRESIDENT: Norman Schulman
Contact: Scott McLaughlin
Founded: 1998
Number of Facilities: 26
Total net rentable square footage: 1,838,842
Number of Facilities in Development: 1
Expansion plans: The company will continue to acquire and develop new sites and seek additional third-party management contracts throughout the United States. -
3001 Lava Ridge Court, Suite 130
Roseville, CA 95661Phone: (916) 481-2600
Email: jordan@cpinc.us
Website(s): www.shieldstorage.com
OWNER/PRESIDENT: Greg Drennan, Kenny Pratt, and Jordan Mills
Contact: jordan@cpinc.us
Founded: 2003
Number of Facilities: 32
Total net rentable square footage: 1,803,394
Expansion plans: The company is expanding in the Western U.S. primarily via acquisitions.
-
1639 Bradley Park Drive, Suite 500 PMB 281
Columbus, GA 31904Phone: (706) 452-5667
Email: will@artisanpropertiesinc.com
Website(s): www.artisanpropertiesinc.com
OWNER/PRESIDENT: Fred Rickman
Contact: Will Potts
Founded: 1995
Number of Facilities: 23
Total net rentable square footage: 1,750,000
Expansion plans: The company has planned expansion of its management company. It began managing The Mini Storage Center in the Carolinas. -
11820 Miramar Parkway
Miramar, FL 33025Phone: (954) 594-1225
Email: michael@nationalbusinessmanagement.com
Website(s): www.nationalbusinessmanagement.com
OWNER/PRESIDENT: Michael Cabak
Founded: 2014
Number of Facilities: 18
Total net rentable square footage: 1,680,085
Number of Facilities in Development: 3 -
208 Gates Road
Little Ferry, NJ 07643Phone: (201) 204-4987
Email: arockoff@access-store.com
Website(s): www.accessselfstorage.com
OWNER/PRESIDENT: Foy Cooley
Contact: Andrew Rockoff
Founded: 1976
Number of Facilities: 23
Total net rentable square footage: 1,669,374
Number of Facilities in Development: 3
Expansion plans: The company plans to add three to five new construction and five-plus new third-party management locations to its portfolio. -
4533 Rancho Blanca Court
Fort Worth, TX 76108Phone: (817) 456-4658
Email: info@donaldjonesconsulting.com
Website(s): www.donaldjonesconsulting.com
OWNER/PRESIDENT: Donald Jones
Contact: Emily Maxifled
Founded: 2004
Number of Facilities: 35
Total net rentable square footage: 1,634,931
Expansion plans: The company will expand its managing services to additional states and assist owners with development and restructuring. -
1601 Eastman Avenue, #101
Ventura, CA 93003Phone: (805) 642-4773
Email: ellen@epicgroup.us
Website(s): www.getepicstorage.com
OWNER/PRESIDENT: William Kendall
Contact: ellen@epicgroup.us
Founded: 1985
Number of Facilities: 17
Total net rentable square footage: 1,608,977
Number of Facilities in Development: 1
Expansion plans: The company is currently building one new facility in 2026 (approximately 120,000 square feet) in Ventura County, Calif. -
1447 Peachtree Street, Suite 470
Atlanta, GA 30309Phone: (678) 701-9305
Email: neil@nitneilpartners.com
Website(s): www.nitneilpartners.com
OWNER/PRESIDENT: Neil Sapra and Nitesh Sapra
Contact: Nitesh Sapra
Founded: 1985
Number of Facilities: 22
Total net rentable square footage: 1,600,020
Number of Facilities in Development: 6
Expansion plans: The company plans to execute on a pipeline of six new deals of approximately 450,000 net rentable square feet in North Carolina, Texas, Georgia, Virginia, and D.C. -
5301 Dempster Street, Suite 300
Skokie, IL 60077Phone: (847) 732-6819
Email: tbretz@elmdalepartners.com
Website(s): www.storsafe.com
OWNER/PRESIDENT: Tom Bretz
Contact: Tom Bretz
Founded: 2016
Number of Facilities: 32
Total net rentable square footage: 1,565,180
Expansion plans: StorSafe Self Storage Management will be expanding in the Midwest. -
10230 NE Points Drive, Suite 410
Kirkland, WA 98033Phone: (206) 464-5252
Email: RogerW@mgnco.com
Website(s): www.nwbld.com
OWNER/PRESIDENT: Privately Held
Founded: 1979
Number of Facilities: 25
Total net rentable square footage: 1,564,160
Number of Facilities in Development: 2
Expansion plans: The company will open two new facilities and start construction on four more. -
328 Barry Avenue South, Suite 300 / 4541 Bellaire Drive South, Suite 100
Wayzata, MN 55391 / Fort Worth, TX 76109Phone: (952) 767-2500 / (817) 735-9996
Email: info@nolanpg.com / info@ezmini.com
Website(s): www.ezstoragenow.com / www.ezmini.com
OWNER/PRESIDENT: John A. Nolan / William J. Nolan, Jr.
Contact: John A. Nolan
Founded: 1971
Number of Facilities: 20
Total net rentable square footage: 1,563,928
Expansion plans: The company has ongoing, selective interest in acquisitions and new development. -
11750 Stonegate Circle
Omaha, NE 68164Phone: (402) 334-2123
Email: jake@mcgregorint.com
Website(s): www.mcgregorint.com
OWNER/PRESIDENT: Geoff McGregor
Contact: Jake Hillwick
Founded: 1982
Number of Facilities: 23
Total net rentable square footage: 1,537,000
Number of Facilities in Development: 1
Expansion plans: McGregor Interests Inc is committed to growth with planned acquisitions, expansions already underway, and more third-party-managed properties in negotiation.
-
275 1st Avenue South, Suite 2005
St. Petersburg, FL 33701Phone: (727) 224-9540
Email: SynergyStorage@aol.com
Website(s): www.store-it.com
OWNER/PRESIDENT: Jim Gail
Contact: Kelsey Wells
Founded: 1991
Number of Facilities: 24
Total net rentable square footage: 1,483,724
Number of Facilities in Development: 1
Expansion plans: Synergy Storage Group will complete development of one facility in Florida. It’s looking for select management and ownership opportunities in its existing markets. -
7 Columbia Turnpike
Florham Park, NJ 07932Phone: (862) 227-2010
Email: randall@columbiastoragegroup.com
Website(s): www.columbiaselfstorage.com
OWNER/PRESIDENT: Randall P. Mosca
Contact: Randall Mosca, Jr.
Founded: 2012
Number of Facilities: 29
Total net rentable square footage: 1,427,083
Expansion plans: The company is looking to expand throughout the Northeast as well as Arizona. -
8810 Cuyamaca Street
Santee, CA 92071Phone: (760) 401-0297
Email: sue@havilandstorageservices.com
Website(s): www.havilandstorageservices.com
OWNER/PRESIDENT: Susan Haviland
Contact: Kylie Smith
Founded: 2009
Number of Facilities: 13
Total net rentable square footage: 1,409,540 -
7777 W. Deer Valley Road
Peoria, AZ 85382Phone: (602) 997-9690
Email: storagelady@coxarmored.com
Website(s): www.armored-mini-storage.com
OWNER/PRESIDENT: Diane M. Gibson
Contact: Diane Gibson
Founded: 1995
Number of Facilities: 16
Total net rentable square footage: 1,316,631
Expansion plans: The company is bringing on three to four more properties to manage. -
180 2nd Street
Los Altos, CA 94022Phone: (425) 922-6009
Email: tkokernak@storagecorner.com
Website(s): www.storagecornergroup.com
OWNER/PRESIDENT: Theodore Kokernak
Contact: Ben Wagstaff, partner (bwagstaff@storagecorner.com)
Founded: 2015
Number of Facilities: 24
Total net rentable square footage: 1,290,000
Expansion plans: The company plans to acquire four to five new value-add self-storage properties in SCG’s existing target markets and execute on a few expansion opportunities among owned stores. -
1308 E. Jasmine Avenue
McAllen, TX 78501Phone: (956) 213-8244
Email: matt@verturo.com
Website(s): www.justacloset.com
OWNER/PRESIDENT: Joey Holand
Contact: Danny Mederos
Founded: 2019
Number of Facilities: 13
Total net rentable square footage: 1,270,396
Number of Facilities in Development: 6
Expansion plans: JAC is continuing to execute an active and disciplined growth strategy, with six additional facilities currently in the development pipeline. Over the next 12 months, the company will focus on advancing these projects while continuing to strengthen the performance of its existing portfolio. Beginning in 2027, JAC plans to expand beyond Texas, selectively entering markets that align with the company’s development criteria and operating model. The company’s long-term objective is to grow the portfolio to approximately 30 facilities by 2032. JAC’s vertically integrated platform provides control across the full development and operating lifecycle, allowing the company to capture economics at multiple stages, maintain greater control over execution, and maximize long-term investor value. -
PO Box 1176
Sorrento, FL 32776Phone: (407) 783-6294
Email: csr@peopleschoicestorage.com
Website(s): www.peopleschoicestorage.com
OWNER/PRESIDENT: Scott Dahin
Contact: scott@tricoreig.com
Founded: 2019
Number of Facilities: 20
Total net rentable square footage: 1,263,413
Number of Facilities in Development: 1
Expansion plans: Peoples Choice Storage plans to hold and recapitalize. -
7577 Central Park Boulevard, Suite 205
Mason, OH 45040Phone: (678) 491-7984
Email: Brad@AcmStorage.com
Website(s): www.AcmStorage.com
OWNER/PRESIDENT: Brad North
Contact: Brad North
Founded: 2002
Number of Facilities: 17
Total net rentable square footage: 1,210,000 -
5388 Ronald Reagan Boulevard, Suite 136
Johnstown, CO 80534Phone: (720) 506-9432
Email: Info@upliftselfstorage.com
Website(s): www.upliftselfstorage.com/uplift-real-estate-services
OWNER/PRESIDENT: Brandon Grebe
Contact: Dan Fischer
Founded: 2024
Number of Facilities: 29
Total net rentable square footage: 1,204,207
Expansion plans: The company is adding an additional 10 properties by the end of next year. -
1820 W. Orangewood Avenue, Suite 203
Orange, CA 92868Phone: (657) 224-9444
Email: rrogers@storehere.com
Website(s): www.storehere.com
OWNER/PRESIDENT: Ryan T. Rogers
Contact: Ryan Rogers
Founded: 2012
Number of Facilities: 16
Total net rentable square footage: 1,136,015 -
2221 Victory Lane
Hoover, AL 35216Phone: (205) 989-8660
Email: jlebon@pankeyproperties.com
Website(s): www.pankeyproperties.com
OWNER/PRESIDENT: Paul M. Pankey, Jr.
Founded: 2002
Number of Facilities: 16
Total net rentable square footage: 1,056,134
Number of Facilities in Development: 1
Expansion plans: The company plans to expand its portfolio through office buildings with storage.
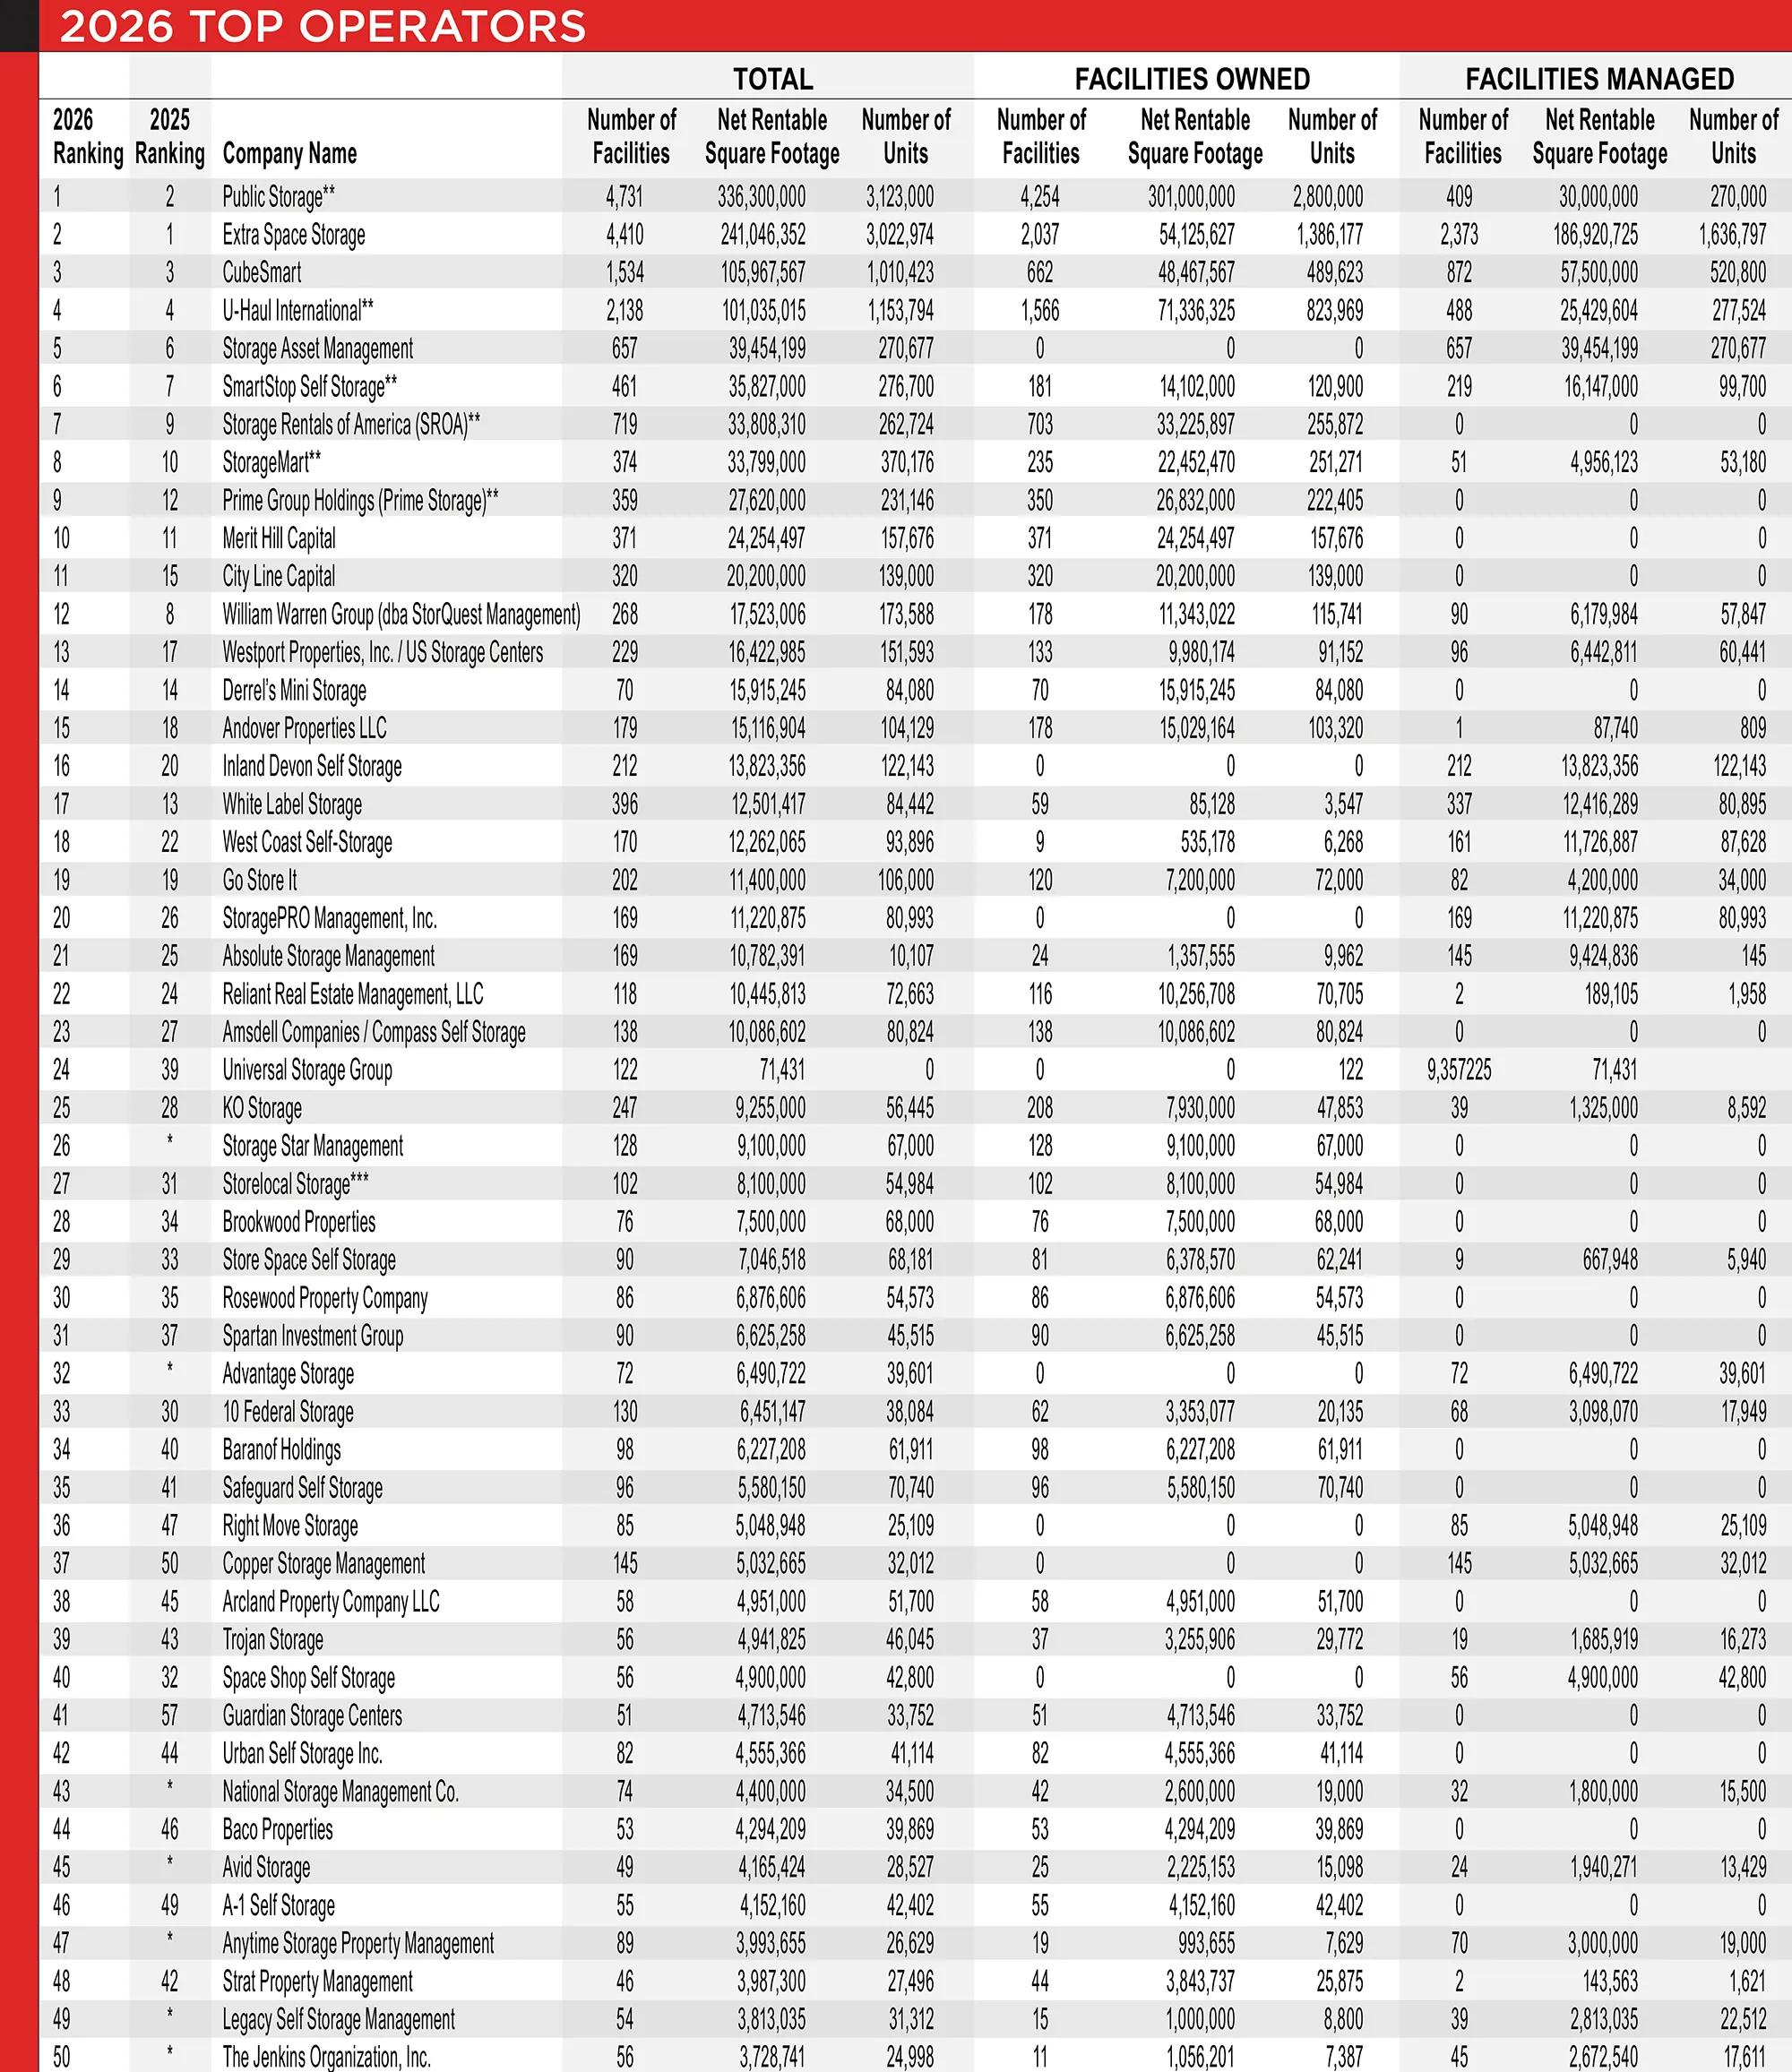
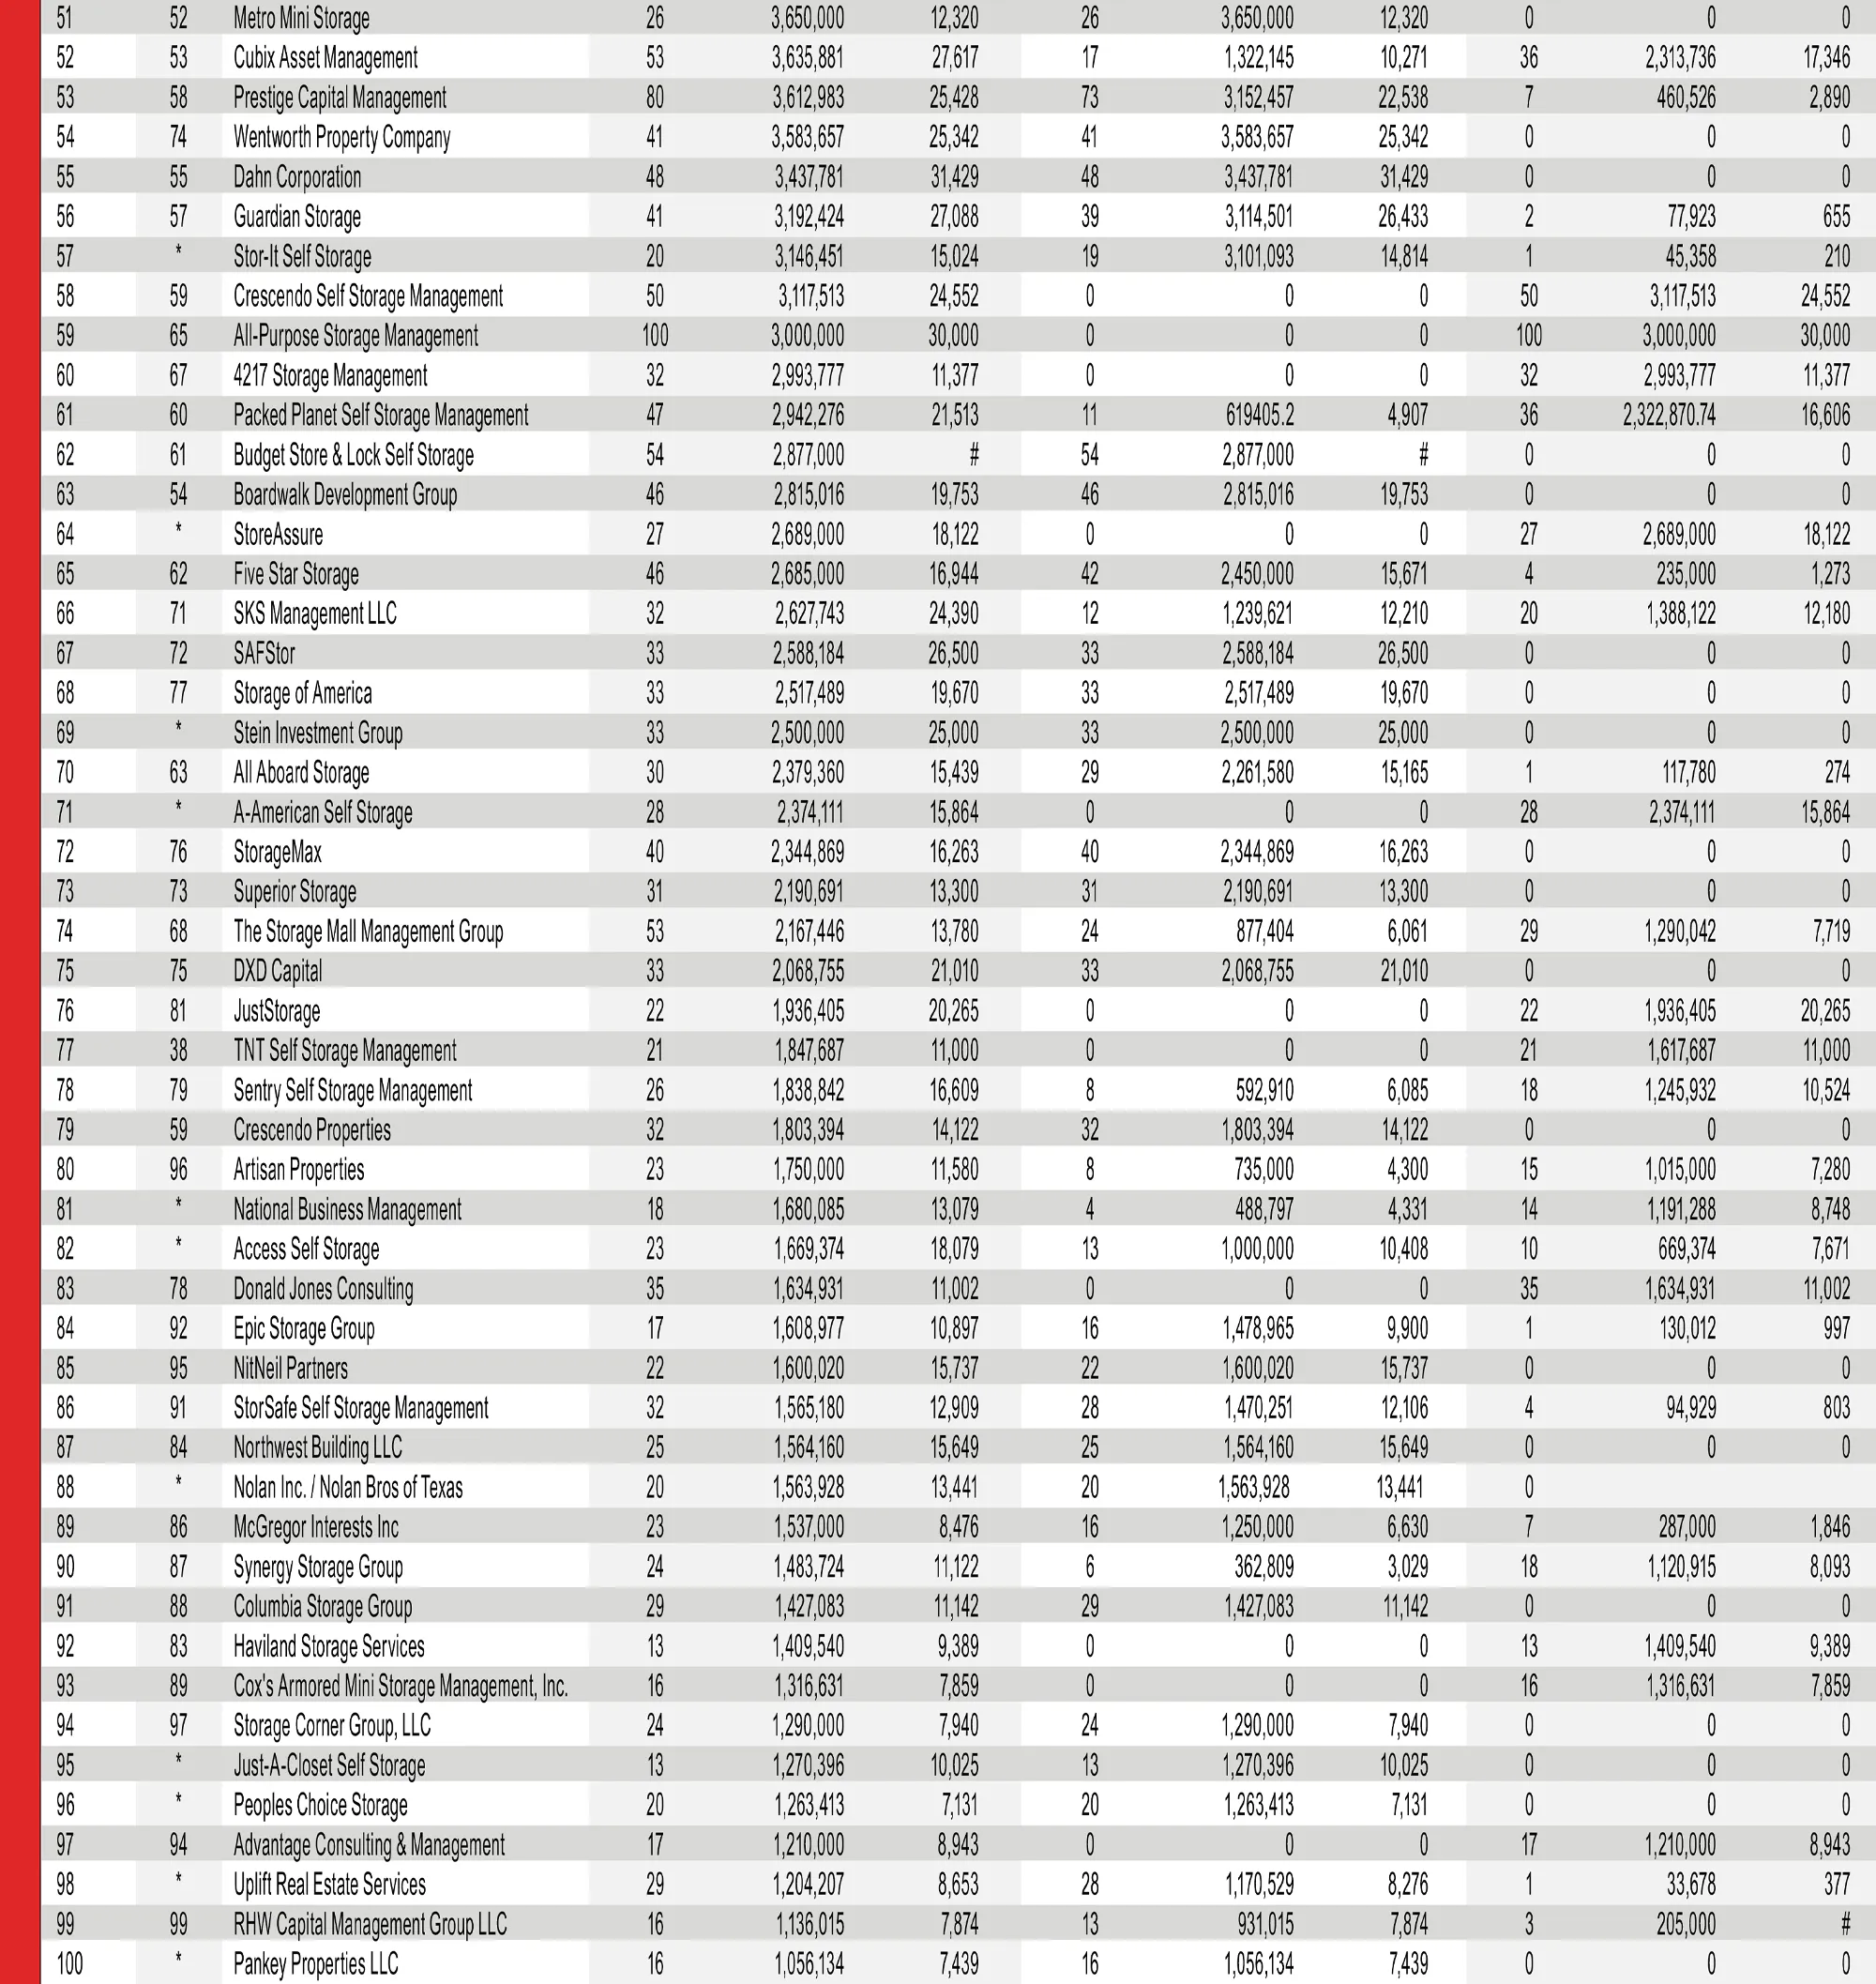

DESIGN-BUILD EXPERTS
NATIONWIDE
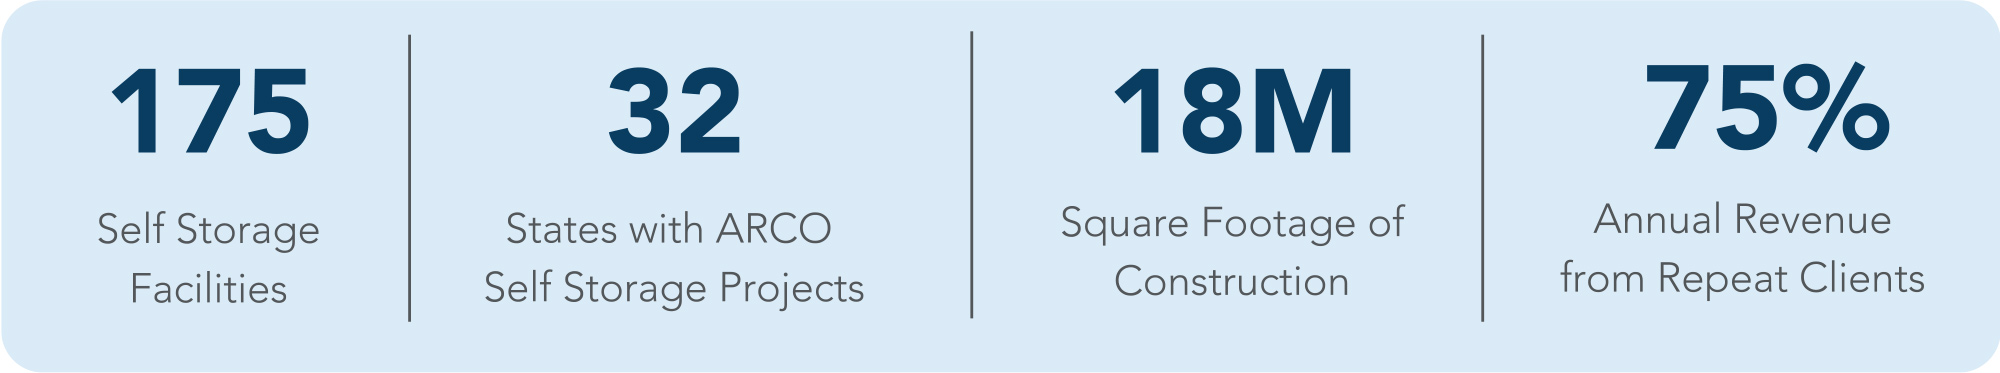
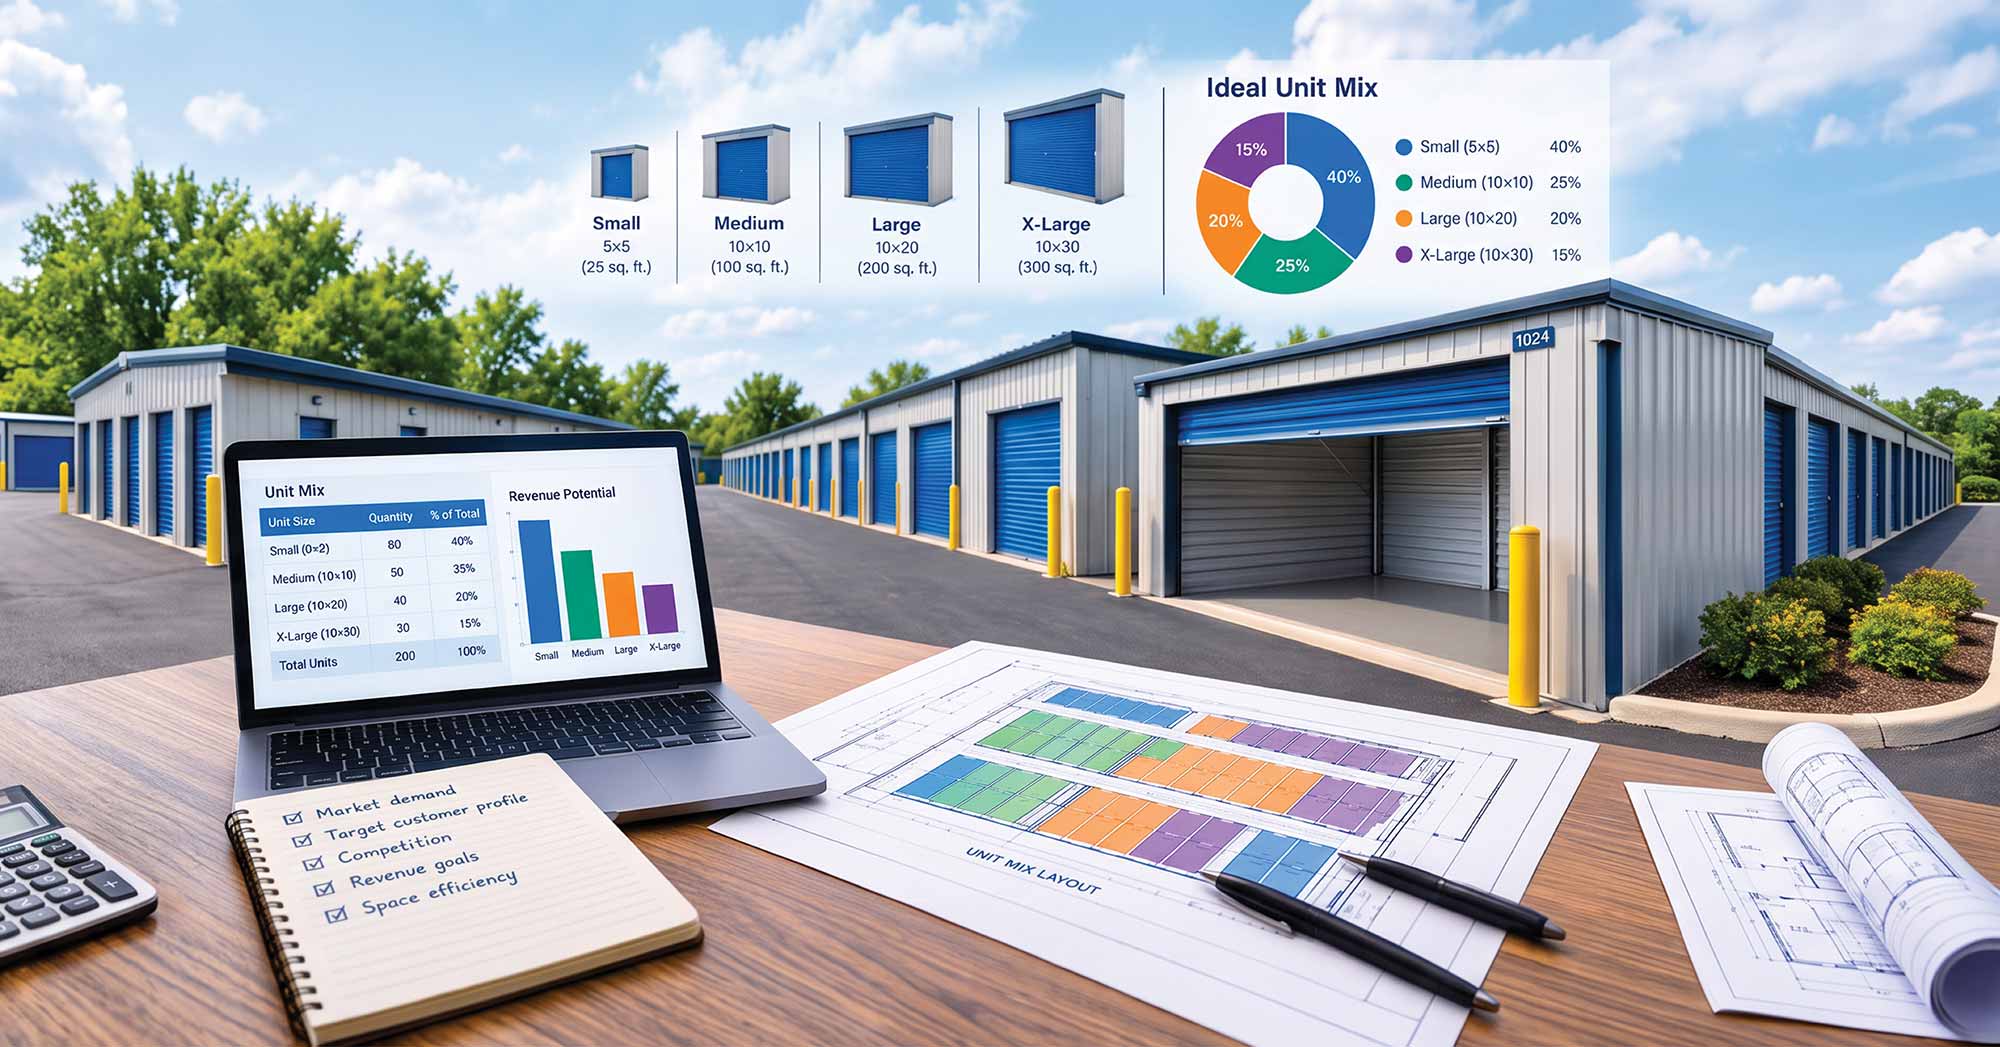
f your property has the wrong mix of storage units, you’re leaving money on the table. Too many large units can sit empty for months. Too few smaller units can cause you to miss steady demand from renters who want affordable space. When your unit mix doesn’t match your market, profitability suffers.
StorSuite’s strong third-party management team can make a real difference. They can help you build a smarter unit mix strategy based on local demand, pricing opportunities, and long-term revenue goals.
Instead of guessing what renters want, StorSuite uses data, expert insight, and forecasting to shape a property that performs better. The right unit mix doesn’t just fill units. It supports higher occupancy, stronger growth, and more dependable cash flow.
When your mix isn’t working, you can run into the following problems:
- High vacancies in unit sizes with low demand,
- Missed rentals because your most requested sizes are always full,
- Lower average revenue per square foot,
- Increased discounting to fill slow-moving spaces, and
- Reduced flexibility as market demand changes.
A profitable unit mix helps you match supply to demand. That creates a better customer experience while improving revenue and operational efficiency.
- Market Study – A market study shows what renters in your area actually need. It looks at competition nearby, population trends, household density, new development, and local business activity. It identifies which unit sizes are most common and where supply gaps exist. This is critical because your property should reflect your local market, not a generic self-storage model.
- Expert Advice – Data is important, but experience matters too. An experienced third-party management team can interpret market conditions, identify revenue opportunities, and spot operational risks. For example, an expert may see that a market appears oversupplied in larger units but still has room for premium climate-controlled small units. That kind of insight can help design a profitable strategy.
- Forecasting – A good unit mix plan should not only fit today’s demand but should also account for future changes. Forecasting helps you prepare for shifts in renter behavior and expectations, seasonal demand, economic conditions, and new competition. With the right forecast, you can make the right decisions before it’s too late.
Consider the following trends when developing unit mix:
- Strong demand for smaller, lower-cost units;
- Continued interest in climate-controlled storage;
- Rising value of vehicle, RV, and boat storage in the right markets;
- More customer focus on convenience and access; and
- Greater need for flexibility in how space is used and priced.
These trends are not the same in every location. That is why third-party management is so valuable. A management team can track your market, compare your performance against local demand, and recommend adjustments that make financial sense.
- Focus on revenue per square foot. Not all units generate the same return. In many markets, smaller units can produce more revenue per square foot than larger ones. A profitable strategy looks beyond occupancy alone and considers which spaces are actually driving income.
- Balance demand and availability. If your most popular units are always full, you are either able to raise prices without losing customers or you could have a supply problem. If other sizes remain vacant, you may need to rework pricing, marketing, or future conversion plans.
- Build in flexibility. Markets change. Your unit mix strategy should leave room to adapt. That could include converting underperforming spaces, repositioning unit types, or adjusting pricing strategies to guide demand toward the most profitable sizes.
- Support premium offerings. Climate-controlled units, covered parking, and specialized storage can increase revenue only when they align with local demand. The goal is not to haphazardly add features but to offer premium space in areas where renters are willing to pay more.
- Reviewing occupancy and move-in trends by unit type,
- Monitoring competitor pricing and product mix,
- Adjusting rates based on demand patterns,
- Identifying underperforming inventory,
- Recommending operational and layout changes, and
- Forecasting future risks and growth opportunities.
You’ll stay ahead of market shifts instead of falling behind and be able to make better decisions about pricing, capital improvements, and long-term asset performance.
StorSuite’s third-party management team helps self-storage owners create unit mix strategies built for profitability. If your property isn’t producing the returns it should, it’s time to take a closer look.
Contact StorSuite to learn how our third-party management team can help you design and manage a more profitable unit mix strategy.
alk into a wet market in Bangkok, Shanghai, or Hanoi for the first time, and it’s complete chaos: the noise, the smell, bodies everywhere. Vendors shout prices. Produce is stacked in ways that defy logic. Nothing feels organized.
But then you spend time there. You start to see the patterns. There’s a language—spoken and unspoken—between vendor and customer. It’s body language—a handshake that means something, a nod that closes a deal. Wherever you turn, there’s something you’ve never experienced: a smell you can’t place, a texture you don’t recognize, a fruit you didn’t know existed. Underneath all that novelty, there’s consistency, rules, and logic. It all works. That’s organized chaos.
Asia’s self-storage market is exactly the same.
Most people talk about “Asia’s self-storage opportunity” as if it’s one thing—a single market, a single playbook. On the surface, it looks completely chaotic: eight markets, eight different rules, eight different customer bases, eight completely different economics. Nothing seems to fit together.
When you spend time in each market, you start to see it. There’s logic underneath. There are patterns and consistencies in how customers behave, how pricing works, and how occupancy stabilizes, but there are surprises everywhere you turn: a market where rents are USD 0.11 per square foot per month (USD 1.2 per square meter per month), another where they’re USD 8.7 per square foot per month (USD 93.6 per square meter per month). Unit sizes range from 10 square feet to 100 square feet and occupancy rates range from 63 percent to 93 percent.
The chaos is real, but it’s organized. Understanding that difference is everything.
What follows is a market-by-market breakdown—not a one-size-fits-all playbook but a guide to understanding the organized chaos underneath.
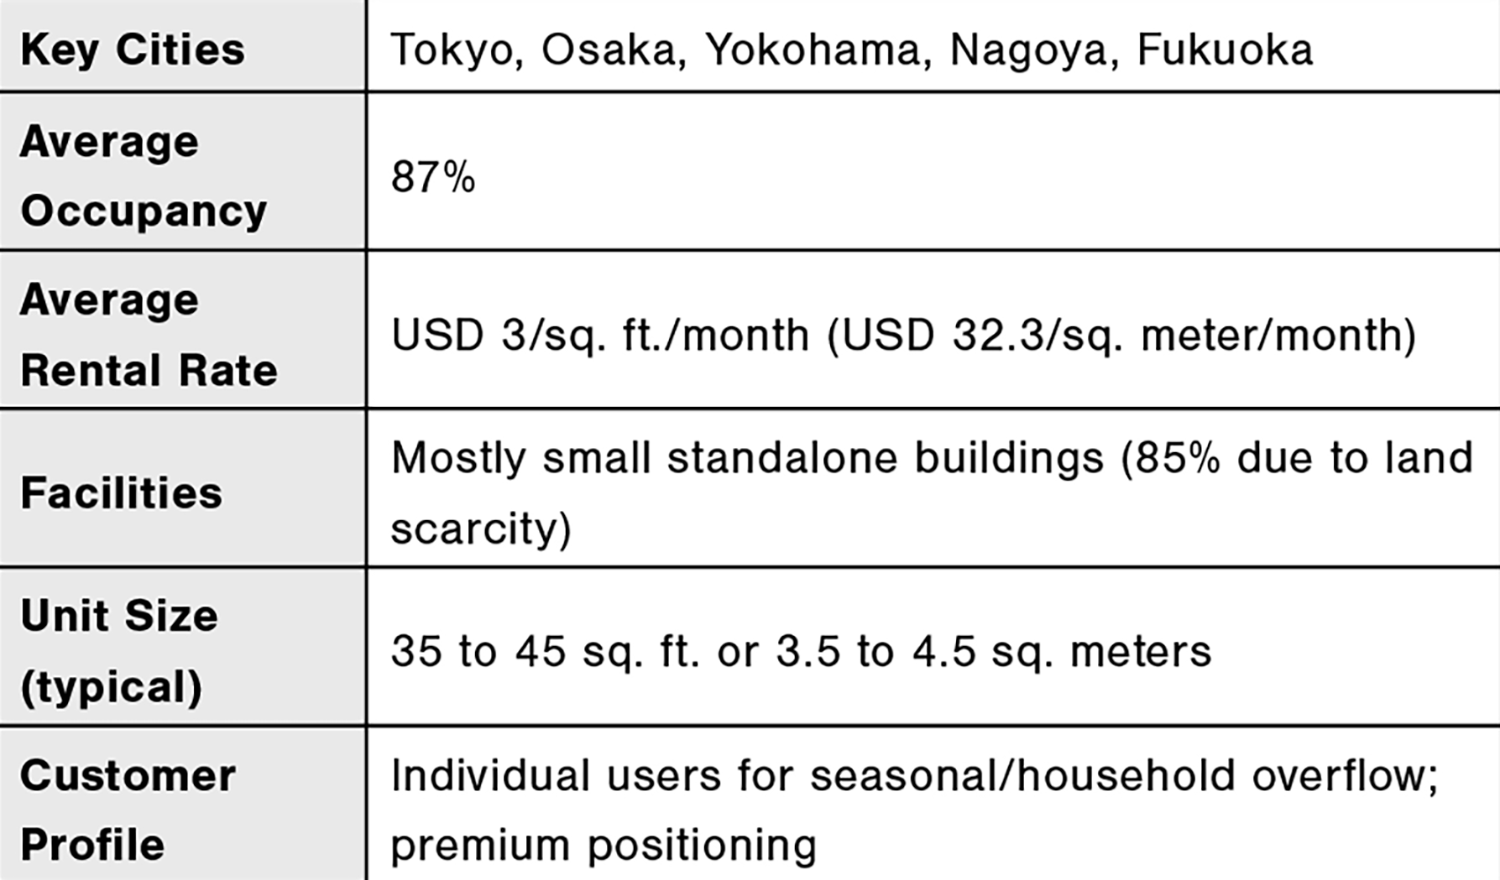
The unit economics are tighter than you’d expect. Small unit sizes (35 to 45 square feet) mean you’re playing a volume game, not a yield game. Climate control and indoor facilities are table stakes, not differentiators. Your customer is someone storing seasonal goods or household overflow, not a business looking for logistics space.
One key insight is that 90 percent of storage customers live within walking distance of their facility. In Japan, storage is not something you drive to—it is something you walk to. It functions as an extra room, an extension of the home. This is fundamentally different from most Western markets, where customers think nothing of a 20-minute drive to a suburban facility.
Key Recommendation: Build a local-language-first website (Japanese), then English. Partner with established operators or financial institutions. Solo foreign entry is difficult. Focus on digital integration, yield management, and portfolio consolidation.
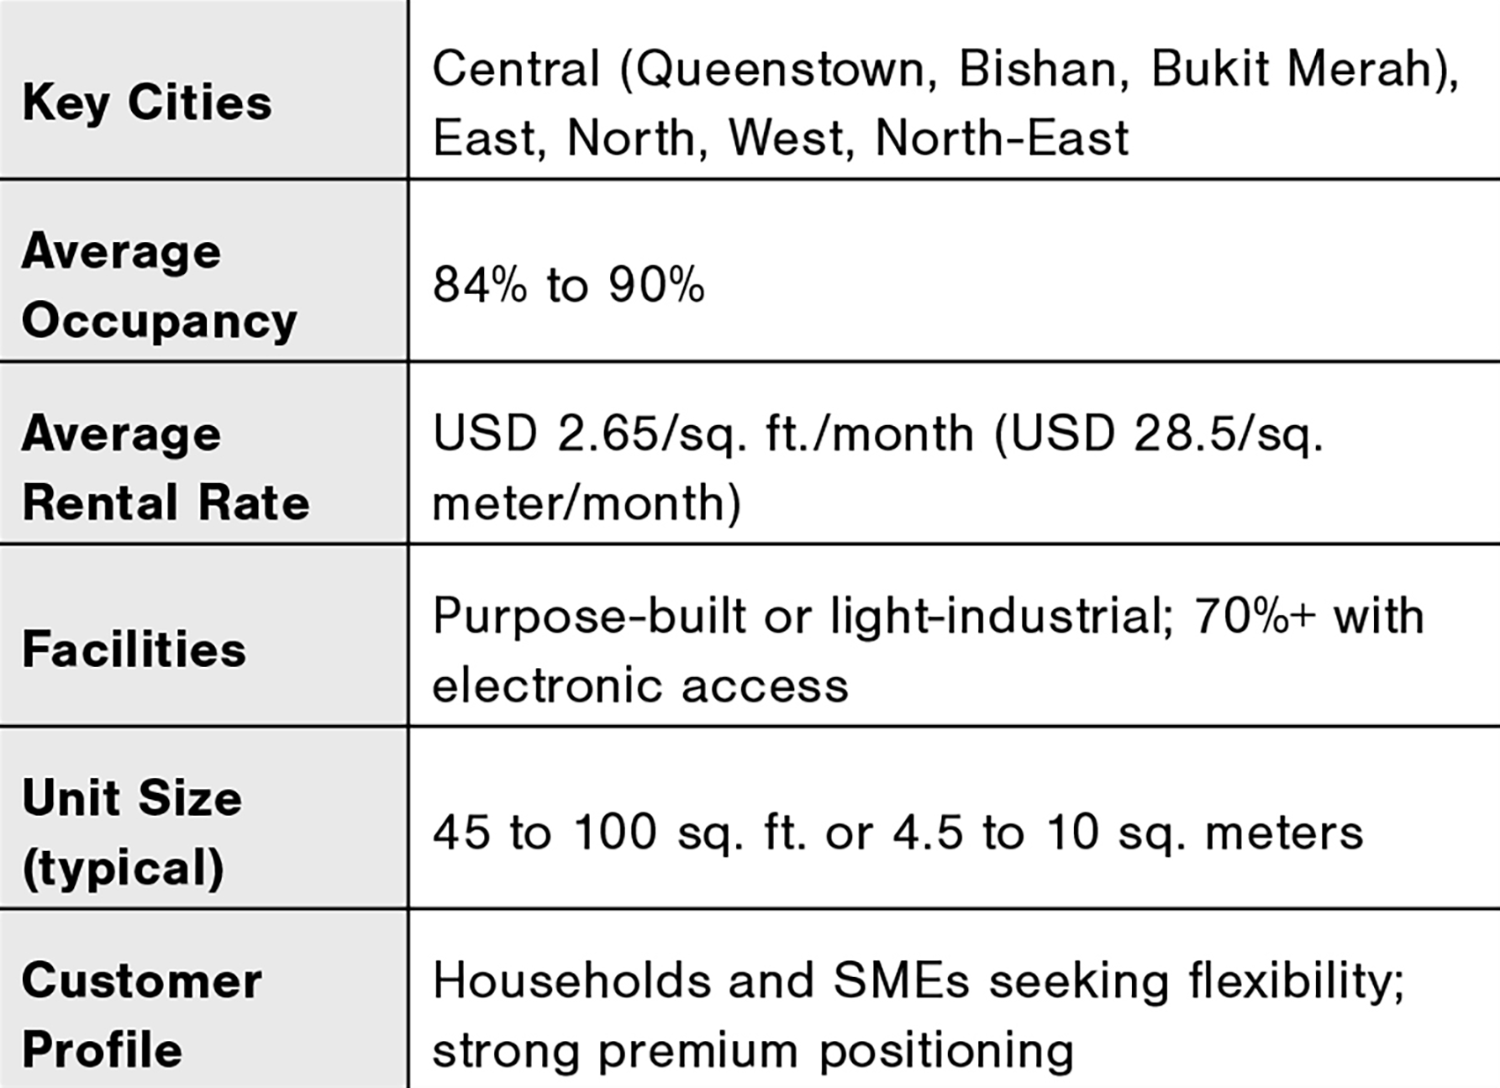
What makes Singapore different from Japan isn’t maturity—it’s diversity within maturity. Unit sizes are bigger (45 to 100 square feet). Customers include both households and SMEs. Digital access and technology enablement are table stakes, not emerging trends. The market rewards operational excellence and service differentiation, not price competition.
Central areas command premiums (SGD 7 to 9 per square foot or SGD 75 to 97 per square meter per month) because land scarcity is even more brutal than Japan. Eastern corridors stay affordable because they serve long-term residential tenants. It’s a tiered market, not a monolithic one, but the tiers follow clean logic.
Singapore shows you what happens when a small, dense market reaches full institutional maturity: no wild swings, no surprises, just steady, disciplined execution.
Key Recommendation: Build an English-first website. Emphasize digital-first experience and AI-driven pricing. The market rewards operational excellence and customer service. Compete on technology and service quality, not price.
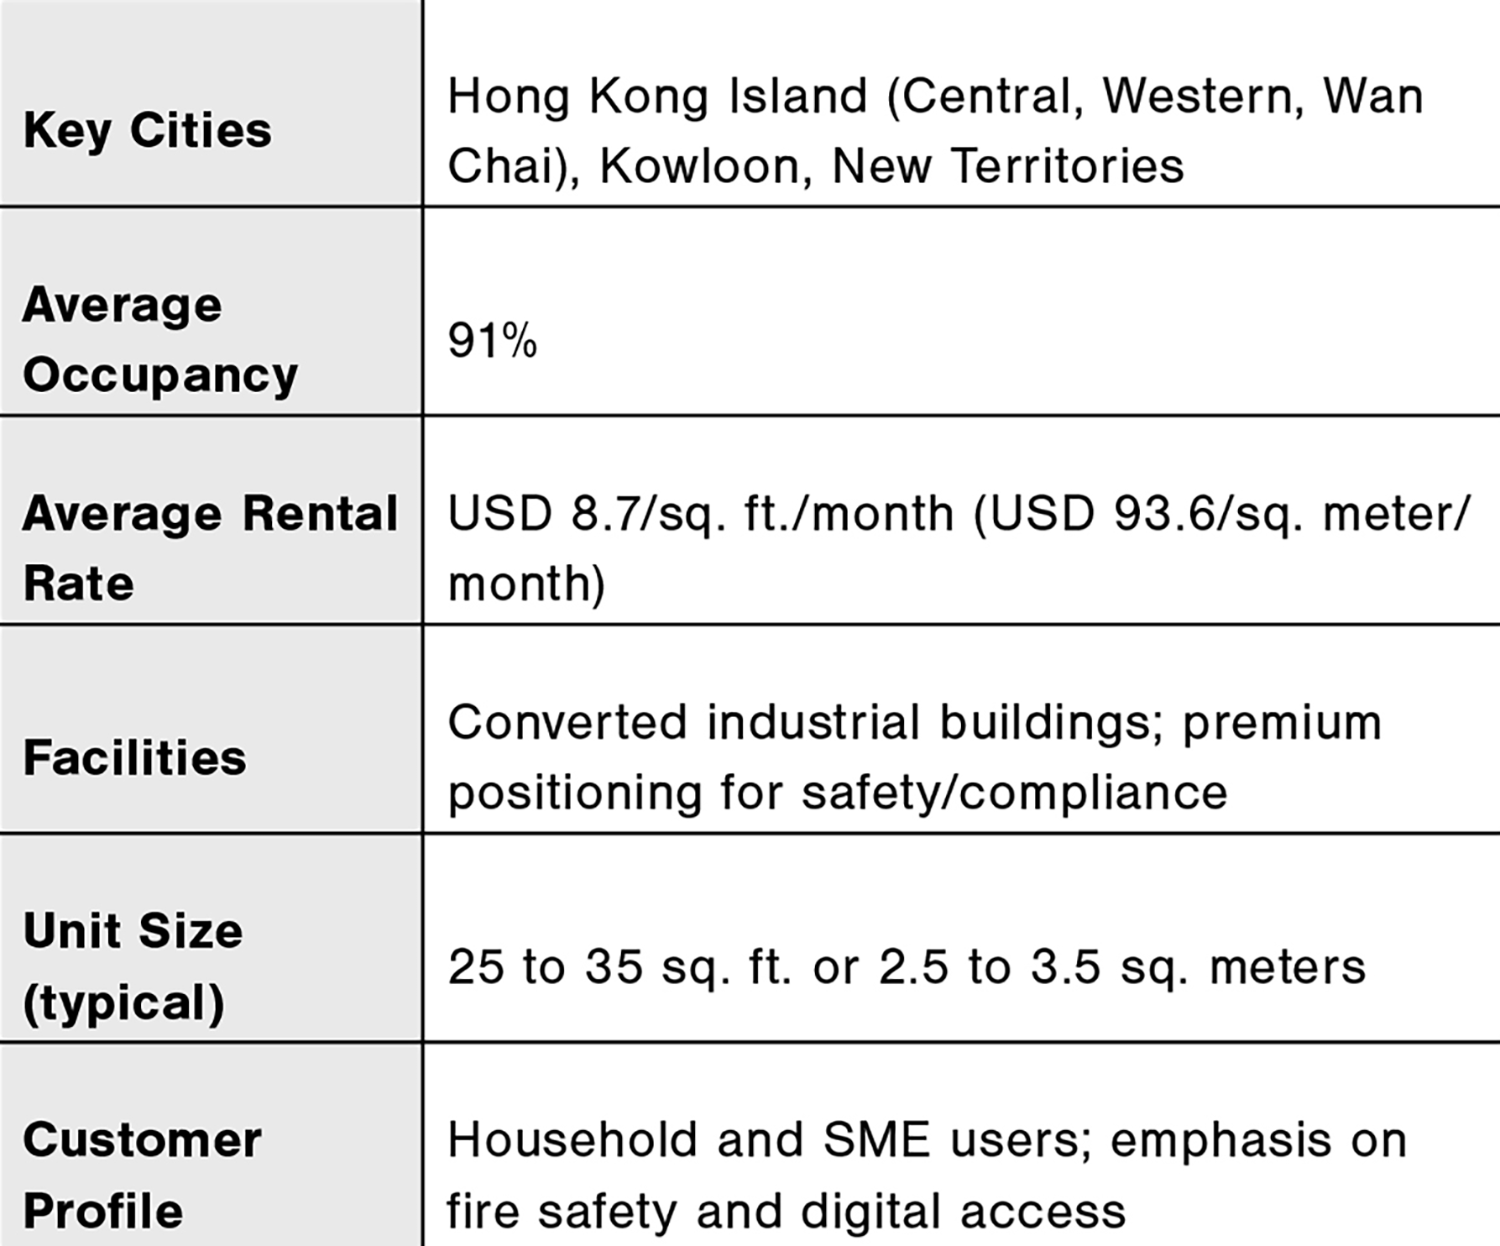
Density and scarcity are the reasons. The entire city is vertical, and every inch of ground is fighting for dollars. Unit sizes are tiny (25 to 35 square feet) because there’s literally nowhere else to put them. Your customer isn’t looking for value—they’re looking for space because they have nowhere else to go.
Regulatory tightness adds another layer. Fire safety and licensing compliance aren’t nice-to-haves; they’re existential. New territories offer cheaper units (HKD 50 to 60 per square foot or HKD 540 to 650 per square meter per month) because they’re further out, but even “affordable” Hong Kong storage is premium pricing by any other market’s standard.
Hong Kong shows you that maturity doesn’t mean stability. Scarcity can drive rents into another stratosphere entirely. And when land is this constrained, the economics stop following normal rules.
Key Recommendation: Build a local-language-first website (Cantonese with traditional Chinese), then simplified Chinese, then English. Focus on premium branding and compliance certifications. The market is saturated, so compete on service quality and location precision, not price. Regulatory excellence is your moat.
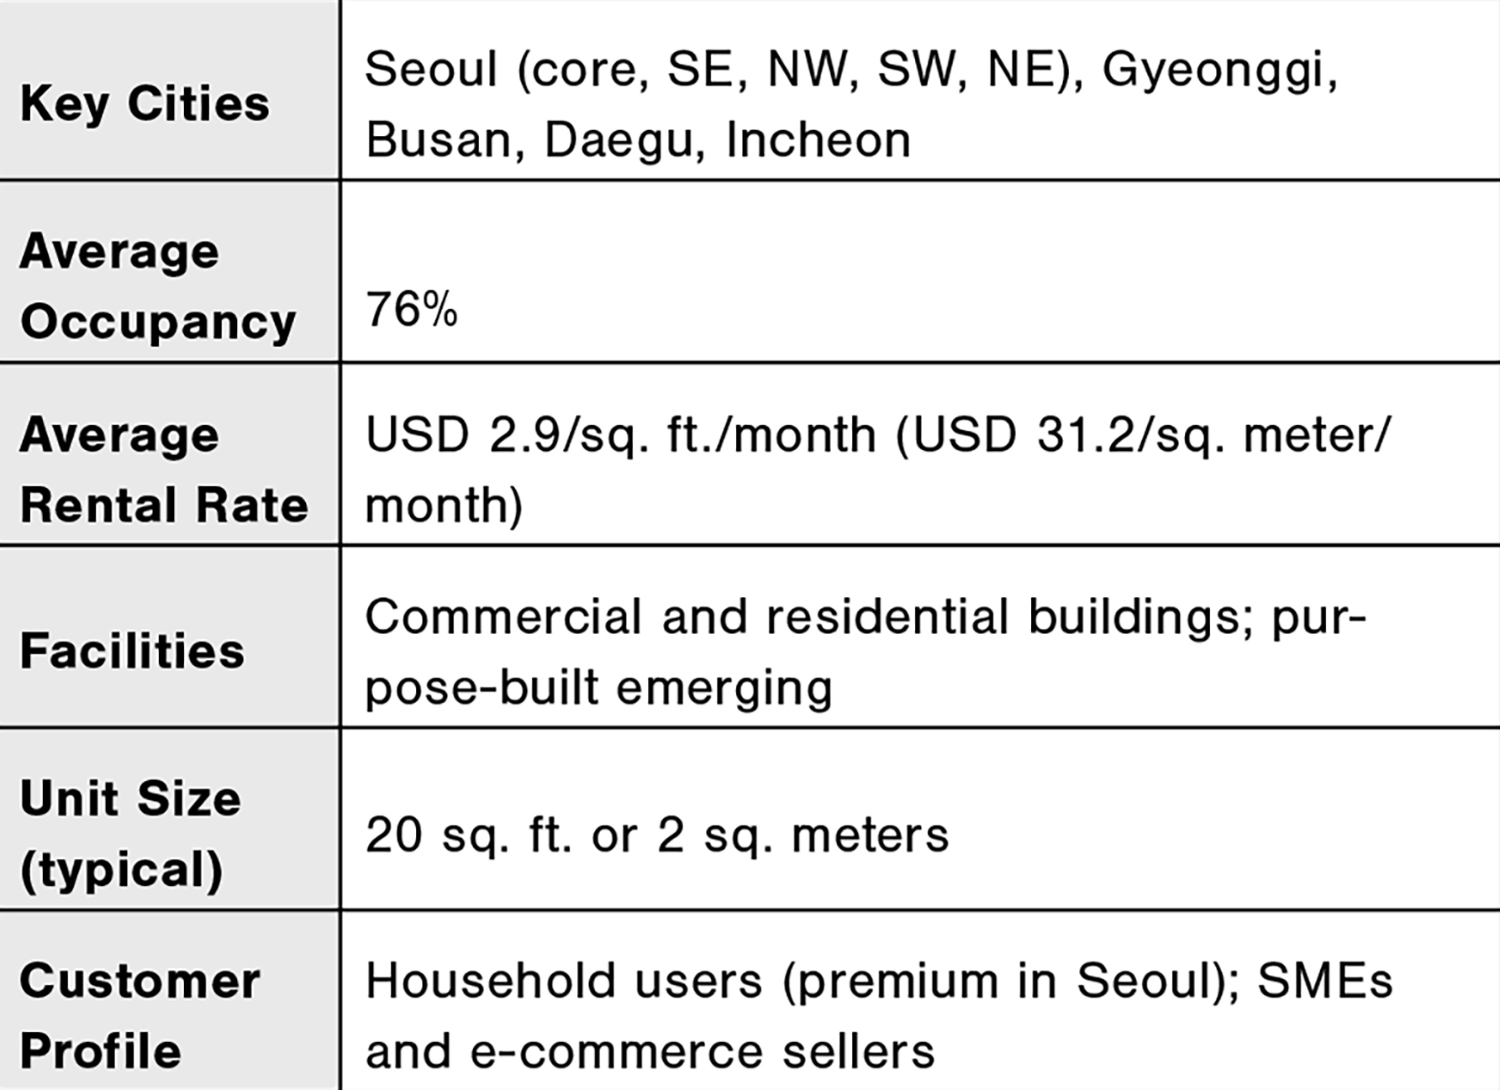
Unit sizes shrink to 10 to 30 square feet because space is at a premium but not as constrictive as Hong Kong. Seoul’s core districts demand premium rates; secondary hubs are more affordable. The market is stratified, and your position in the hierarchy matters enormously.
But here’s the crucial difference: Technology is the differentiator. Opt for AI-assisted pricing, automated booking systems, 24-hour digital access, and mobile-first platforms that let renters manage their units from their phones. In Japan and Singapore, technology is table stakes. In South Korea, technology is competitive advantage. That’s a fundamental shift.
Key Recommendation: Build a Korean-language-first website, then English. Tech stack is critical. Implement AI-assisted pricing, automated booking, and 24-hour access. The market rewards digital integration and operational efficiency. Operators who can’t match tech sophistication will lose share.
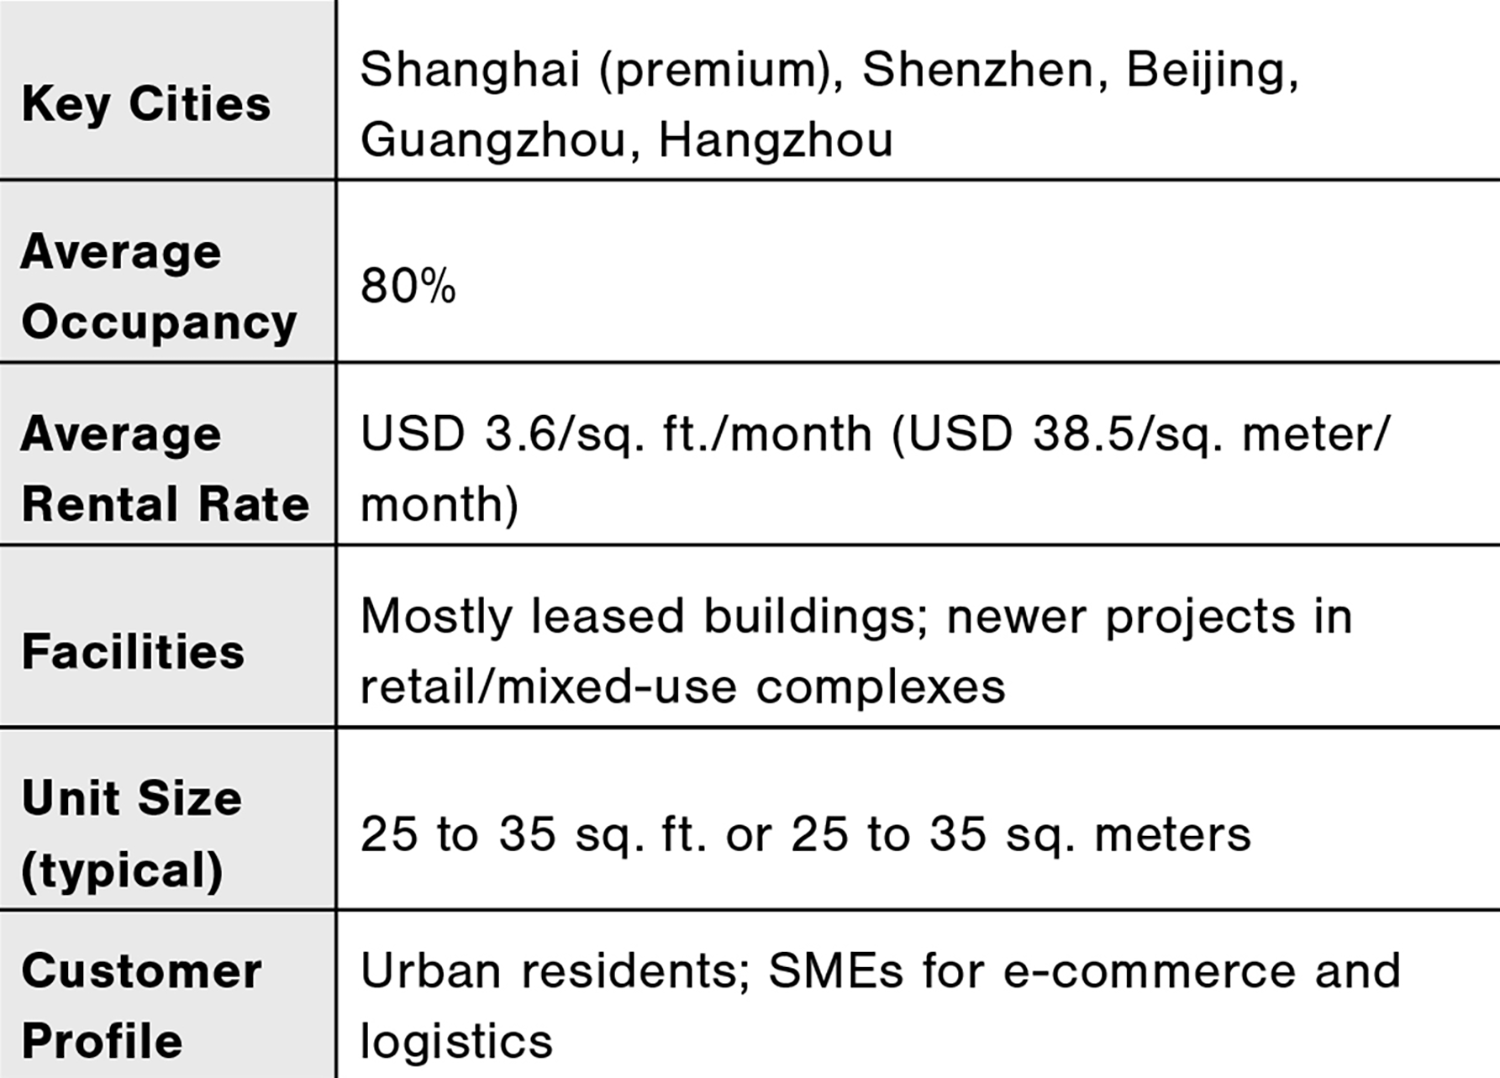
Most facilities operate through long-term leases in industrial buildings or increasingly within retail and mixed-use complexes, seeking visibility and customer accessibility. The sector is still fragmented—no single operator dominates—which means there’s room for consolidation and innovation. But there’s also room for disaster if you pick the wrong city or the wrong landlord.
China shows you what happens when a massive market is still figuring itself out. Occupancy is recovering and rents are stabilizing, but there are no guarantees. Regulatory risk exists. Supply can flood in overnight, but so can growth. It’s not for the faint of heart.
Key Recommendation: Build a Chinese-language-first website (Mandarin), then English. WeChat integration, Alipay/WeChat Pay, and mobile-first booking are essential; this is non-negotiable. Differentiate on digital transformation and cost efficiency. Local partnerships and regulatory relationships matter enormously.
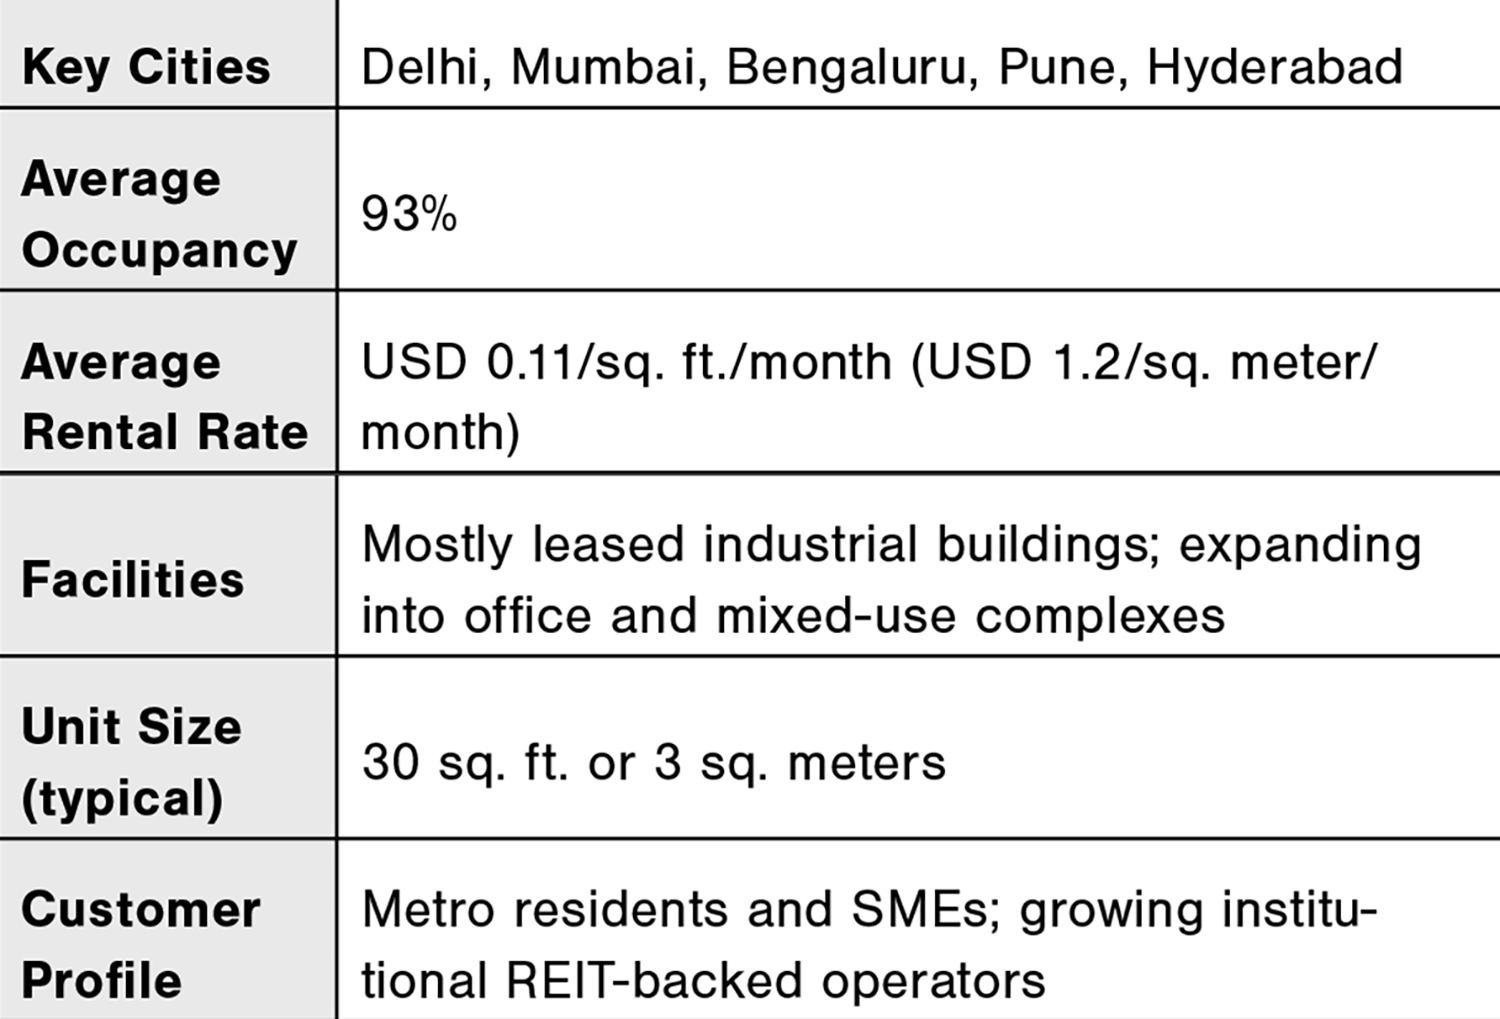
A basic 1-meter-by-1-meter-by-1-meter unit in Mumbai or Delhi costs less than USD 1.20 per month. That’s not a typo. For that price point, the customer base isn’t the affluent household—it’s small business owners, e-commerce sellers, and SMEs managing working capital with razor-thin margins.
The crucial difference: India’s market is being built by REIT-backed operators and institutional players who understand that professionalization drives adoption. It’s not organic customer discovery—it’s directed capital building a market from the top down. And the volumes required to make USD 1.20 unit economics work demand scale that only institutional capital can provide.
India shows you what happens when institutional capital meets an emerging market with minimal existing supply. High occupancy doesn’t mean maturity—it means opportunity and risk colliding at extraordinary speed.
Key Recommendation: Build an English-first website with regional language support (Hindi, Tamil, Telugu). REIT partnerships and institutional relationships are non-negotiable. Focus on scalable operations and asset optimization. The market is consolidating fast—be professional or get crowded out.
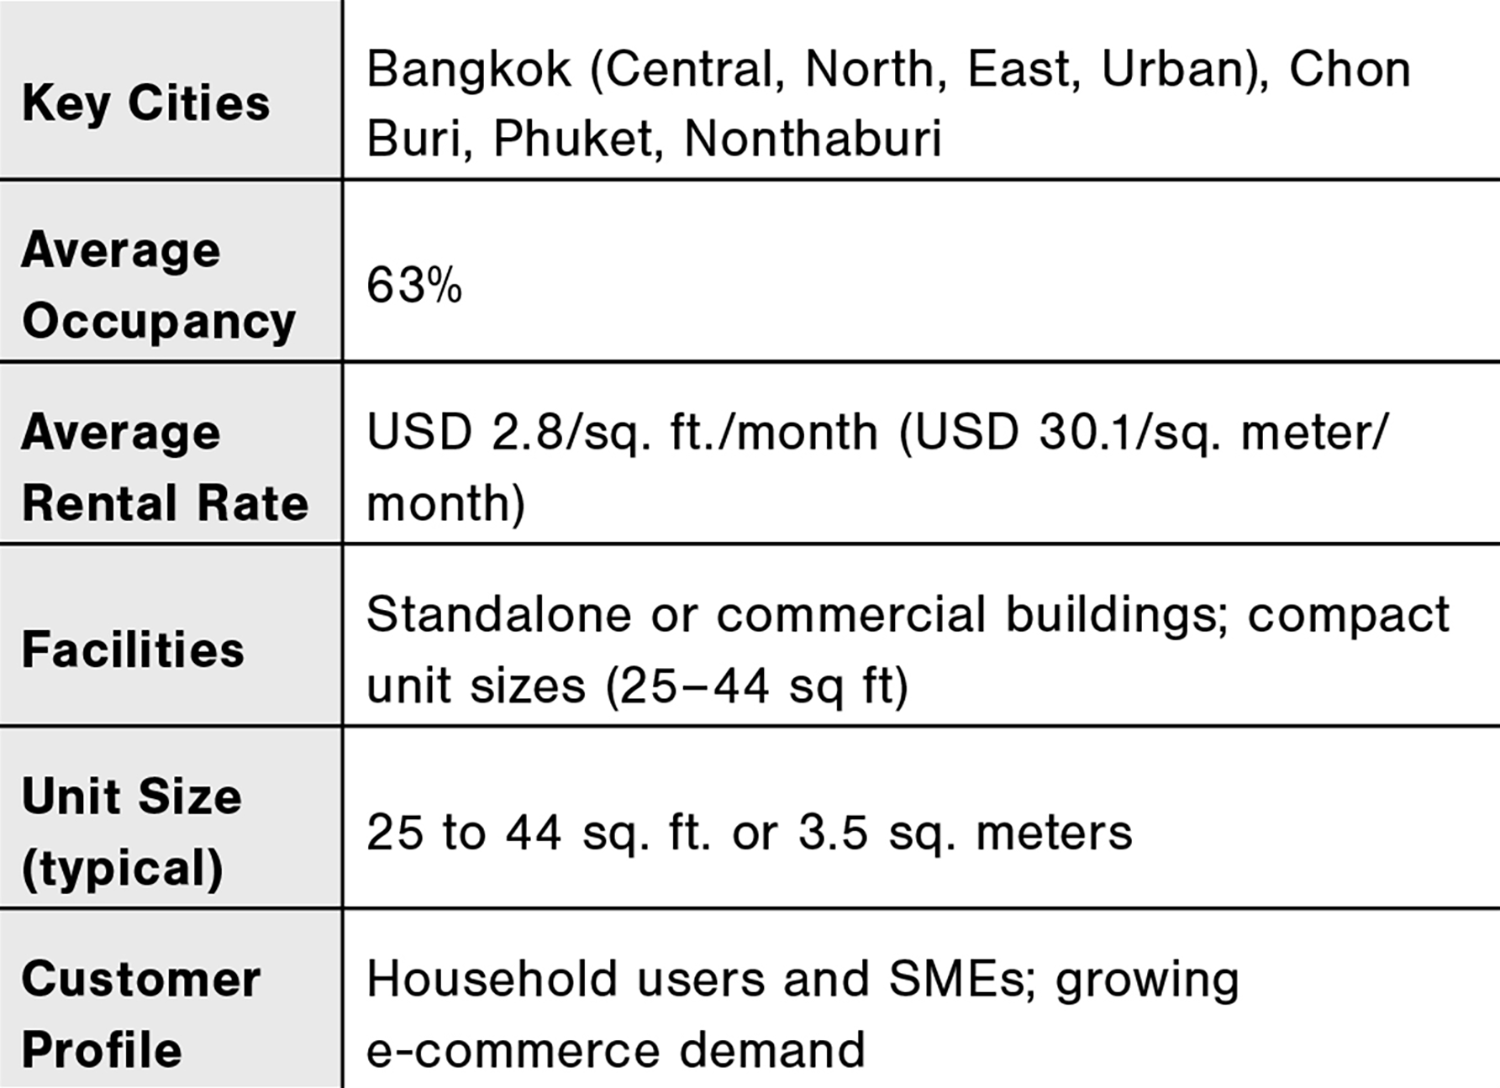
Bangkok’s central areas command premiums because density is high and residential space is tight. Eastern areas remain cost-competitive because they serve longer-term tenants and household users looking for affordability. The market is bifurcating, but the split is clean and predictable.
What matters here is digital-first marketing and online leasing, mobile payment integration, and regional-language customer support. The Thai market isn’t looking for premium positioning—they’re looking for access and convenience. If you can make it easy to rent online, easy to pay via phone, and easy to access 24/7, you win.
Thailand shows you what the next growth phase looks like. It’s not yet saturated, not yet hyper-competitive, but it’s moving in that direction. Entry now gets you first-mover advantage; entry later puts you fighting for scraps.
Key Recommendation: Build a Thai-language-first website, then English. Mobile payment integration and regional-language customer support are crucial. Be early on digital marketing and online leasing shifts. The market is moving toward digital-first operations—lead that transition. During typhoon/monsoon season, educate customers about stacking goods above ground level and consider restricting ground-floor unit rentals during peak rainfall months.
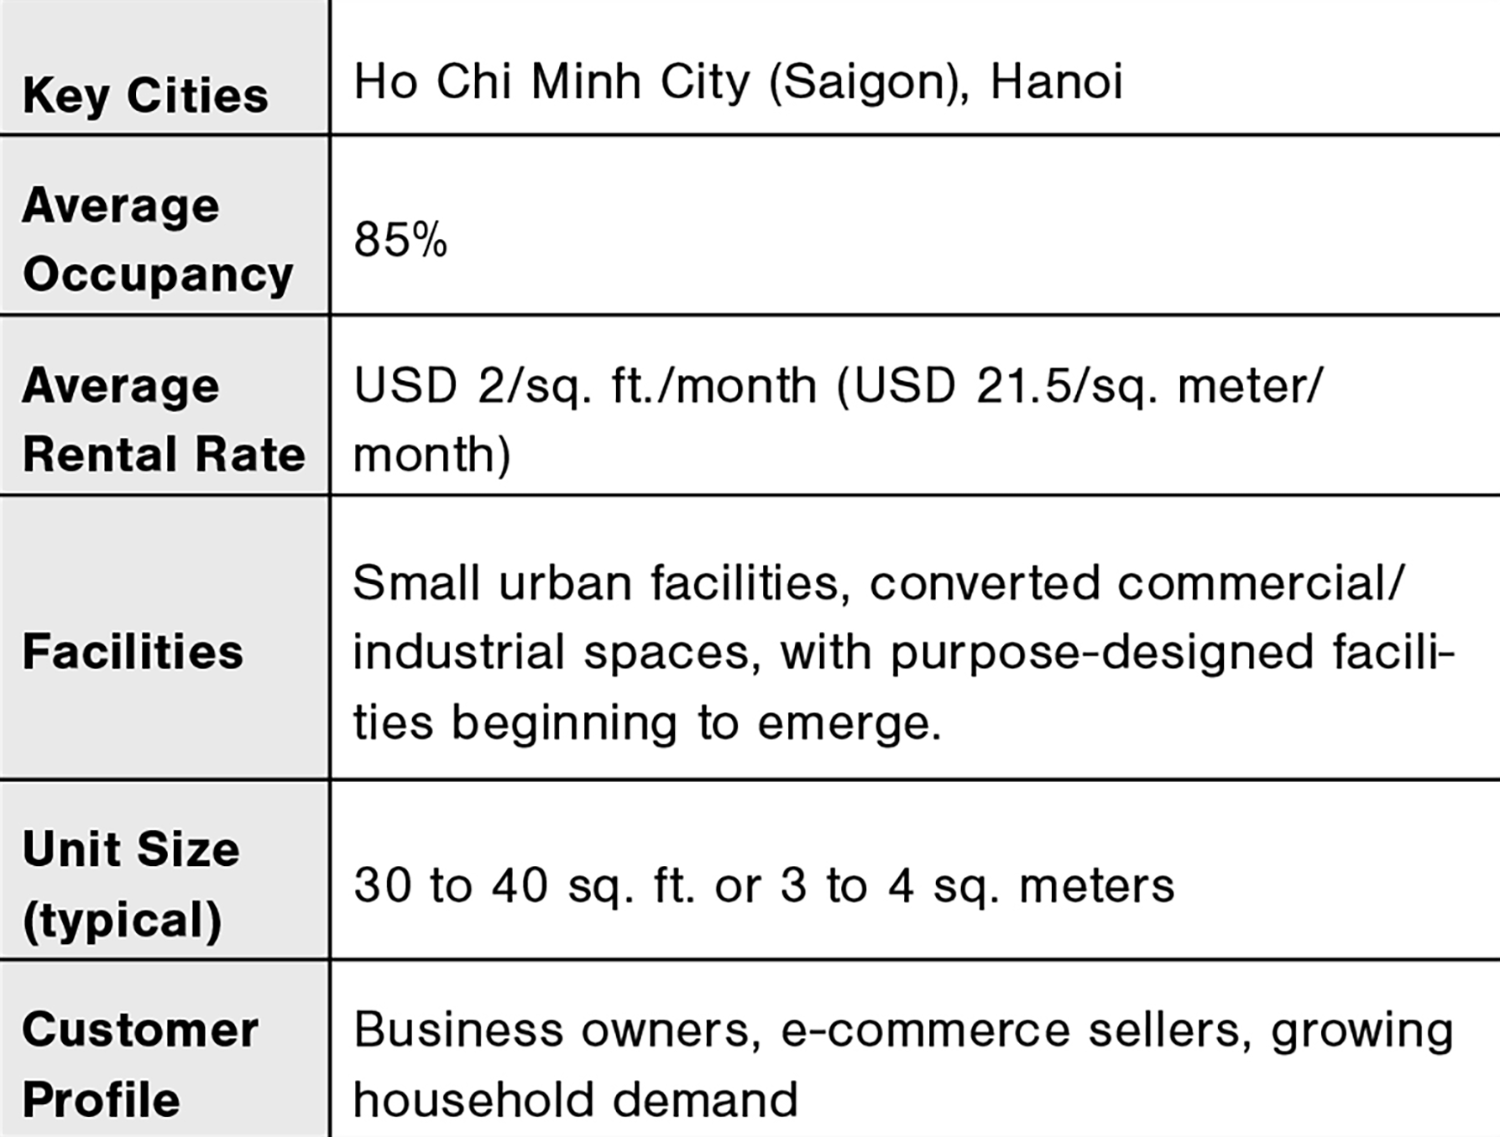
Occupancy at 85 percent is remarkable for an emerging market. But rents are USD 2 per square foot per month (USD 21.5 per square meter per month)—cheaper than most developed Asian markets, but significantly more expensive than India. Vietnam’s demand is unusually mixed. SMEs, e-commerce sellers, and small businesses are important customers, but household demand is already meaningful, particularly around moving, renovation, relocation, and temporary space constraints.
The market is app-first and mobile-first by necessity. Cash payments are still common, but digital adoption is accelerating. Flexible rental terms are important because customers need this flexibility.
Key Recommendation: Building a Vietnamese mobile-first site with a focus on Zalo, Vietnam’s No. 1 messaging app, phone nr, website chat, QR payments, and a simple online reservation is a good place to start. Compete on trust, convenience, and flexibility. Keep in mind that the market is still discovering the category of self-storage. Typhoon and monsoon seasons are operational realities, so invest in drainage, waterproofing, sump pumps, and elevated entry points before your first flood.
The operators who win aren’t the ones who build a Japan playbook and try to export it to Vietnam, Thailand, or India. They’re the ones who slow down, spend time in each market, understand its language—both literal and economic—and build something that fits. They’re the ones who see the chaos and recognize it for what it is: order underneath.
That’s the only playbook that works in Asia. It’s not one strategy but eight strategies, eight websites, and eight approaches to your customer, your pricing, your technology, your brand.
Welcome to organized chaos. Now go build something that works inside it.
razilian self-storage is moving from an unfamiliar real estate niche toward a recognizable urban solution. The change is visible in São Paulo, where apartment living, neighborhood retail, and last-mile commerce often meet on the same street. For operators looking at Brazil, the important lesson is that growth is real, but it is not uniform. Market education, local demand, and disciplined site selection still matter more than simply adding doors.
The numbers show how quickly the sector is developing. A survey by Brain Inteligência Estratégica and the Brazilian Self Storage Association, known as ASBRASS, counted 383 operating companies and 595 facilities across 110 cities in the first quarter of 2025. Available units had risen from 147,770 in 2021 to 220,901, an increase of 49.5 percent in four years. By the first quarter of 2026, an updated survey counted 244,562 units in 625 facilities across 112 cities, up 10.7 percent year over year. The 2025 survey measured almost 1.93 million square meters of rentable space, roughly 20.8 million square feet.
Those figures describe expansion, but they also reveal concentration.
Forty percent of facilities in the 2025 survey were in São Paulo state, and the Southeast accounted for 55.8 percent of the national total. Average vacancy was 18.6 percent. An operator should resist turning those averages into a national formula. A dense São Paulo neighborhood, an industrial corridor and a midsize interior city have different traffic patterns, housing types, and business needs.
Demand comes from several sources. Smaller homes and frequent moves create residential need, while renovations, family transitions, and temporary assignments produce shorter stays. For businesses, storage can replace a back room, support seasonal inventory, or place products closer to consumers without the commitment of another retail lease. The common element is flexibility: Renters can change the amount of space they rent as circumstances change. In Brazil, however, many potential users do not yet recognize self-storage as the answer to their problem.
Limited public awareness remains one of the market’s largest constraints. A household may first consider moving to a bigger apartment, while a merchant may search for a conventional warehouse. Both can overlook a nearby storage facility because the category is unfamiliar. This affects more than advertising. It lengthens lease-up, makes a clear explanation of access and security essential, and gives referrals unusual importance. The encouraging part is that awareness is cumulative. Every visible facility, satisfactory rental, and recommendation introduces the solution to another circle of renters. As familiarity increases, inquiries and demand follow.
SmartStorage illustrates that mixed approach. Its facilities offer units from about one to 100 square meters for households and businesses. Small spaces may serve apartment residents, while larger ones can support retailers, local businesses, or online sellers. The practical lesson is that unit dimensions cannot be considered alone. Loading access, elevator capacity, corridor width, renter circulation, and the ability to reconfigure partitions determine whether a nominally available unit is genuinely useful. A balanced plan is measured by how the building works after opening, not only by the number of units on a drawing.
The choice of format is also broadening. GoodStorage, an established operator in the São Paulo region, combines conventional self-storage with flexible warehouses and larger urban logistics properties. It reports close to 500,000 square meters of leasable area across those products, so the total is not a measure of self-storage alone. It does show the range of flexible-space demand that a large metropolitan economy can generate.
Existing buildings can offer strong urban locations, but conversion is not simply a matter of installing partitions. Floor loading, ceiling height, fire protection, vehicle access, elevators, circulation, and structural reinforcement can change the economics quickly. A mezzanine may add rentable area, yet its cost and effect on movement must be modeled. SmartStorage has used converted properties in greater São Paulo, where the best lesson has been straightforward: Calculate net rentable area only after the building’s physical and regulatory limits are understood.
Operations then turn a property into a solution. Renters need predictable access, clean common areas, understandable contracts, and confidence that management will respond when something goes wrong. Cameras, access control, and mobile apps can make a facility easier to use, while modular partitions allow the unit mix to evolve. SmartStorage uses round-the-clock camera monitoring, app-based access, and solar power where a property permits it. Technology does not substitute for a visible manager, clear communication, and consistent maintenance.
SmartStorage’s experience offers a reference point rather than a national benchmark. The company was founded in 2020; as of September 2026, its network included 13 locations operating or under development, combining company-owned projects with a franchise presence. Completed and planned space exceeded 20,000 square meters, including projects not yet available to rent. Its established facilities have typically reached 85 percent to 90 percent occupancy, although results vary by site and age. A project of approximately 5,000 square meters in the Anhanguera area is planned as its largest facility and reflects the search for sites able to serve both homes and businesses.
Brazil’s company count also points to a fragmented industry. The 383 companies identified in 2025 operated 595 facilities, an average of fewer than two per company. That leaves room for independent owners with close local knowledge, regional groups, and larger platforms. It may also create opportunities for management agreements, acquisitions, and franchising. Franchising can carry operating methods into new cities, but the model does not cure a weak property. The local partner still needs a viable site, sufficient capital, clear standards, and support through the period between construction and stable occupancy.
For investors and operators, the central question is not whether Brazil can add facilities; recent growth has already answered that. The question is where a facility fits within its immediate trade area and how long renters will take to understand it. The strongest projects will connect research with adaptable design, conservative underwriting, and steady local education. In a market where many renters are discovering the category for the first time, trust is an operating asset. A dependable experience creates repeat business, referrals, and a larger market for everyone at a gradual pace.
Brazilian self-storage will probably become more varied as it expands. Some locations will remain primarily residential, others will develop a substantial small-business base, and larger urban-space formats will serve logistics demand that sits beside traditional storage. São Paulo will continue to matter, but growth outside the capital should broaden the industry’s map. The opportunity is substantial because awareness is still developing. Operators who explain the solution well, choose properties carefully, and adapt their unit mix to local evidence can help turn that opportunity into durable demand.
ocated just outside Fort Worth, Texas, on the West Fork of the Trinity River, lies Lake Worth, a growing community known for welcoming new businesses with relatively low property taxes. 10 Federal recognized it as the perfect location for its latest facility, strategically developing a 2.6-acre site directly across from Target, Walmart, and a newly built apartment community.
Designed by Nova Group, Inc. and constructed by DSS Building Group, the facility broke ground in September 2025. The Class-A facility opened for business in July 2026—ahead of schedule and on budget. Today, occupancy continues to grow at the 77,725-net-rentable-square-foot facility, which features 786 climate-controlled units, a key differentiator in a market with fewer than 4.5 square feet of climate-controlled storage per capita. Meanwhile, on the ground floor, an additional 2,100 square feet of space awaits three future retail tenants.
The location also debuted several of 10 Federal’s latest customer-facing enhancements, including refreshed branding, updated signage, and a redesigned tenant portal, now called “My Account.” Together, the physical improvements and digital upgrades make the facility a showcase for how 10 Federal is investing in the customer journey, from curb to lease.
For additional information about the 10 Federal location at 3946 Paul Meador Road, visit the company’s website, 10federalstorage.com/storage-units/texas/lake-worth/paul-meador-road.
e’ve been making the case that the most important D in self-storage may be the one that comes first: disposition. While death, divorce, downsizing, and displacement create the need for space, our reluctance to let go is what fills it. For three installments, we’ve taken you on a journey of the mind, provided real-world examples, and offered concrete data. Now, it’s time to make some money.
For those who’ve lost a loved one, operators may consider partnering with estate sale companies and professional organizers, promoting estate transition packages, or offering an introductory period that accommodates families clearing a home. Highlighting climate-controlled larger units for whole-house cleanouts can also benefit tenants and operators alike. Larger units not only give people more space to easily navigate the many items left behind when it’s time to sort through them, but they also tend to create long-term tenants.
“Someone renting a 5-by-5 unit may be able to pack it up and move relatively easily, whereas relocating the contents of a full 10-by-30 unit requires considerably more time and effort,” says Dr. Ahmet Kuyumcu, founder of Prorize, an AI-powered revenue management platform. “Variables such as unit type and size, payment method, and the customer’s proximity to the facility can help explain behavior and length-of-stay patterns. However, pricing decisions should be driven by market conditions, demand forecasts, and aggregate customer behavior—not by an individual customer’s personal circumstances.”
Kuyumcu adds that operators may consider offering customers a discounted rate in exchange for a minimum-length-of-stay commitment—something people handling an estate may be very open to. “Although this pricing structure is not yet widely used, some operators in certain countries and markets have offered it as an optional arrangement. It can give customers greater price predictability while helping operators forecast occupancy and length of stay.”
This type of arrangement could be especially appealing, for example, if the children handling the estate live in New York and their parent(s) lived in Miami. In these situations, remote account management will be a priority, so operators should offer autopay, provide digital access to documents, and clearly communicate rent increases, security issues, and pest control measures via email or text if they’ve opted in.
Separating couples may be attracted to flexible leases that allow for easy unit-size changes. As they begin going through belongings and deciding who gets what, items may gradually leave the unit, potentially necessitating consecutive moves from larger to smaller units. Making those transfers painless can keep the customer at the facility rather than giving them a reason to shop elsewhere.
Security and accountability may also matter more than usual. The ability to provide separate access codes to the same unit, for example, could create a record of which partner entered the property if/when a dispute over belongings arises, without the manager having to play referee.
Technology can help couples manage another problem: figuring out exactly what’s in storage. SecureInventory by SecureLease, powered by InstaBoxx, is an AI-assisted tool that allows renters to create a digital inventory of items they place in storage simply by photographing the contents of a box. The app categorizes those items with photos, descriptions, and estimated values. When something is added or removed, the inventory updates accordingly. “This adds another layer of value to the unit,” says Stacie Maxwell, vice president of growth and innovation at On The Move. “Inventory has always been the tenant’s responsibility—or more accurately, their problem. Tools like this provide a solution in a way that benefits both sides.”
These tenants are storing the portion of their old home that doesn’t fit into the new one for the foreseeable future. The storage unit becomes an extension of their home, so they’re likely looking for services and items that help manage belongings over an extended period. Shelving, storage bins, protective covers, and other organization products will be more appealing to someone planning to visit a unit repeatedly for years than to someone storing belongings for a few months.
A downsizer who intends to regularly access seasonal decorations, clothing, furniture, or hobby equipment also likely won’t pack a unit as tightly as possible. Suggesting a larger unit with shelving and an aisle may be more useful, and more profitable, than the smallest unit capable of containing everything.
A customer dealing with an eviction, job relocation, deployment, disaster, or other sudden disruption may go from having no need for storage to needing it within hours. To attract them, online renting should be seamless, unit availability should be current, pricing should be clear, and electronic leases should be easy to complete via phone.
Customers should also be able to determine what size they need without driving to the facility with a tape measure. Size guides help, but an AI-powered platform like Self-Storage.ai may be even more beneficial. The company’s SpaceStacker allows customers to add 3D representations of their own items to units of different sizes to visualize how they’ll fit. “The user experience is better, website engagement and SEO are improved, and clients see more conversions and fewer dropouts,” says Nylan Raufaste, co-founder of Self-Storage.ai.
Pickup services, moving or military partnerships, and truck rentals can also remove friction for people facing permanent or temporary displacement. For those who have recently experienced a disaster, an introductory offer can help get them in the door, provided the promotion and subsequent rate are communicated transparently. Following a catastrophe, participating U-Haul facilities will offer 30 days of free storage and U-Boxes when available. “When people are in a jam, our heart goes out to them,” says CEO Joe Shoen. “We don’t want their money. We’ve got the space, so we let them have it. And who knows, maybe they’ll remember us some day down the road when they need a moving truck or storage.”
- Preserve Your Memories.
- Protect What Matters.
- Safekeeping Till You Decide What You’re Keeping.
- Make Space For New Memories.
- Some Things Aren’t Meant To Be Sold.
Here’s another consideration: While someone searching online for “storage units near me” has already decided storage is the solution, what about the person searching for “what to do with a parent’s belongings,” “how to store family heirlooms,” or “what to keep when downsizing”? Content, landing pages, and paid-search campaigns built around those questions could introduce storage as a possible solution earlier in the process. An estate storage page might explain climate-control and larger-unit options, while downsizing content could discuss long-term storage and organization. Disaster-related messaging could emphasize immediate availability and fast online rentals, whereas divorce-related messaging could focus on privacy, security, flexibility, and access control. Instead of waiting for customers to search for storage, operators can meet them while they’re still deciding what to do with their stuff.
The same principles can apply to the sales process. When someone calls and says, “I need storage,” the natural response is to ask how much stuff they have to store. Understanding disposition can raise a useful question: Why? The answer can tell the manager whether the customer needs climate control, frequent access, a larger unit with room to navigate, moving assistance, packing supplies, digital inventory tools, or another product or service.
For operators, understanding that instinct turns disposition from a theory into an opportunity. It can determine the ways they market, what they offer, and how they sell. Because when possessions become part of who we are, making room for what matters creates value for both customers and operators.
Brad Hadfield is MSM’s lead writer and web manager.
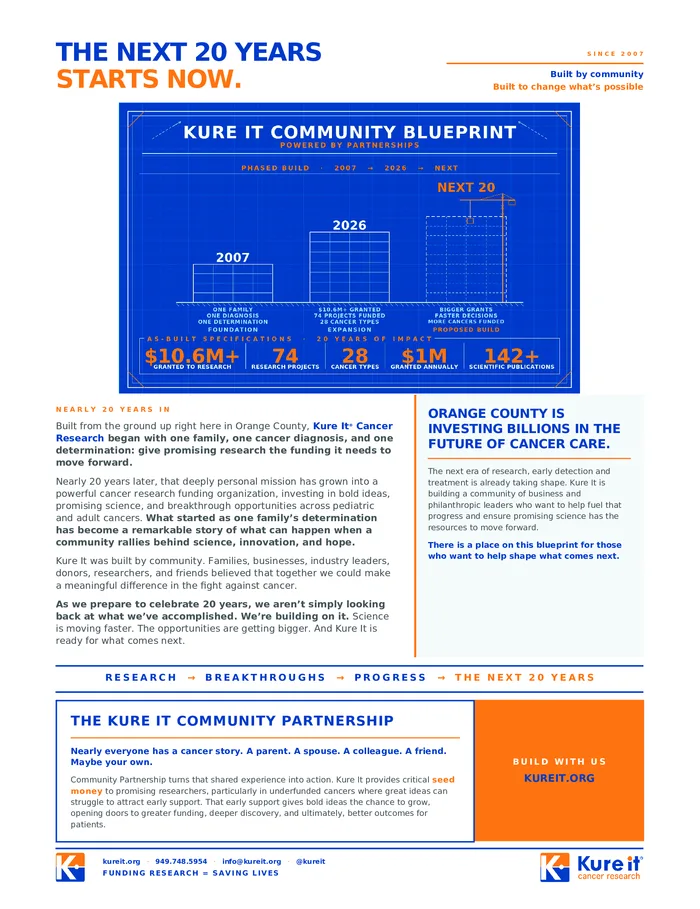
t should’ve been a normal day at Brown University. On Dec. 13, 2025, students were taking final exams and likely looking forward to the holiday break. But someone else was about to change lives and shatter the campus’ sense of security. A tall man dressed in black, his face obscured by a camouflage mask, entered the campus armed with a Glock 34 9mm semiautomatic pistol and opened fire, killing two people and wounding eight others. Then he disappeared.
Investigators had little to go on, but one clue would prove critical: a gray Nissan with Florida plates. Providence police searched for the vehicle using a network of Flock Safety cameras, eventually identifying its license plate and tracing it to a rental car. Less than a week after the shooting, investigators tracked the suspect to an Extra Space Storage unit in New Hampshire.
And while the Brown case highlighted their potential in a horrific crime, the same technology is being used to solve a problem considerably more familiar to self-storage operators: burglary.
In August of this year, Pennsylvania police used Flock cameras after two men allegedly burglarized a self-storage facility. The system identified the black GMC pickup seen entering the property, allowing investigators to trace it to its registered owner. Police subsequently recovered items allegedly stolen from the facility, as well as additional stolen property reportedly stored in another unit.
That same day in Georgia, police tapped into the Flock technology to investigate a string of break-ins at Crazy Ray’s Self Storage. Security footage showed two men arriving in a Chevrolet Avalanche and breaking into 10 to 15 units, but a nearby Flock camera provided something considerably more useful: the vehicle’s license plate. Police said the evidence helped identify a suspect who was also linked to another theft investigation.
Three investigations of dramatically different severity, but each illustrates what has made ALPR technology such a powerful law enforcement tool: It can turn a vehicle into a trail. So why are they also considered controversial?
Unlike traditional surveillance cameras that continuously record video, Flock cameras capture still images of passing vehicles. That information is stored in a cloud-based system that authorized users can search during investigations. The technology can also generate real-time alerts when a plate matches law enforcement information associated with a stolen vehicle, Amber Alert, or other investigation.
For self-storage operators, the appeal is obvious. A conventional security camera might show a black SUV entering a property shortly before several units are burglarized, while an ALPR can potentially give investigators the plate and identifying characteristics they need to determine which black SUV they’re seeking.
That’s what’s made Flock one of the more controversial surveillance technologies in the country. Privacy advocates have raised concerns about the collection and retention of vehicle-location data and the ability of a large network of cameras to reconstruct where a vehicle has traveled, even when its owner isn’t suspected of a crime. Some consider this an abuse of power. A Washington Post investigation found nearly 50 cases of officers charged with or accused of misusing the cameras, many involving tracking current or former romantic partners. The Institute for Justice also keeps a public database of more than 150 documented cases nationwide, sorted into four types (stalking, non-law-enforcement use, misread errors, and other misuse) drawn from media reports and public records.
The backlash continues to grow, with residents vandalizing the cameras and many cities terminating contracts due to public outcry. Justin Insalaco, a retired police officer and board member with Crime Stoppers, thinks it’s ridiculous.
Insalaco points out that consumers already encounter license plate readers and other forms of tracking in everyday life, from toll roads to private businesses to the phone we all carry. “You know that thing is traceable and tracking you.” What makes ALPR particularly valuable to law enforcement, he says, is its ability to turn a vague vehicle description into something investigators can actually pursue.
“If you own a self-storage facility and you’re worried about security and thefts, and you don’t have an ALPR camera, what are you doing?” Insalaco asks. “It doesn’t have to be Flock. I’m not trying to promote Flock. I don’t think the brand matters.”
For self-storage operators, Insalaco says that doesn’t necessarily mean replacing an entire surveillance system. An ALPR camera positioned at a facility’s entrance and exit can complement conventional cameras throughout the property. If surveillance footage captures a vehicle near a burglarized unit but can’t provide a readable plate, the ALPR system at the gate may provide the identifying information investigators need. “I wouldn’t own a self-storage place without having some kind of ALPR camera at my gate where people are coming in and out,” he says. “Otherwise, what are you going to give to the cops? A description such as a black GMC isn’t very useful, but a license plate can give investigators somewhere to start.”
The company has also responded to concerns over who can access ALPR data and how it can be used. Langley told Fortune that Flock has introduced additional privacy protections and measures intended to address misuse by law enforcement officers. “Local communities, not Flock, decide their sharing rules, offense filters, and retention windows,” he said. “Our job is to give them better tools that reflect their needs and values of their communities and to help hold individuals accountable when someone misuses the system.”
Insalaco agrees that safeguards are necessary, but he believes Flock hasn’t always helped itself in communicating with a skeptical public. “I think they brought a lot of these problems on themselves, to be honest, by the way that they responded,” he says.
Still, Insalaco distinguishes criticism of Flock from criticism of ALPR technology itself. “I’m not saying Flock,” he says. “The attack on the actual technology itself, meaning the ALPR system, is the thing that I’m opposed to. If you’re not using ALPRs, I think that’s a mistake.”
For an industry that has invested heavily in gates, cameras, and access controls, ALPR seems to be asking the question: What if the next generation of security systems didn’t just record who entered a facility but recognized a potential threat before the gate ever opened?
e operate storage on the Outer Banks, a string of barrier islands off the North Carolina coast where the population can multiply several times over between February and July before emptying out again by October. Most pricing advice in this industry assumes demand that moves in a gentle, predictable line. Out here, demand looks more like a heartbeat monitor. Learning to price for that swing, rather than against it, has been the most useful operational lesson we have picked up.
The peak-season renter arrives in spring and is gone by fall. Think vacation-rental managers storing linens and supplies, seasonal businesses holding inventory, families parking the overflow of a summer house. This is the most price-tolerant demand we see because it is short, urgent, and tied to a season that prints money for the customer. It is also the most temporary; counting on it past Labor Day is a good way to be disappointed.
Boat and RV owners are a different animal. Their need is seasonal storage too, but their units are large, their tenancy tends to run in years rather than months, and they would rather pay through a quiet winter than risk losing their spot before summer. That makes them strong candidates for annual pricing, where we trade a little peak-season upside for revenue that does not evaporate in the off-season.
Second-home owners are the quiet backbone. They store furnishings between renovations, seasonal gear, and the contents of a house being readied for the rental market. Their demand is steadier and less tied to the tourist calendar, and they care more about security and reliability than about a few dollars of monthly rate. Then there is the year-round local base; it’s the smallest group by headcount, but the most important one to keep, for reasons I will come back to.
So, we price to the season instead. Street rates climb as occupancy tightens into the summer and ease back as the islands empty out, and we hold a portion of our most desirable inventory back from deep discounting because we know what it will command in June. None of this is exotic. It is the same revenue management a beach hotel has run for decades, applied to a corner of the industry that has often pretended its demand is flatter than it is.
Seasonality is not the only lever the coast hands you. Salt air and humidity are hard on stored belongings, which makes climate-controlled space noticeably more valuable here than it is inland, and that premium holds up across the calendar far better than a raw street rate does. A second-home owner storing furniture through a damp winter is not shopping on price the way a July vacationer is. Pricing the product mix, not just the season, is part of the same discipline.
The harder discipline is resisting the urge to chase every peak dollar. A street rate that spikes too aggressively in July fills units, but it also sets an expectation, and the customer who signed at the summer peak remembers that number when you try to hold it through the winter. We have learned to price the peak for what the peak is worth without pretending the peak lasts all year.
The temptation is to treat that post-storm spike as found money. We have come to see it differently. Demand born of a disaster is real, but it is not a foundation you can build a business on. Plus, an operator who appears to profit from a community’s worst week earns a reputation that outlasts the storm. We meet the demand and serve it well, but we do not price our annual plan around the assumption that catastrophe will fill our units.
That floor is why we are careful with our existing customers, even when the market would let us be aggressive. It is easy, in a high-demand summer, to push rate increases on tenants who have nowhere convenient to go. It is also short-sighted, because the local renter you overreach on in July is the one whose unit you will badly want filled in January, and word travels fast in a small coastal community.
So, we run a deliberate split. New-customer street rates move with seasonal demand, reflecting peak conditions, while increases for established local customers stay measured, predictable, and fair. The volatile market gets the volatile pricing; the loyal base gets the stability, as they’re the ones providing consistency. It costs us a little at the summer peak and buys loyalty that pays all winter.
Pricing for volatility is really just pricing for reality that has been looked at more closely. It means separating the segments rather than blending them, letting the rate move with the season instead of fighting it, pricing the risks you actually carry, and protecting the tenants who keep the lights on when the tide goes out. Do that, and a market most operators would call unmanageable starts to look like one of the more honest pricing classrooms in the business.
Andrew Bonnis is a self-storage operator, marketer, and writer who covers pricing, operations, and the realities of running storage in some of the country’s more demanding markets.
y the time a quarterly economic report confirms that housing turnover has slowed or population growth has cooled, the conditions behind that shift may already be affecting local self-storage demand.
These reports describe conditions after data has been collected and analyzed. For day-to-day operations, facility-level activity can provide a more immediate view of what is changing in the local area.
Macroeconomic indicators such as unemployment, regional GDP, and housing reports provide useful context. But operators can pair them with signals from their own facilities and surrounding markets to identify potential shifts sooner.
- Inbound inquiries and call volume provide a direct measure of prospect interest. A meaningful increase or decrease in calls or messages about availability can help operators identify shifts in interest before they appear in move-in totals.
- Website activity, particularly searches for availability in a specific market, functions similarly, especially when paired with the most-searched unit sizes. Changes in searches for specific unit sizes can also help operators identify which types of inventory are attracting more or less interest.
- Reservation-to-move-in conversion rate is worth watching closely. A declining conversion rate, even when inquiry volume remains steady, shows that interest isn’t translating into move-ins at the same rate and warrants a closer look.
- Requested unit sizes, waitlists, and cancellations round out the more facility-specific signals. A growing waitlist for a particular unit size suggests real unmet demand worth addressing through pricing or availability adjustments, while rising cancellations can show that initial interest isn’t translating into completed rentals.
Facility data becomes more useful when paired with local context. Housing activity, business formation, and development permits can help operators understand changes taking place around a facility. The U.S. Census Bureau’s Building Permits Survey, for example, provides local data on permits for privately owned residential construction. Operators can also review local government development records and business formation data for additional context.
The dashboard doesn’t need to be complicated. Operators can track weekly inquiries, calls, website activity, reservations, move-ins, cancellations, conversion rates, and requested unit sizes in a shared spreadsheet or reporting tool. Local housing, permit, and business activity can be reviewed alongside those facility-level metrics.
The key is consistency. Compare each rolling 30- or 60-day period with the same period in previous years, where historical data is available. Look for several indicators moving in the same direction rather than treating one unusual week as a trend.
External signals can also guide where operators look for opportunities. New residential development or increased business activity near a facility may warrant closer attention to those areas, including targeted local marketing or commercial outreach. Facility-level inquiry and conversion data can then help determine whether that outside activity is translating into storage demand.
- Relying on a single metric in isolation – Inquiry volume alone, without checking conversion rates or unit-size trends alongside it, can be misleading, since a spike in inquiries doesn’t necessarily translate into actual leases.
- Ignoring seasonality – Comparing this month with last month can make a normal seasonal pattern look like a market shift. When possible, compare current results with the same period in previous years.
- Reacting to small sample sizes – A handful of unusual inquiries, cancellations, or move-ins can look like a trend when the underlying sample is small. Look for sustained movement across multiple indicators before making major changes.
- Confusing interest with confirmed demand – Inquiries and website activity show interest, not completed rentals. Track prospects through reservations and move-ins before treating increased attention as confirmed demand.
Broader industry research can still provide valuable context. MSM’s coverage of predicting self-storage demand shows how market-level indicators can contribute to demand analysis, while its 2026 self-storage industry outlook highlights the growing role of data in pricing and revenue decisions.
The goal isn’t to produce a perfect forecast. It’s to build a repeatable process for recognizing meaningful local changes, testing those signals against actual results, and making better-informed decisions sooner.
elf-storage owners constantly look for ways to improve cash flow. Raising occupancy, adjusting rental rates, controlling operating costs, and upgrading security all contribute to stronger returns on their investment. Yet many investors overlook a major tax planning opportunity already built into the property: cost segregation.
Cost segregation, often called cost seg, separates qualifying building components of the property. Instead of writing off building components over 39 years, owners move qualifying components, such as paving, fencing, lighting, gates, and office finishes, onto shorter depreciation schedules. That creates larger deductions earlier in ownership, resulting in immediate tax savings.
Historically, investors had to request a proposal and wait for a customized study before knowing whether the numbers made sense. CostSegregation.com changes that process. CostSegregation.com is the first software solution built to offer direct-to-investor cost segregation. Self-storage owners can review estimated deductions and tax savings, use the software for free, and only pay if they’re happy with the results. Here are the key takeaways:
- Self-storage facilities often contain site improvements and specialty components that qualify for accelerated depreciation.
- CostSegregation.com provides an instant estimate and generates a full cost segregation report in just 15 minutes.
- The platform also supports eligible residential and commercial investment properties elsewhere in an owner’s portfolio.
- Asphalt and concrete paving,
- Parking areas and drive aisles,
- Curbs and sidewalks,
- Security gates and perimeter fencing,
- Exterior and site lighting,
- Signage and signage foundations,
- Site drainage and stormwater costs,
- Security cameras and surveillance equipment, and
- Office flooring, furniture, fixtures.
Many of these assets listed follow shorter depreciation schedules than the main building structure, qualifying for accelerated depreciation deduction. Those deductions leave more cash flow for security upgrades, expansion, operating reserves, debt reduction, or another acquisition.
For climate-controlled facilities, the analysis can also include specialized electrical, controls, and other systems, although HVAC and other building systems require closer review because they often remain structural components.
Owners can begin a cost segregation study when they acquire, construct, or renovate a facility; the related depreciation begins once the property is ready and available for use. If a cost segregation analysis was not completed in that first year, a prior-year report can still be evaluated through a look-back study.
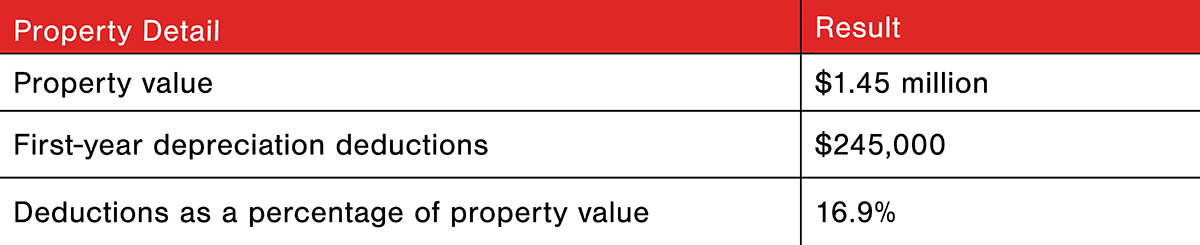
One CostSegregation.com self-storage example involved a facility valued at $1.45 million. The completed analysis generated $245,000 in first-year depreciation deductions.
At a 35 percent combined tax rate, the $245,000 deduction translates to approximately $85,750 in estimated first-year tax savings.
- Potential first-year depreciation deductions and
- Estimated tax savings based on those deductions.
Additionally, the platform allows investors to view the price of their report based on their building’s tax basis. Commercial reports start at $1,295, whereas residential reports start at just $495.
In fact, CostSegregation.com supports eligible residential and commercial investment properties with up to $1.5 million in building basis, excluding land. Owners can use the same platform to evaluate a self-storage facility alongside qualifying rental homes, short-term rentals, offices, warehouses, and other properties in their portfolio.
Every completed report includes detailed depreciation schedules, up to five corrections, and KBKG-backed audit support.
CostSegregation.com is the top-rated cost segregation software solution. The platform averages 5/5 stars on Google reviews and has maintained a 100 percent IRS audit success rate since launching in 2016.
That expertise is built into a straightforward process:
- Enter the property address. AI-assisted public data fills in available property details, turning a process that once took hours into one that takes under a minute.
- Confirm the information. Review the purchase price, land value, placed-in-service date, and major improvements. Owners can also invite their CPA into the workflow.
- Review the results. Complete the process in less than 15 minutes and download the full report if they’re happy with the results.
The first step is to see what the opportunity looks like for your facility. Use CostSegregation.com’s free calculator to compare your estimated first-year deductions and tax savings with the report price.
How much money can cost segregation save a self-storage owner?
The result depends on the facility’s building basis, site improvements, component mix, placed-in-service date, and the owner’s tax rate. One CostSegregation.com self-storage example generated $245,000 in first-year deductions on a $1.45 million property.
Do I need blueprints or a property inspection?
No. For properties that fit the software, CostSegregation.com uses available public information and straightforward questions about the facility. The self-guided process does not require a site visit.
Can I use the software for a facility I purchased in a prior year?
Yes. For qualifying prior-year properties, CostSegregation.com includes a Section 481(a) calculation schedule when applicable. The owner’s CPA determines how the catch-up depreciation fits the tax return.
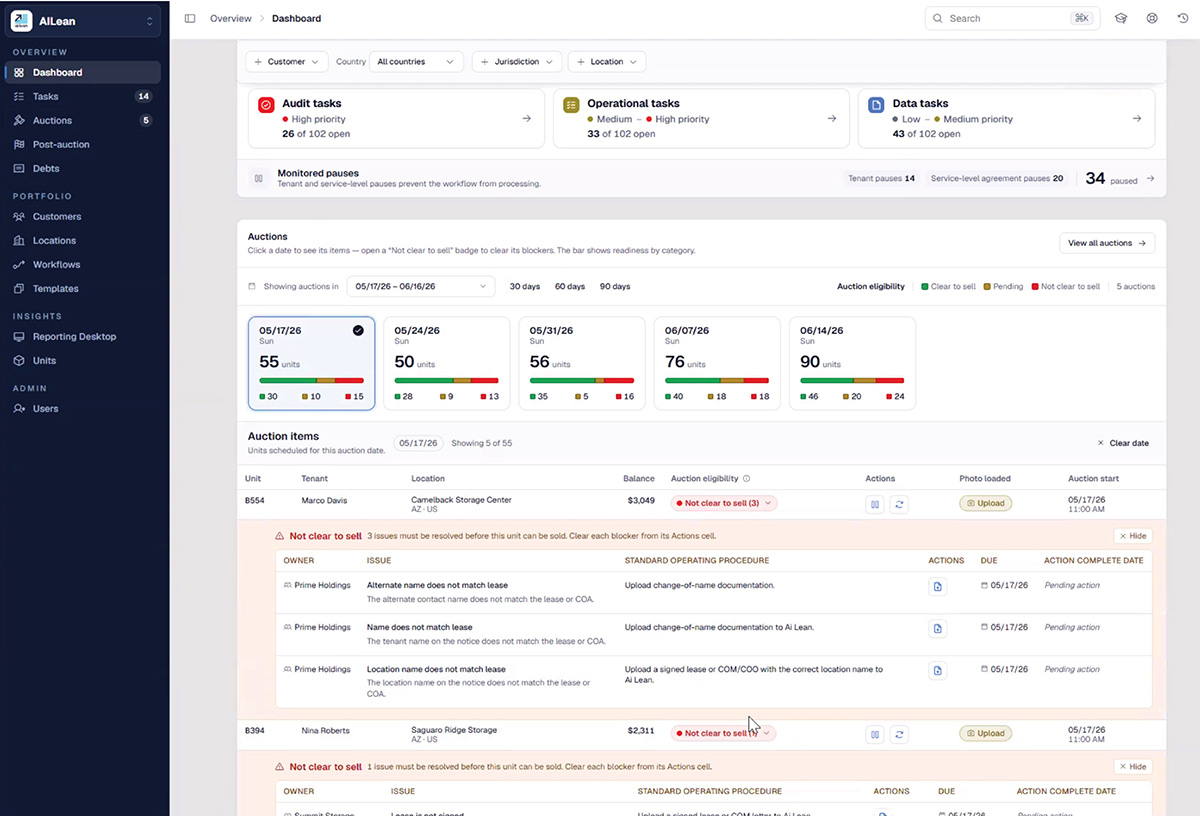
ollecting overdue rent is only one part of delinquency management. A missed payment can set off a chain of collection attempts, lien notices, legal requirements, auctions, and unit preparation. Each step takes time and money, while opening the door to potential mistakes.
Ai Lean, a self-storage technology company, has brought that entire process under one roof with its new Intelligent Recovery Platform, which connects collections, lien compliance, auctions, and unit turnover. Rather than requiring operators to manage several disconnected systems, the platform follows an account from its first missed payment until the unit is ready to generate revenue again.
The company already works with more than 1,500 facilities, with services spanning all 50 states and international markets. Ai Lean integrates with operators’ existing facility management systems, including Tenant, Inc., SiteLink, Cubby, and more, without requiring them to replace their current technology.
Ai Lean did more than extend its existing services into another country. Working alongside the operator, the company began “Project Bahamas,” developing and testing a new approach to recovery within the operator’s active self-storage business. The project eventually became the foundation for the new platform. “What came out of that partnership wasn’t an update or a new feature,” says Shardlow. “It became the new Ai Lean, not shaped and tested in our own heads but in a real operator’s business.”
When an account does proceed to lien, Ai Lean’s Lien Compliance engine manages the required steps according to applicable laws. A centralized dashboard displays each account’s status, required actions, and supporting documents, along with a complete audit trail. The company says its lien services cover all 50 states, as well as international markets. Ai Lean also carries wrongful-sale liability for lien processes it handles, providing another layer of legal protection.
But Ai Lean’s approach doesn’t end when the gavel drops. Operators using BidHaven also gain access to Rent-Ready, a workflow that manages the steps required to return a unit to available inventory, including lock cuts, photographs, inspections, and securing the space. QR-code pickup is designed to simplify the post-sale handoff to auction buyers.
The distinction is an important one. Clearing a tenant’s debt doesn’t necessarily mean an operator has recovered the unit’s earning potential. Every additional day spent clearing and preparing the space represents another day it cannot be rented.
Ai Lean reports its technology has reduced delinquency by as much as 80 percent and recovered hundreds of staff hours per month. When Storage Star implemented end-to-end automated delinquency management with Ai Lean, for example, bad AR dropped from $1 million to $120,000 in 90 days. Delinquency fell below 2 percent, and the operator reclaimed more than 500 staff hours per month.
For Ai Lean, the new platform isn’t just a success but an evolution. “The team that started by solving the hardest, least glamorous problems in storage, delinquency and lien compliance, has become something bigger—much bigger,” says Shardlow.
elf-storage has the fundamentals of a major asset class. The next few years are about acting like one.
This week, a big piece of the self-storage industry is under one roof in Atlanta. It’s a good moment to ask what kind of industry we want to be.
On paper, we’re already in the big leagues. Institutional capital owns a large share of the product. Tenants stay longer every year—closer to what an apartment gets than what anyone expected when this business was built on garage doors and handshakes. Capital that used to need storage explained to it now comes looking for it.
But we have a habit. We show up late to lessons the hotel industry learned years ago: brands, revenue management, consolidation. I’ve called it being fashionably late. Roughly 10 hotel companies now flag most of the rooms in America, and plenty of those hotels are still owned by individuals flying somebody’s brand. The good news about being late is you can see where the potholes are.
There are three things big-league industries do that we still skip.
They protect the reputation of the product. Revenue management works. But just because the data says you can, doesn’t mean you should. Aggressive teaser rates followed by steep increases build short-term revenue and long-term resentment, and resentment eventually finds a regulator. Scott Zucker used this page in September to walk through the scrutiny data-driven pricing is already drawing. We should set our own standards before someone sets them for us.
They share data. The questions every operator asks are simple: How many units did I rent, and from where? We still guard numbers that are mostly public anyway, and it keeps everyone guessing. Better benchmarks help the independent with one store as much as the REIT with a thousand.
They invest in people and tools. We treat technology like an expense to cut instead of capital to deploy. It’s easy not to spend money, but it isn’t always wise. And the best tool in any facility is still a manager who has time to be on the floor renting units instead of chasing paperwork.
Every one of these is within reach of an operator with a single store. It comes down to deciding we’re a serious industry and behaving like one—on the rate page, in the data, and at the front counter.
We called this week the big leagues of self-storage. The name only matters if we play that way on Monday, when everyone is back at their desks.



You need steel structures that will stand the test of time. Spans that will protect your customers’ property. And designs that will support solar, whether you’re ready today or want to upgrade tomorrow.
Covered RV and boat storage demands a premium. Baja Carports stands ready to help you deliver, year after year.
Talk to StorageVault.
Proven platform delivering results since 1998.
- 265+ stores nationwide.
- Experienced team focused on results.
- Resources that respond when you need them.
- Canadian expertise that delivers.