
lower supply meets a long road to recovery. A Yardi Matrix team attended the Self Storage Association National Fall Conference Sept. 8 to 11 in Las Vegas and presented Self Storage Odyssey 2026: Navigating an Evolving Market. Slides are available upon request. Like Odysseus’ journey home, the sector’s recovery has been long and marked by obstacles, many stemming from its record-setting pandemic performance. Demand from domestic migration and home sales remains in a three-year slump, while renewed inflation poses another threat to normalization. Attendees confirmed that fundamentals weakened in August and early September. Near-term improvement will depend largely on declining new supply, but record oversupply in many markets could prolong recovery for years. Nationally, supply delivered from 2023 through 2025 nearly matched the previous peak from 2018 through 2020, without the COVID-era demand surge that accelerated lease-ups. Although occupancy appears to have stabilized, revenue growth remains pressured by the historically wide gap between in-place and street rates. Contributions from existing customer rate increases should also diminish as move-in and move-out activity normalizes. Despite these challenges, the sector remains favored by large investors, while transaction activity and pricing have continued their gradual recovery in 2026.
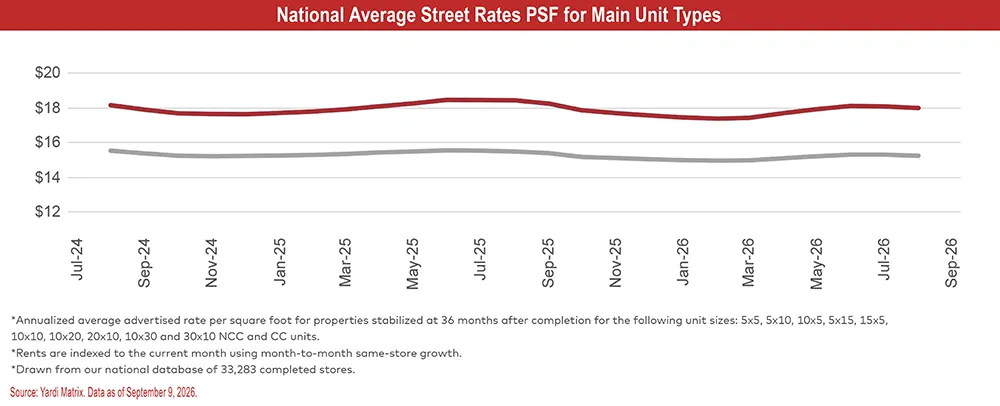
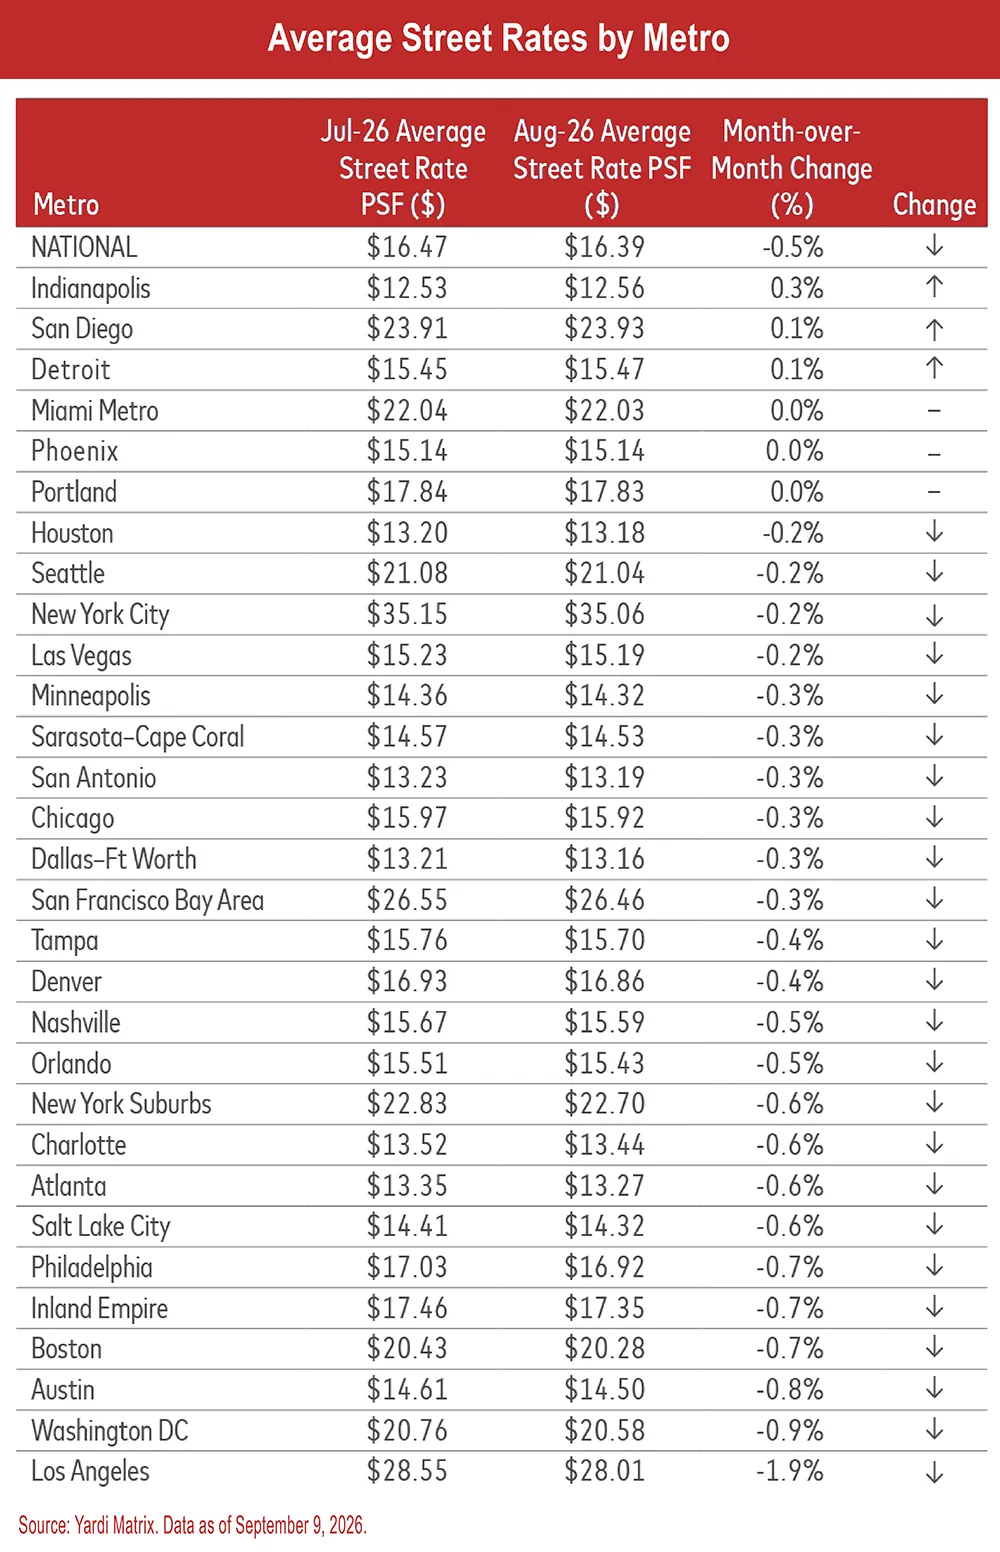
Advertised rate declines widen despite slowing supply. Advertised rate performance weakened in August as soft demand and lingering lease-up supply pressures outweighed the benefits of a slowing national development pipeline. Nationally, advertised rates declined 1.9 percent year over year in August, compared with declines of 1.6 percent in July and 1.5 percent in June. The national average rate dropped to $16.39 per square foot.
Most of Yardi Matrix’s top 30 metros recorded larger year-over-year advertised rate declines in August than in July 2026 or August 2025, pointing to broad-based weakness. Only four top metros experienced an annual increase in advertised rates for non-climate-controlled (NCC) units, while Austin and San Francisco were the only two markets where rates for climate-controlled (CC) units increased.
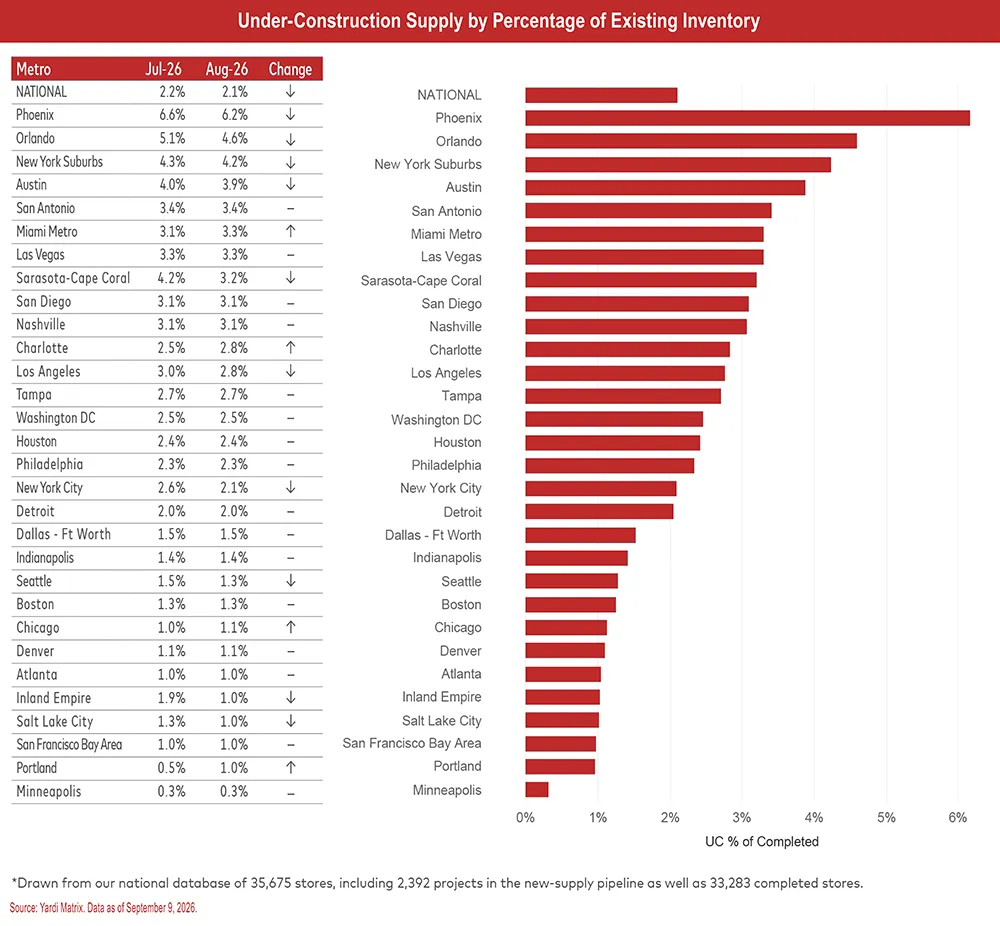
Nationally, Yardi Matrix tracks a total of 2,392 self-storage properties in various stages of development, including 594 under construction, 1,499 planned, and 299 prospective properties. Under-construction projects represented 2.1 percent of existing stock by NRSF at the end of August, down 10 basis points month over month. Yardi Matrix also maintains operational profiles for 33,283 completed self-storage facilities in the U.S., bringing the total dataset to 35,675.
REIT advertised rates declined 3.1 percent year over year and 0.9 percent month over month in August, compared with declines of 1.2 percent and 0.3 percent, respectively, among non-REIT competitors. The sharper REIT declines reflect their more responsive pricing strategies amid weaker seasonal demand.
See August 2026 Year-Over-Year Rent Change for Main Unit Sizes chart.
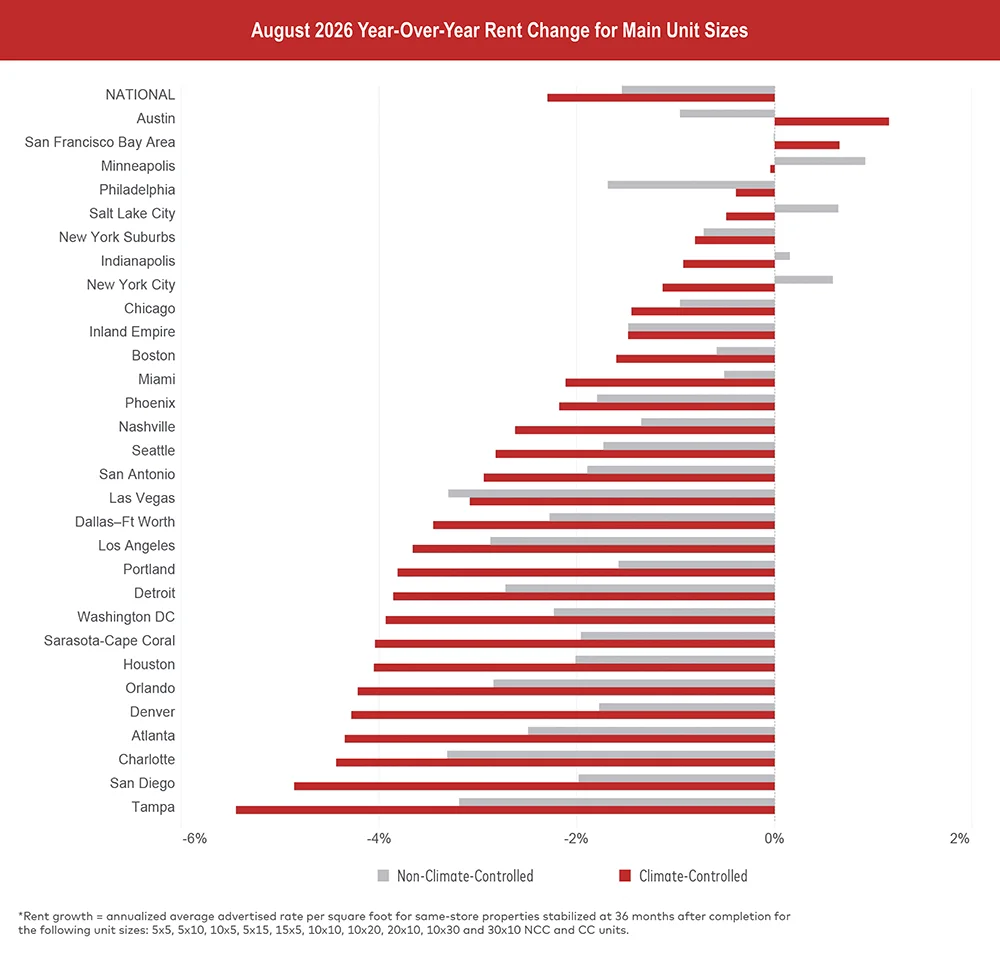
Month-over-month declines were widespread in August, with 24 of the top 30 metros posting decreases in advertised rates.
See National Average Street Rates PSF for Main Unit Types chart and Average Street Rates by Metro table.
San Francisco has the strongest demand backdrop of the four, combining limited lease-up supply with the highest population and multifamily rent growth among the top 30 metros. Minneapolis and Salt Lake City also benefit from comparatively modest lease-up supply and improving demand fundamentals. Slowing development is supporting rents in Minneapolis, while Salt Lake City’s positive performance contrasts with continued declines across several higher-supply Mountain West markets.
See Self-Storage Major Metro Summary chart.
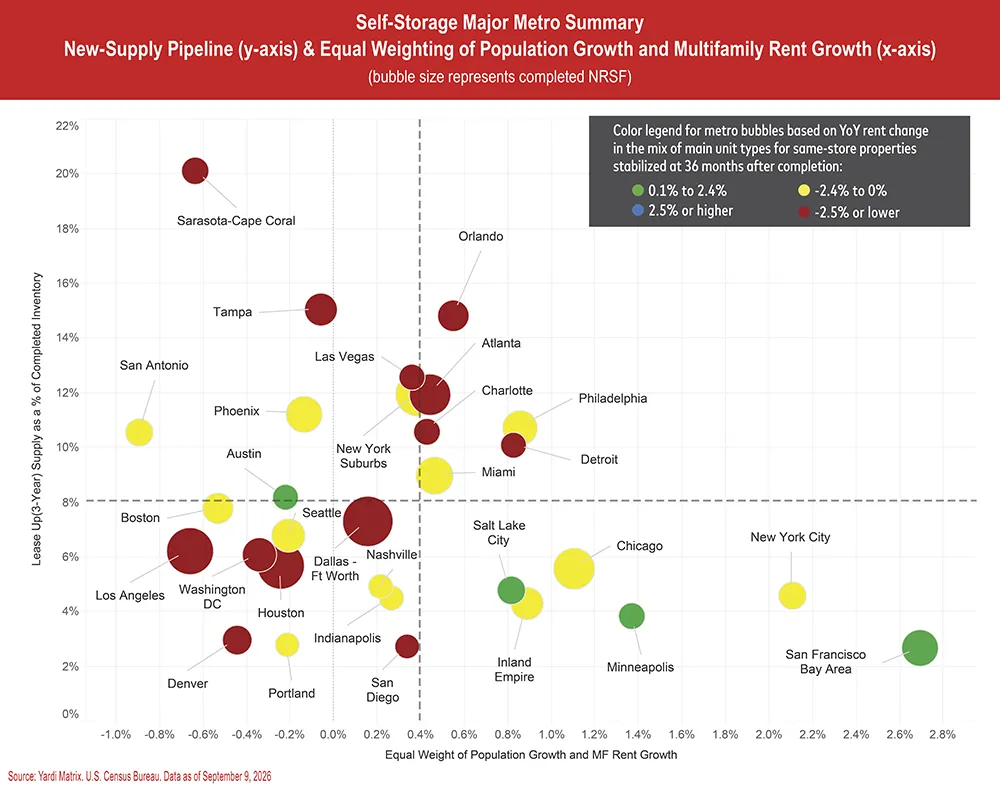
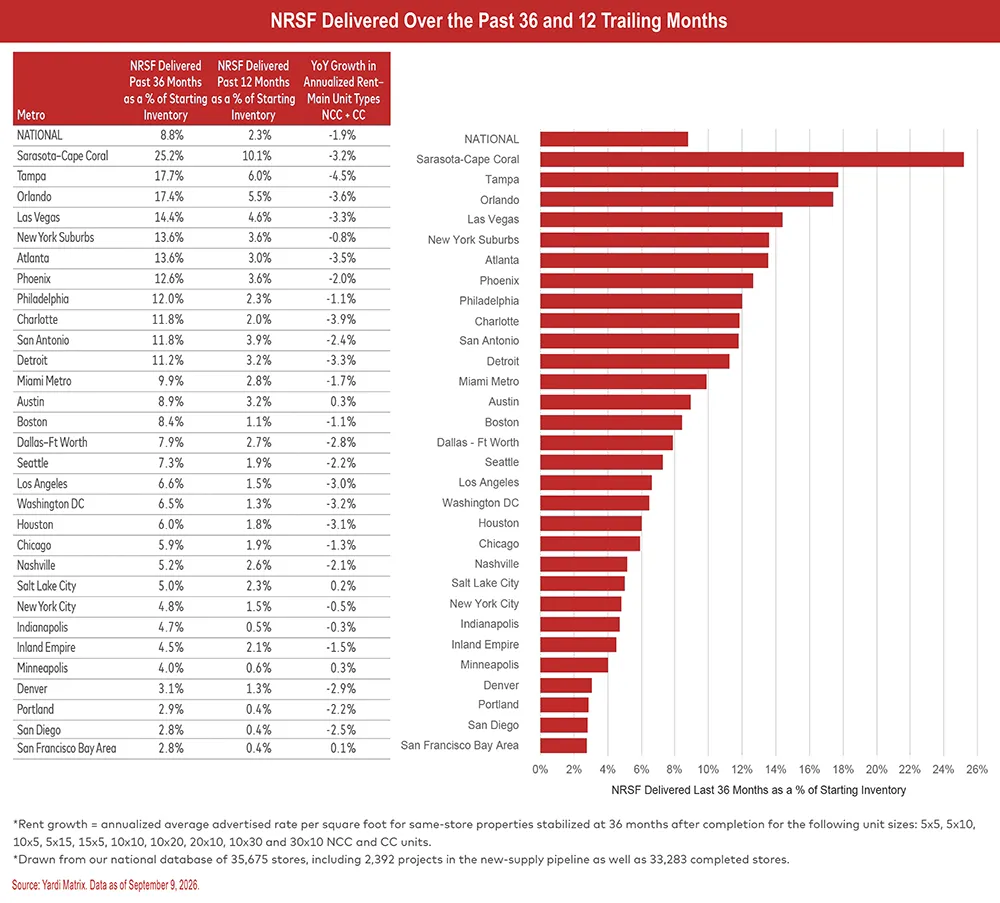
COVID-era growth markets continue to weigh disproportionately on national performance as operators work through elevated lease-up supply. Sarasota–Cape Coral remains the most heavily supplied top-30 metro, as total inventory has grown by one-quarter in just three years, while Tampa and Orlando also remain near historically high lease-up supply levels. Although deliveries are slowing, these Sun Belt markets will need time to absorb existing lease-up inventory, and their large storage footprints amplify their impact on national trends.
See NRSF Delivered Over the Past 36 and 12 Trailing Months table and chart.
San Diego’s under-construction supply was unchanged in August but has more than doubled from 1.4 percent of stock a year ago, while planned supply has risen to 6.1 percent of inventory. After benefiting from limited recent deliveries, the metro could face renewed supply pressure as its expanding pipeline begins to deliver.
See Under-Construction Supply by Percentage of Existing Inventory table and chart.