hile we discussed industry numbers from other vendors in Section 1, only the data from Radius+ and the MSM 2024 Top Operator’s list were used for this section.
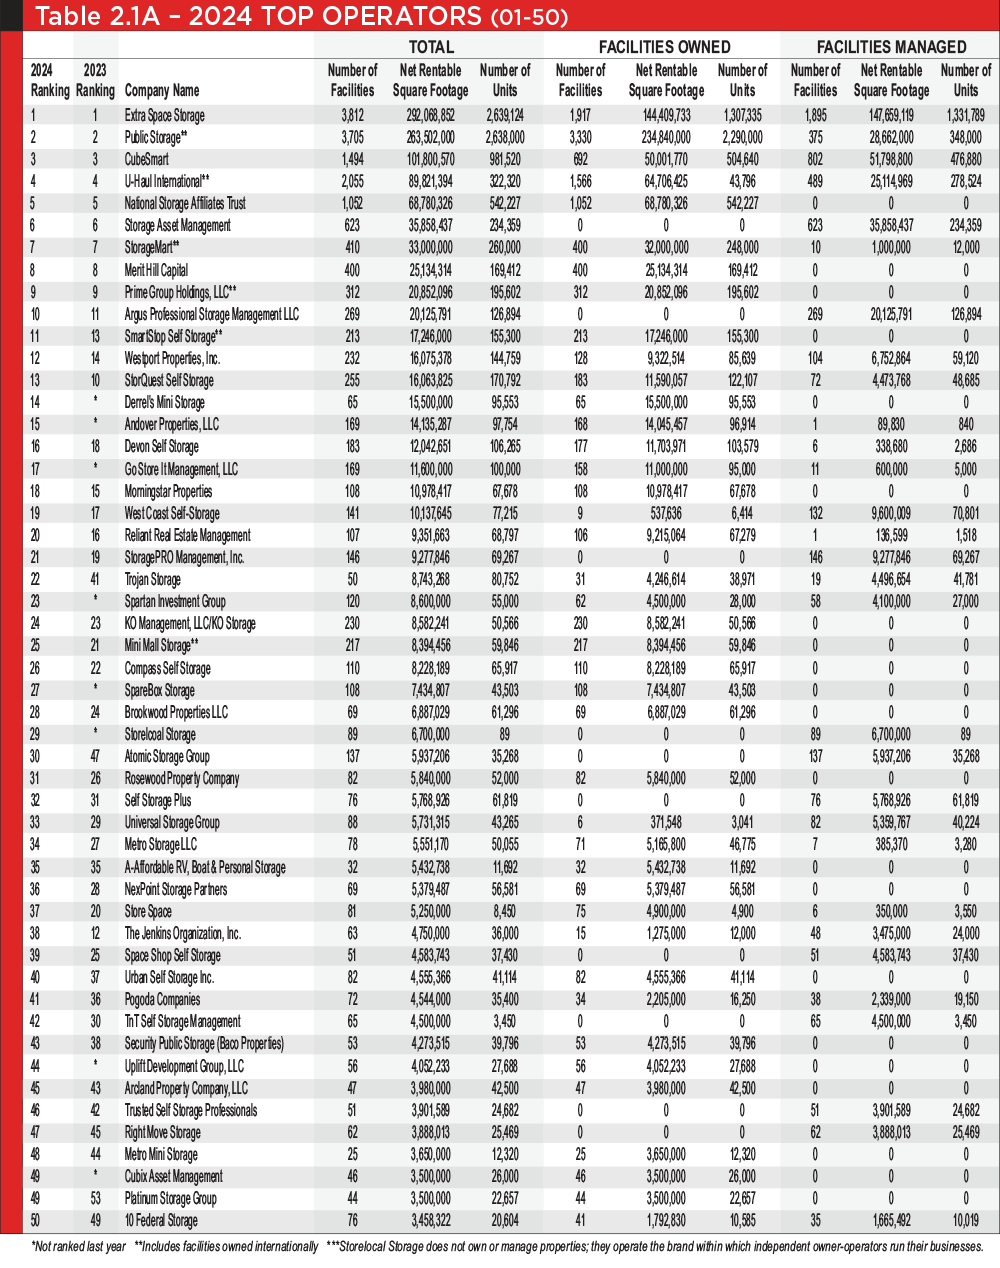
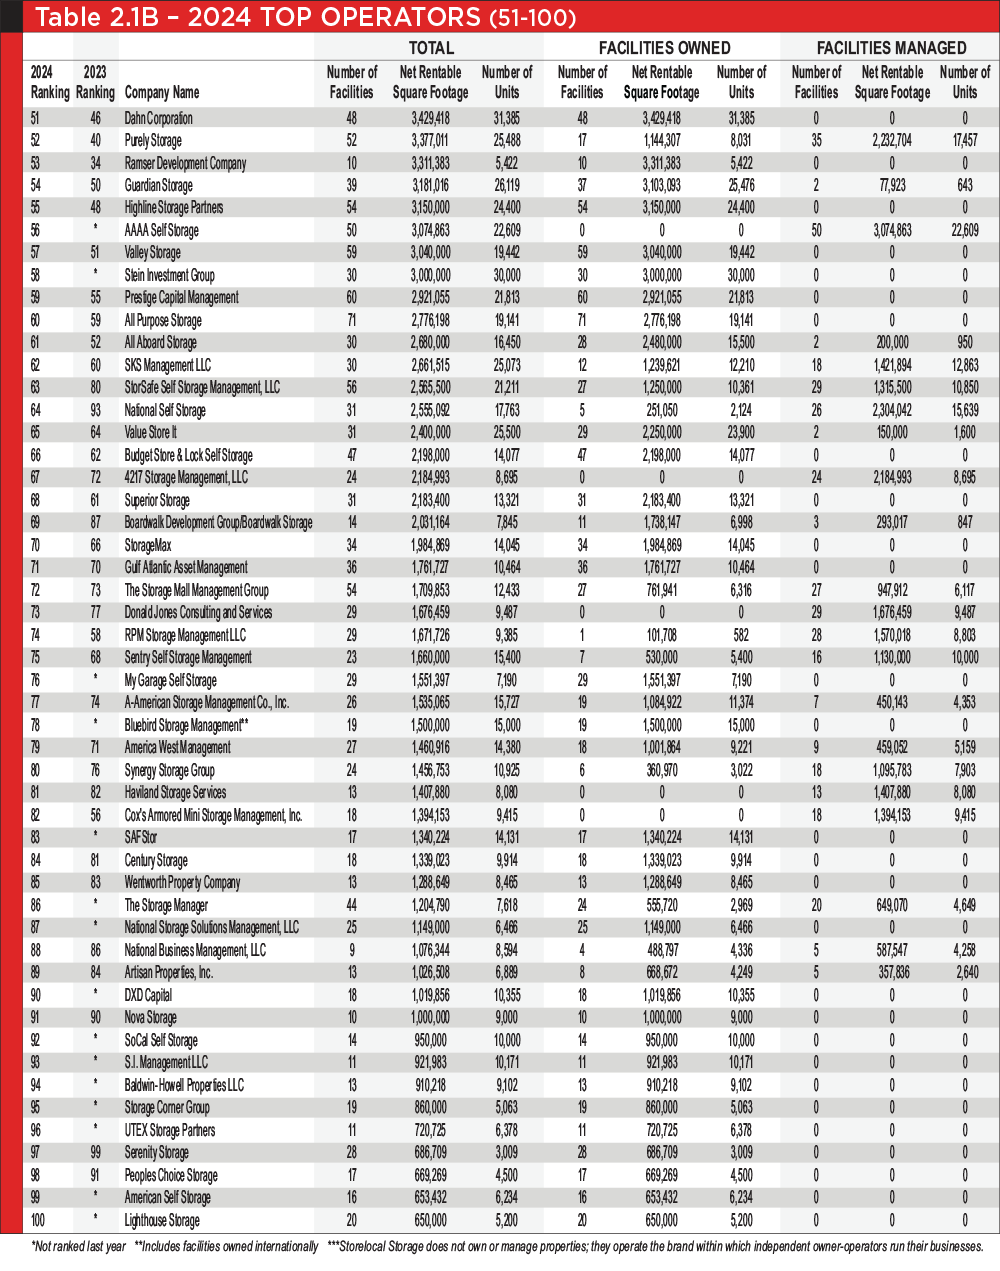
The 2024 Top Operators list (published by MSM in November 2024) and national data show a change in the trend we have seen for many years in the self-storage industry. Instead of showing increased consolidation of ownership, it shows the opposite: The market share of small independent owner-operators grew in number of facilities and square footage, as seen in Tables 2.1A and 2.2B on the following pages. As mentioned in Section 1, as data sources improve and it becomes easier to compare one year to the next, it will be very interesting to see if this trend continues in the years to come.
In analyzing ownership data among the top 100 operators, we look at four groups:
- Public companies (REITs and U-Haul),
- Other top operators with portfolios of both properties they own and properties they manage,
- Other top operators whose portfolios only include properties they own, and
- Other top operators whose portfolios only include properties they manage.
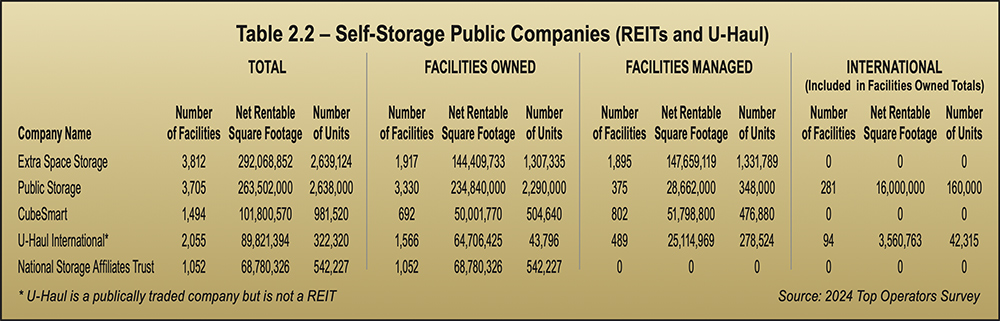
The five largest self-storage operators are REITs, comprising 20.9 percent of facilities and 28.5 percent of square footage. Their portfolios include properties they own and manage, except for National Storage Affiliates (NSA), whose portfolio does not include any third-party managed facilities as of 2024.
Other top operators, ranked No. 6 to 100 on the list, have portfolios of owned facilities only, managed facilities only, or both owned and managed. Moreover, 33 other top operators have portfolios of properties they own and manage. Other top operators whose portfolios only include properties they own comprise 48 companies on MSM’s 2024 Top Operators list. Finally, 15 companies on the Top Operators list only provide third-party management. They do not own any facilities.
Adding up the five public companies (REITs and U-Haul International), 33 top operators with both owned and managed facilities, 48 with owned facilities only, and 15 with exclusively managed facilities brings us to 101 operators on the 2024 Top Operators list. But that’s not a mistake! Cubix and Platinum tied for the No. 49 position, and both are included in the count, bringing it to 101 instead of 100.
This year, 23 operators are new to MSM’s Top Operators list. Of those 23, 17 own properties exclusively and do not offer third-party management.
For many years, each REIT’s portfolio has grown significantly. This year, Extra Space’s, Public Storage’s, and CubeSmart’s portfolios showed growth like years past, but U-Haul was only slightly up and National Storage Affiliates actually shrunk, due to selling stores and changing its operational structure. See Table 2.2 on page 24.
Increasing by 146 facilities, Extra Space’s facility count grew 4 percent and square footage grew 3.9 percent. Adding 172 facilities, Public Storage now has 4.9 percent more facilities and 5.5 percent more square feet than last year. CubeSmart had the fasted growth rate, increasing by 156 facilities, representing growth of 11.7 percent in facility count and 10.5 percent in square footage.
Notice that all three portfolios showed faster growth in facility count than in square footage, indicating that smaller facilities are being added to their portfolios. Perhaps the supply of large facilities available for the REITs to buy is shrinking. This trend is visible in facility and square footage metrics for the entire industry as well as for these REITs.
On the other hand, U-Haul increased facility count by only 1.9 percent but increased square footage by 4.4 percent; hence, while fewer facilities were added to the portfolio, they were large ones, perhaps with more RV and boat storage than the average facility.
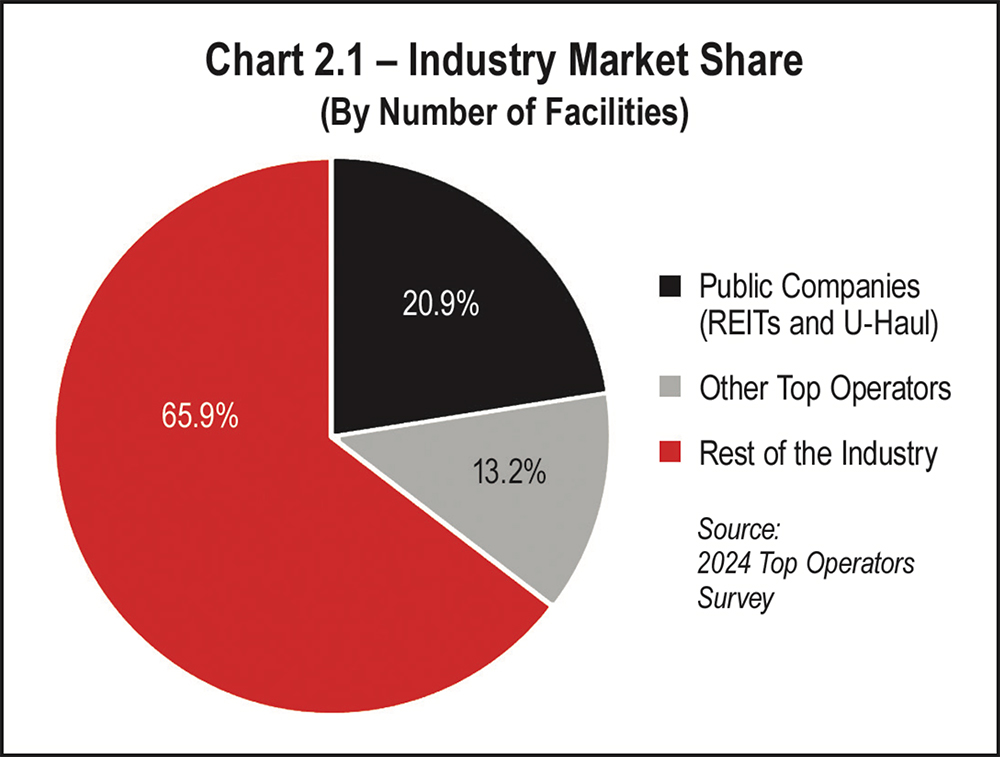
When measured by the number of facilities, industry market share paints a better picture for the independent owner-operator than in recent years. The number of facilities owned by the “Rest of Industry,” i.e., independent owner-operators who are not among the top operators, grew to 65.9 percent this year, up from 64.6 percent last year. This year’s market share is higher than the previous year as well, reported as 65.3 percent in the 2023 Self-Storage Almanac.
Likewise, “Other Top Operators,” as seen in Table 2.1, also increased number of facilities to 13.2 percent this year. Last year they comprised 12.9 percent market share, which was the same percentage reported in the 2023 Self-Storage Almanac.
Meanwhile, public companies’ (REITs and U-Haul) market share as measured by facility count decreased to 20.9 percent this year, down from 22.5 percent and 21.9 percent in the 2024 Self-Storage Almanac and the 2023 Self-Storage Almanac.
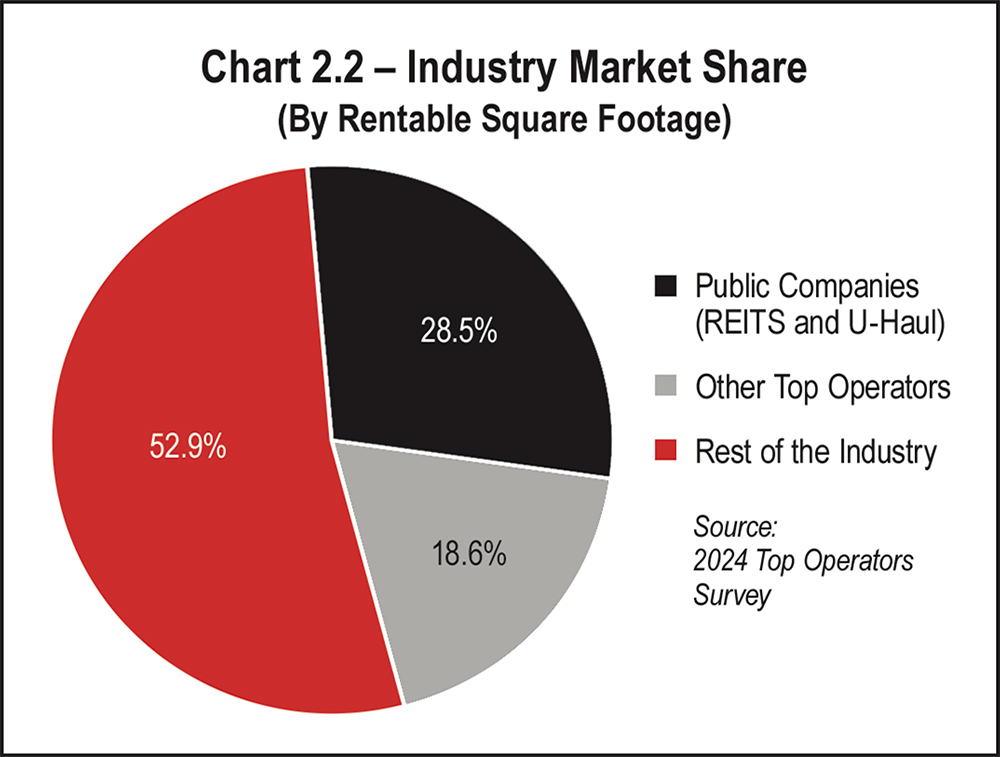
Measuring industry market share by square footage shows even more dramatic gains by small operators. At 52.9 percent this year, “Rest of Industry” picked up 12.7 percentage points, up from 40.2 percent reported in the 2024 Self-Storage Almanac and 41 percent in the 2023 Self-Storage Almanac.
The market share of “Other Top Operators” ranked No. 6 to 100 decreased to 18.6 percent of the industry’s total square footage, down from 22 percent and 22.4 percent in 2024 and 2023, respectively.
Public companies’ market share likewise declined. This year, REITs and U-Haul represent 28.5 percent of the market as measured by square footage, down 9.1 percentage points from 2024, when they had 37.6 percent market share. Their market share in 2023 was 36.6 percent.
Taking a broad picture of all the top operators, a dozen operators experienced significant changes in rankings. Five reported positive gains:
- Trojan shot up to No. 22 from No. 41.
- Atomic Storage Group rose to No. 30 from No. 47.
- StorSafe Self Storage Management, LLC jumped up to No. 63 from No. 80.
- National Self Storage climbed up to No. 64 from No. 93.
- Boardwalk Development Group/Boardwalk Storage moved up to No. 69 from No. 87.
Seven operators experienced double-digit drops in ranking:
- The Jenkins Organization, Inc. moved down to No. 38 from No. 12.
- Space Shop Self Storage declined to No. 39 from No. 25.
- TnT Self Storage Management dropped to No. 42 from No. 30.
- Purely Storage moved down to No. 52 from No. 40.
- Ramser Development dropped to No. 53 from No. 34.
- RPM Storage Management LLC declined to No. 74 from No. 58.
- Cox’s Armored Mini Storage Management, Inc. dropped to No. 82 from No. 56.
The Jenkins Organization, Inc. dropped to No. 38 with 63 facilities and 4,750,000 net rentable square feet (NRSF) from last year’s No. 12 spot, with 49 facilities and 16,400,000 NRSF. They shed three quarters of their third-party managed portfolio, and their owned facility count increased by 1, increasing to 15.
Space Shop Self Storage declined to No. 39 from No. 25 last year. It’s store count shrunk to 51 with 4,583,743 NRSF from 83 with 6,464,163 NRSF. The company sold all 36 facilities it owned, while marginally increasing the number of managed facilities.
TnT Self Storage Management dropped to No. 42 from No. 30 last year. They show a net loss of 10 third-party managed stores, reducing portfolio size to 65 with 4,500,000 NRSF from 75 with 5,200,345 NRSF.
Purely Storage increased two facilities in their third-party managed portfolio, but they declined in ranking to No. 52 from No. 40 the year prior. This year they have more stores, but they are smaller. The 2024 Top Operator list reports 52 stores with 3,377,011 NRSF, whereas last year they only had 50 stores but more square footage (3,879,891 NRSF).
Ramser Development reported a difference of about a dozen facilities, dropping in rank to No. 53 from No. 34 last year. They shed all nine third-party managed facilities, and their store count is down by two facilities.
RPM Storage Management LLC declined in rank to No. 74 from No. 58 last year. They are managing only 28 facilities now, instead of 40, and their owned facility count is down by one. The portfolio decreased to 29 stores with 1,671,726 NRSF, which is down from 42 stores with 2,444,700 NRSF.
Cox’s Armored Mini Storage Management, Inc. dropped to No. 82 this year, down from No. 56 the year before. They had a net loss of two facilities in their third-party managed portfolio, which consists of 18 stores with 1,394,153 NRSF this year. Last year they managed two more facilities for a total of 20 stores and 2,511,492 NRSF. That’s a loss of 1,117,339 NRSF. Several of the facilities that left the portfolio were very large RV/boat storage facilities.
There are 48 companies in MSM’s 2024 Top Operators list with portfolios consisting exclusively of properties they own. The top 10 of these operators are included in Table 2.3 and Chart 2.3, which shows relative size based on square footage.
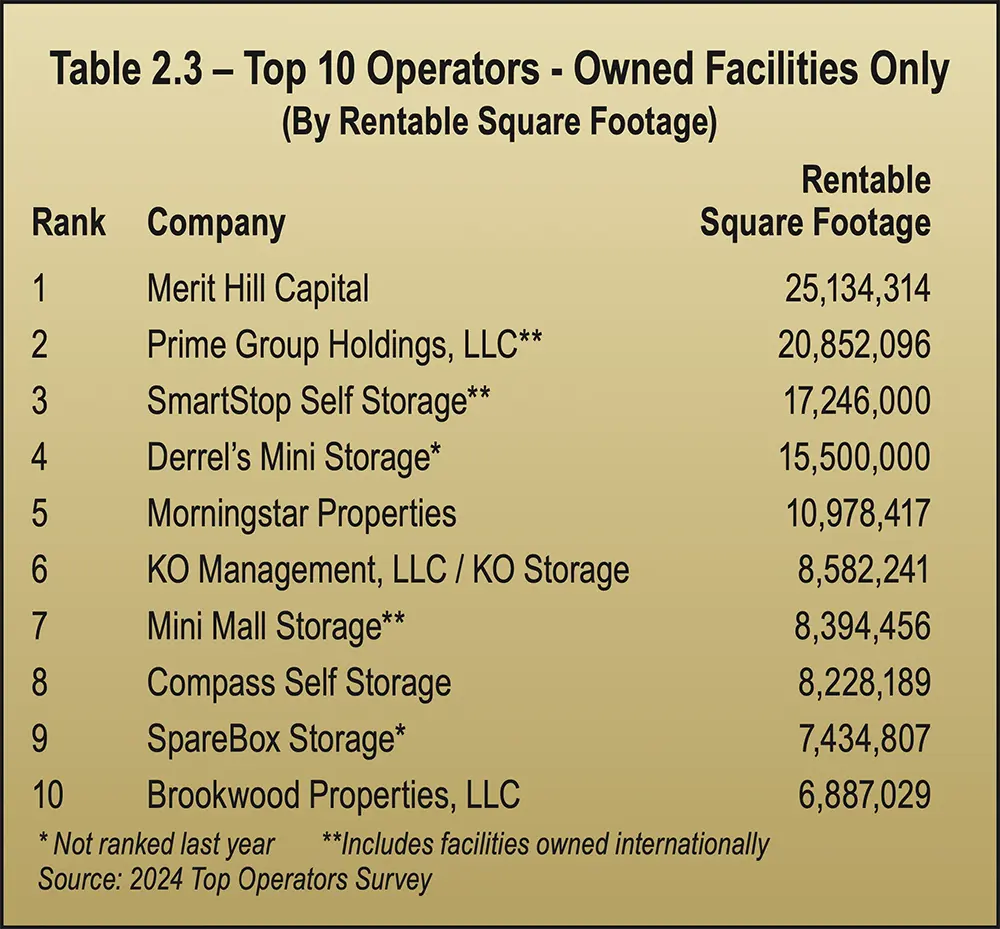
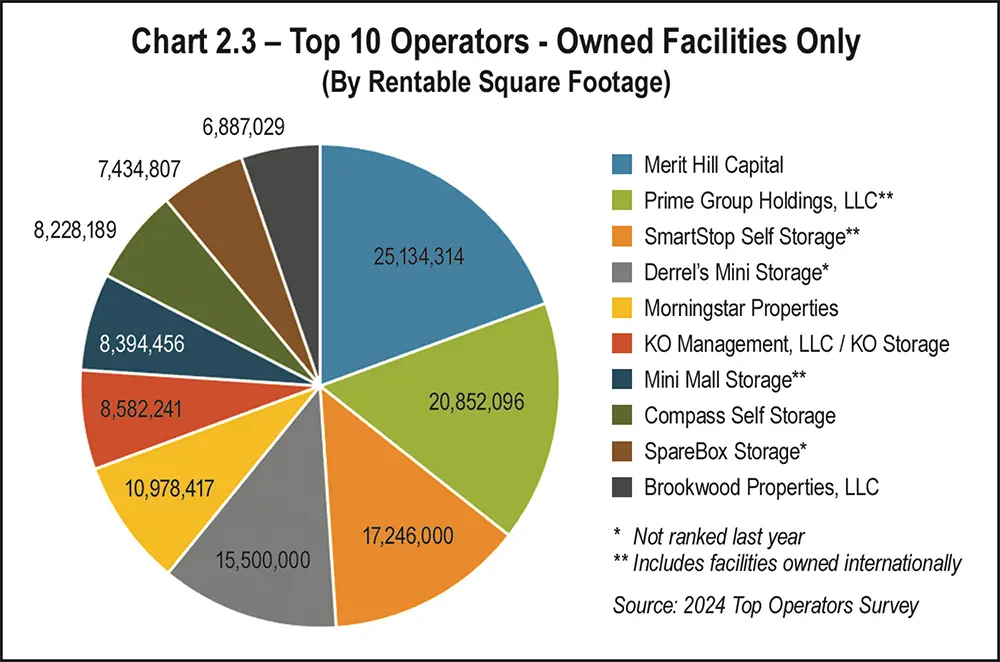
New to the list this year and moving into the No. 4 position is Derrel’s Mini Storage, a regional owner-operator in California. Morningstar Properties moved down from No. 4 to No. 5. KO Management, LLC moved up in one rank to No. 6. Mini Mall Storage moved down two positions to No. 7, as did Compass Self Storage, which now in the No. 8 slot.
SpareBox Storage joined the list of Top 10 Operators (non-REIT) in the No. 9 position.
Like Mini Mall, Brookwood Properties LLC moved down two positions into the last spot on this list.
Rosewood and NexPoint were bumped off the Top 10 list this year by Derrel’s and SpareBox, but they still came in the respectable positions of No. 11 and No. 13.
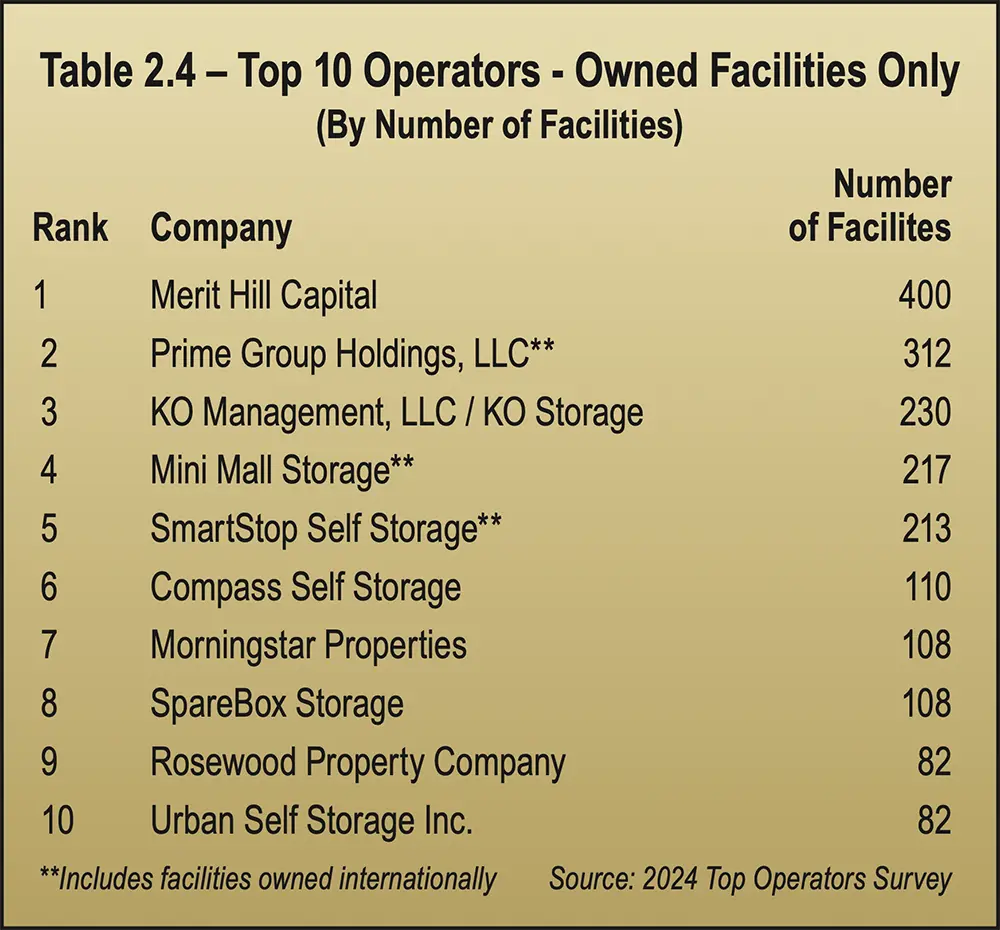
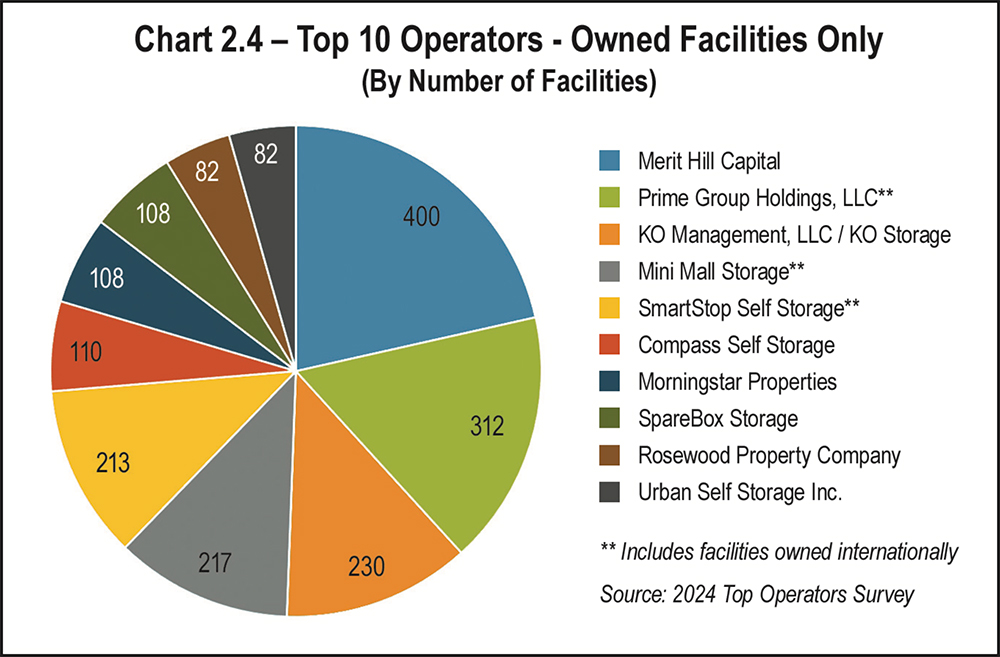
We rank the Top 10 Operators by square footage, as shown in Table 2.3 and Chart 2.3, or by number of facilities, as shown in Table 2.4 and Chart 2.4.
Eight companies appear on both lists. The top two are in the same position (Merit Hill and Prime).
KO ranks higher in number of facilities (No. 3) than square footage (No. 6). Likewise for Mini Mall, which is No. 4 in number of facilities and No. 7 in square footage.
With facilities larger on average than others, SmartShop has the No. 5 position when ranked by number of facilities, whereas it ranks No. 3 when measured by NRSF.
Compass ranks higher for number of facilities, at No. 6, than square footage (No. 8).
Morningstar is the opposite, ranking No. 7 in number of facilities but No. 5 by square footage. It has 108 facilities; the same amount as SpareBox, which ranks No. 8 on the facility count list and No. 9 on the square footage list.
Rosewood and Urban earned spots No. 9 and No. 10 on the list measuring by number of facilities, even though they were bumped off the list measuring size by NRSF. They both have 82 facilities in their portfolios.
Derrel’s and Brookwood do not rank among the top 10 largest portfolios when measured by number of facilities. Derrel’s comes in at No. 14 and Brookwood at No. 12, because they have fewer but larger facilities.
Comparing this year’s data to last year’s, Merit Hill remains No. 1 and Prime No. 2 on both measures last year and this year.
KO and Mini Mall changed positions this year, with KO in No. 3 and Mini Mall in No. 4. SmartStop retains the No. 5 position again this year. Compass moved up the list to No. 5; last year it was No. 7.
Morningstar moved down the list to No. 7; it was No. 6. Rosewood also moved down one spot, from No. 8 to No. 9.
SpareBox and Urban join the list this year in spots No. 8 and No. 10, when measured by facility count. A mentioned earlier, Brookwood and NexPoint fell off this list this year. SpareBox, being the newcomer to the list, ranked slightly higher in the number of facilities rank than NRSF, appearing in the No. 8 spot on this list but No. 9 on the NRSF list. (See Table 2.3 and Chart 2.3.) SpareBox also bumped Rosewood down one rank to No. 9.
Urban Self Storage appeared on this list of top 10 operators for the first time this year because it reported 82 owned facilities and zero third-party managed facilities. Last year, Urban reported zero owned facilities and 78 managed facilities. Clearly, Urban has changed its strategy.
Also interesting is that National Storage Affiliates (NSA) shows zero managed facilities this year, because of the change in their PRO structure, thereby eliminating the 120 managed facilities NSA reported in the 2023 Top Operators list. This, plus the sale of the large portfolio mentioned above, brought NSA’s overall facility count down to 1,052 this year, compared to 1,237 in 2023.
SAM, Argus, and StoragePRO remain in the top three spots of the top 10 management companies when measured by square footage.
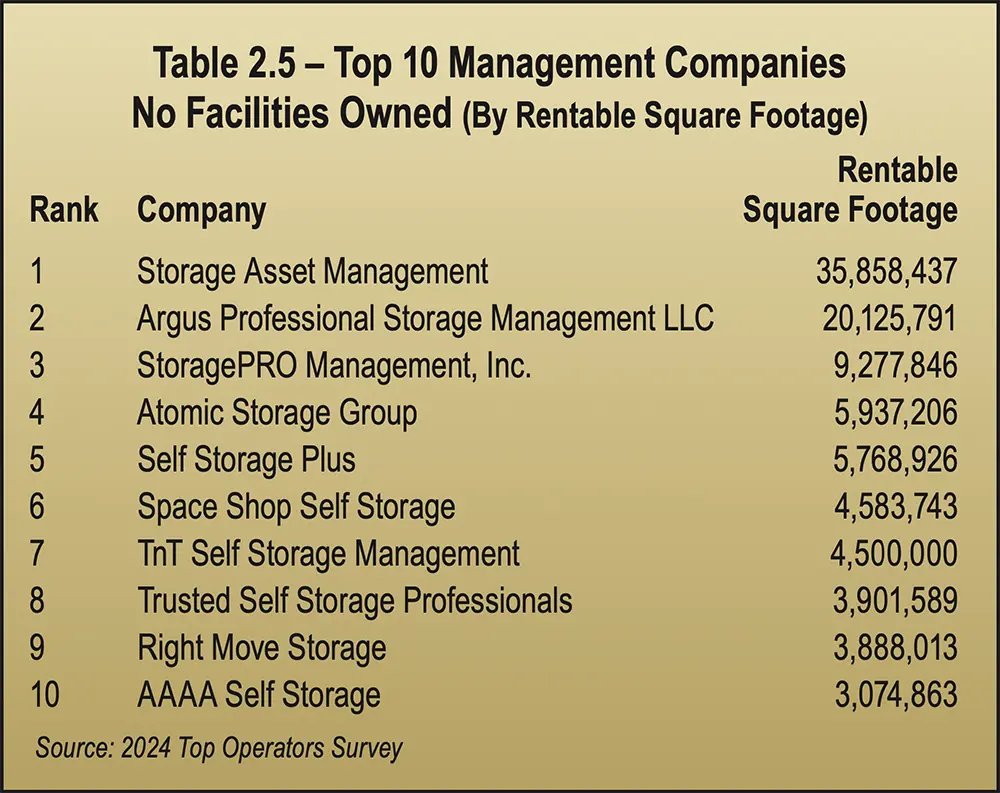
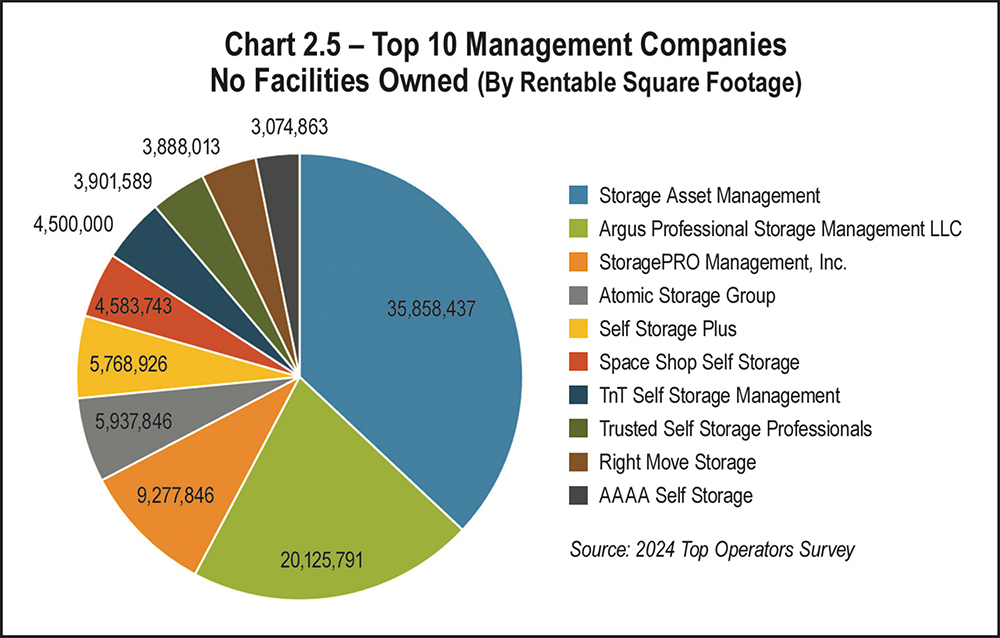
Self Storage Plus retained the No. 5 position.
Like Atomic, Space Shop Self Storage also climbed far up the top management company list this year, to the No. 6 spot, increasing their managed facility count to 51 from last year’s 47. Overall, their ranking declined to No. 39, compared to last year’s No. 25 because they sold all 36 facilities of the facilities they reported as owned facilities in MSM’s 2023 Top Operators list.
TnT slid down the list to No. 7, compared to the No. 4 position last year. As mentioned earlier, TnT’s third-party managed portfolio shrank by 10 facilities, down from 75 reported last year to 65 reported this year, which also decreased their overall ranking among top operators to No. 42, down from No. 30.
Trusted Self Storage Professionals and Right Move Storage retained the No. 8 and No. 9 positions among the top 10 management companies.
Dropping off the list is Cox’s Armored Mini Storage Management, which went from 20 larger facilities to 18 smaller facilities, as explained previously.
The No. 10 position was assumed by AAAA Self Storage, which wasn’t on last year’s list. This year, they manage 50 facilities and captured the last position among the top 10 management companies.
Copper Storage Management is not in this year’s list, but they ranked No. 6 on last year’s top 10 management company list, and No. 32 overall in 2023, with 174 third-party managed facilities. The year before that, the 2022 list ranked Copper No. 42 overall.
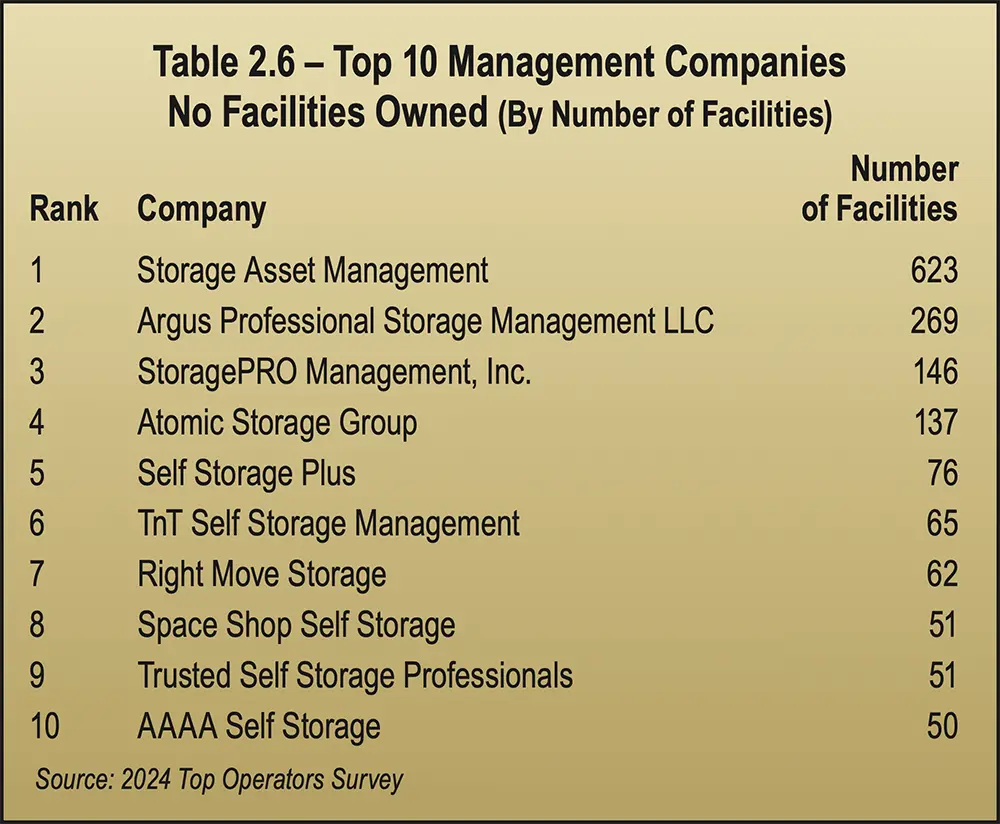
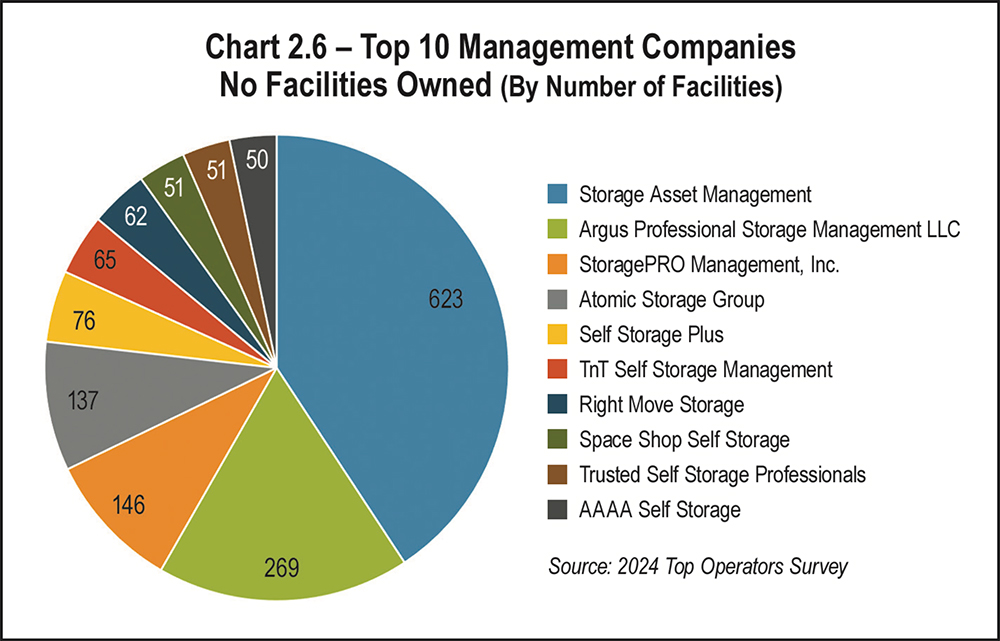
Now for a look at the top 10 management companies as measured by number of facilities. The No. 1 and No. 2 management companies by number of facilities are the same as square footage: SAM and Argus. In fact, SAM and Argus hold the No. 1 and No. 2 positions on both lists, both this year and last year.
When sorted by total number of facilities, the No. 3 spot this year goes to StoragePRO, taking Copper’s position on the list.
Atomic shot up to No. 4 on this list too, capturing the same position on both lists (number of facilities and square footage).
Self Storage Plus increased to No. 5 on this list. It was in the No. 7 position last year.
TnT remains in the No. 6 spot, and Right Move increased to No. 7 this year, from No. 8 last year.
Space Shop Self Storage moved into No. 8, after not being on the list last year.
Trusted Self Storage Professionals maintained the No. 9 position. Cox’s Armored Mini Storage Management, which dropped off the list, was replaced by AAAA Self Storage.
It also shows changes in market share that should grab your attention. This is the first year the data shows an increase in market share by the small, independent owner-operators, both in terms of number of facilities and square footage.
The changes are observable for operators whose strategy is to own facilities (only), provide third-party management (only), and for portfolios that include both owned and managed facilities.
This kind of change in industry ownership, and relative change in size, both up and down, suggest that the self-storage industry is more dynamic than it has been in recent years. Is there more flexibility and opportunity for the independent owner-operator now than in recent years? The COVID years were full of opportunity for owners of all sizes to buy and sell facilities. However, as this year’s data on rates and occupancy underscores, it’s more difficult to grow revenue than in recent years.
How these trends develop in the years to come will have a major impact on portfolios of all sizes, structures, and management styles. One thing is certain: These are indeed very interesting times!